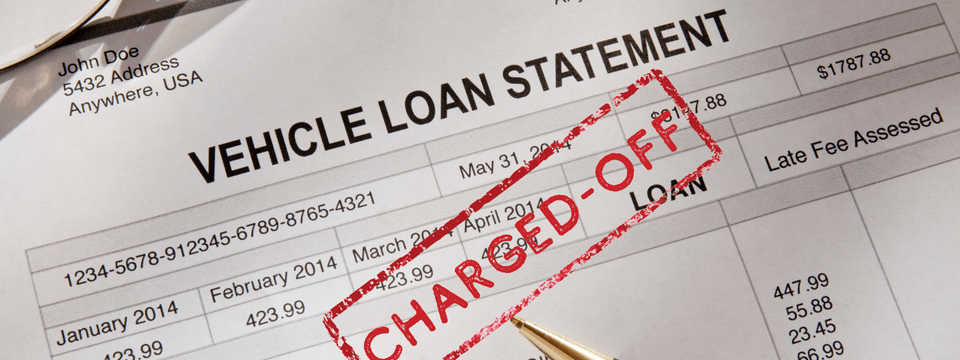
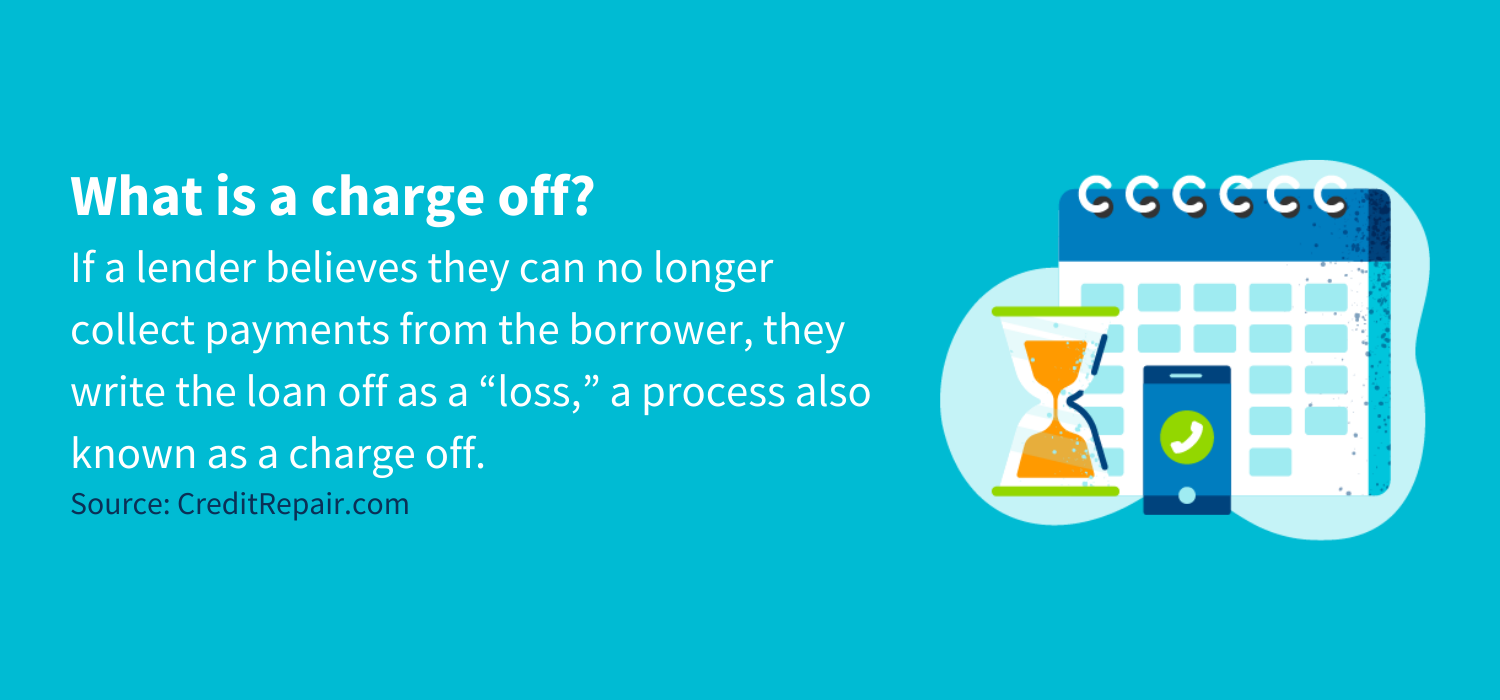
Ever wondered what a charge off on a car loan actually means? It’s a term that pops up often in credit reports, and more people are using it to understand their financial standing. A charge off happens when a lender decides you’re unlikely to pay the remaining balance, yet they still report the amount as a loss. Knowing this helps you spot trouble early.
Why does it matter? For a family trying to buy a used car, a charge off can lower your credit score by dozens of points, making future financing harder. Schools and community banks also view it as a sign of risk, which can affect the interest rates they offer. In short, spotting a charge off gives you a chance to fix problems before they snowball.
Take Maya, who missed several payments after a job loss. By month six, her lender put a charge off on her $12,000 balance. Maya’s credit report showed a black mark, but she used a $500 emergency fund to settle a portion of the debt and started a payment plan. Within a year, she regained a decent score and secured a lower‑interest loan.
Must Read
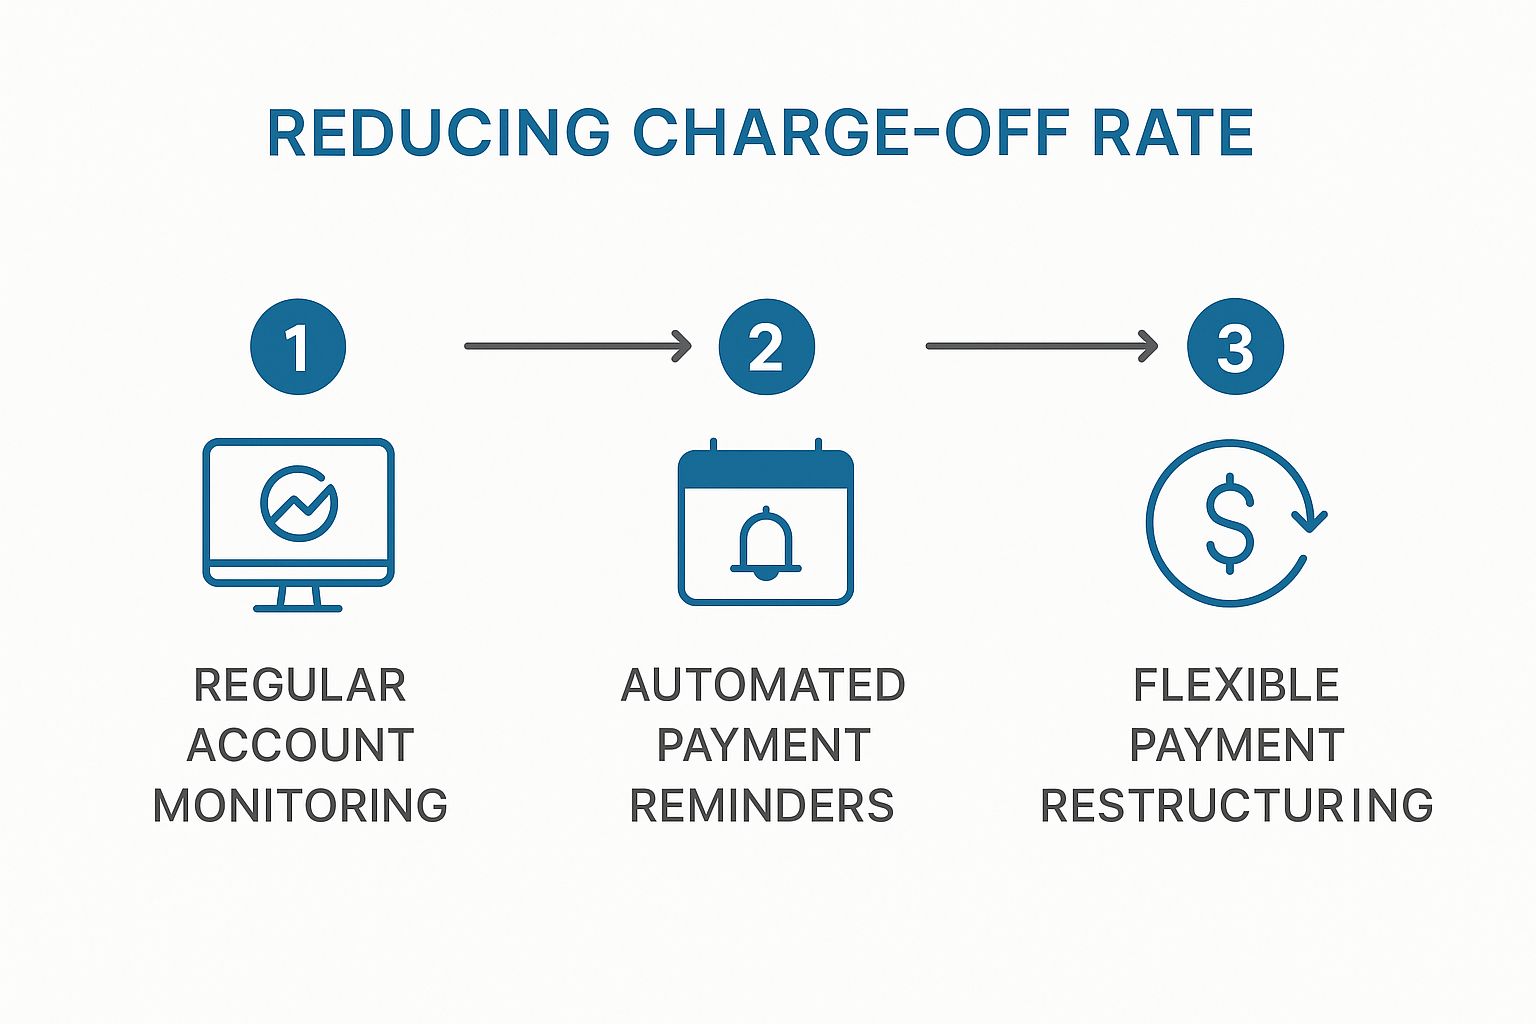
To avoid or manage a charge off, start by communicating with your lender as soon as you miss a payment. Ask for a hardship program or a temporary forbearance. If a charge off already appears, consider a goodwill adjustment or a debt‑validation letter to ensure the entry is accurate. Finally, set up automatic payments to keep future accounts healthy.
Understanding what a charge off means turns a scary credit report line into actionable knowledge. It helps individuals protect their families from higher loan costs and lets communities see responsible borrowing practices. By staying proactive, you turn a potential setback into a stepping stone toward financial stability.