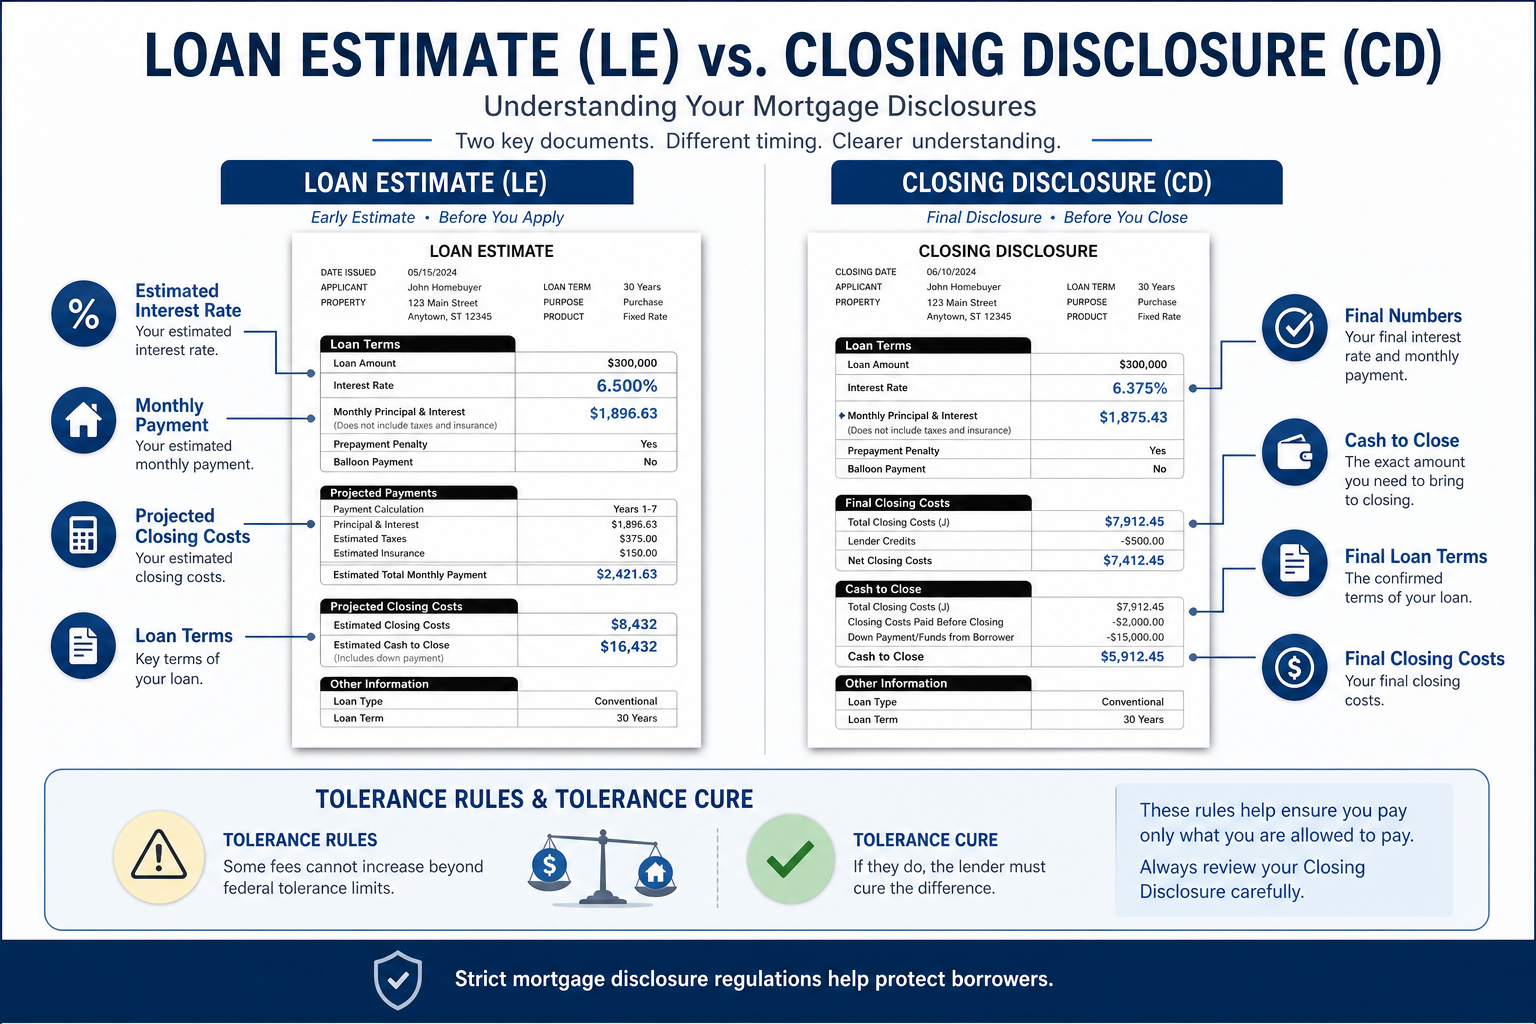
So, you've decided to refinance your mortgage. Congratulations — you're about to enter a world of paperwork so thrilling it could put a bedtime novel to shame. But before you sign your life away (again), you should probably understand what "closing costs" are, because they're sneaky little gremlins that love to crash the party.
What Even Are Closing Costs?
Closing costs are the fees you pay to finalize your new loan. Think of them as the cover charge at the most expensive club you've ever joined — except instead of drinks, you get bureaucratic headaches and a handshake from a stranger in a blazer.
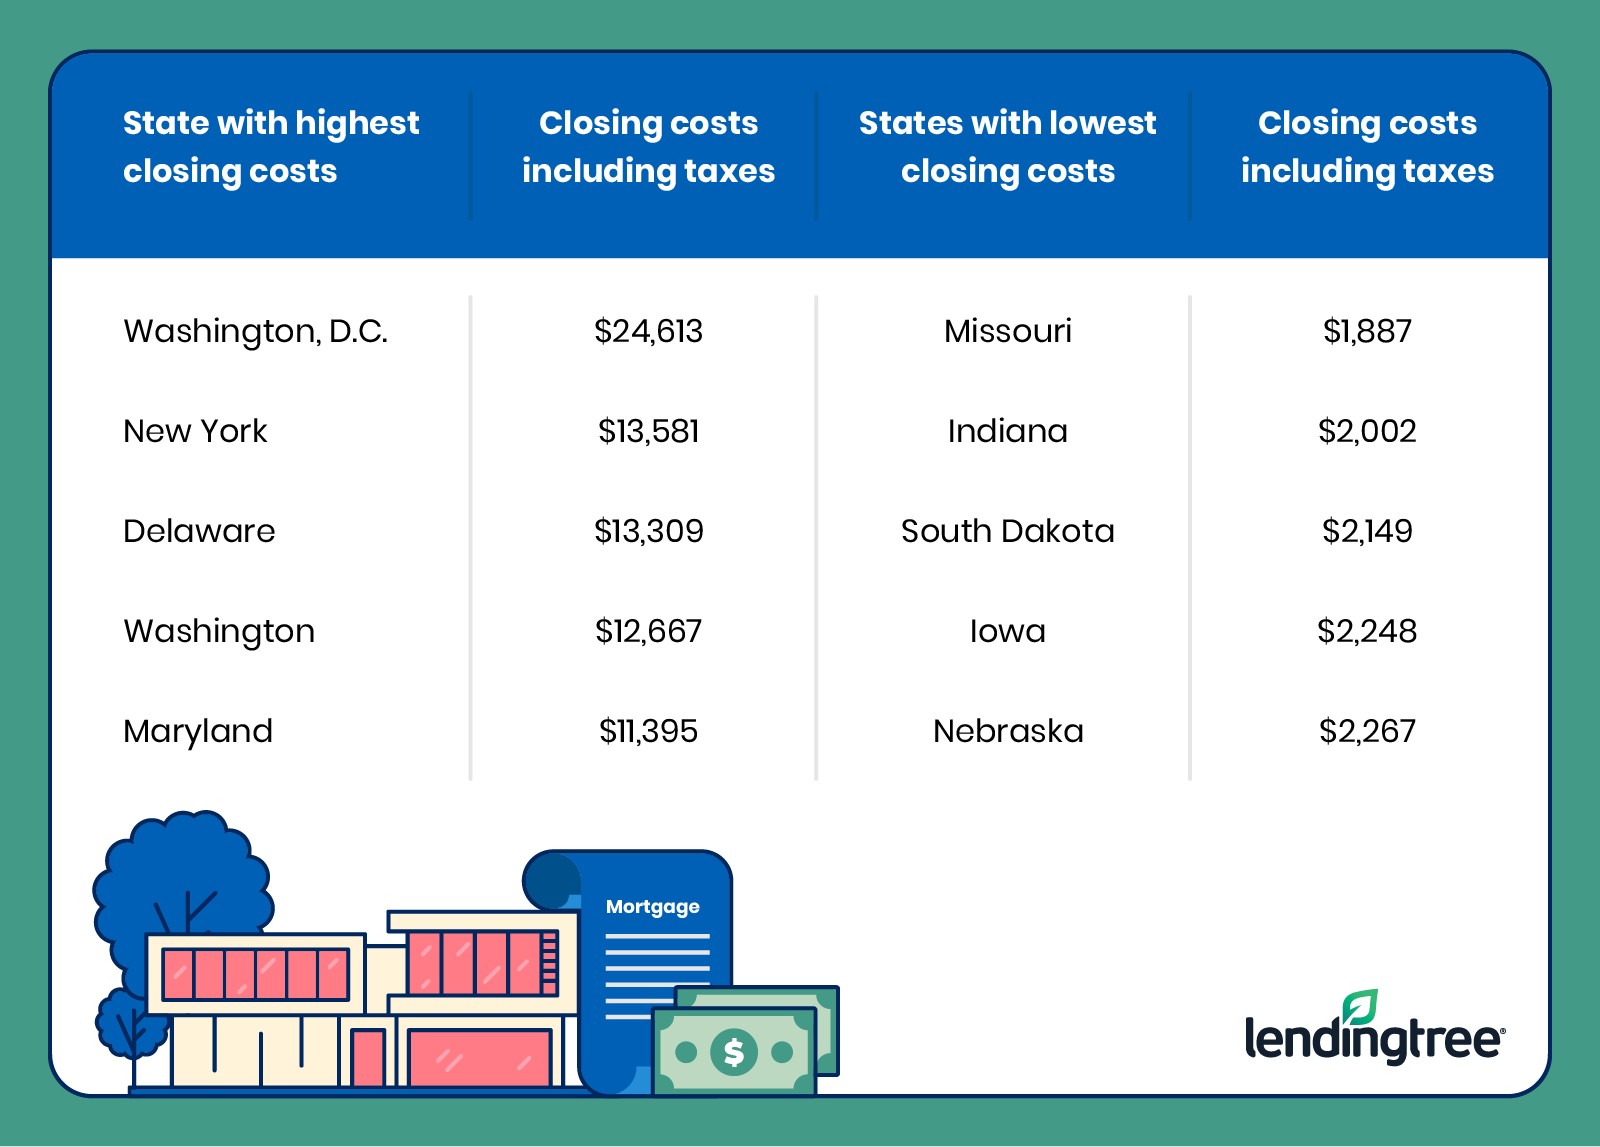
These costs usually range from 2% to 5% of your loan amount. So if you're refinancing a $300,000 mortgage, expect to shell out somewhere between $6,000 and $15,000. Ouch.
Must Read
The Usual Suspects
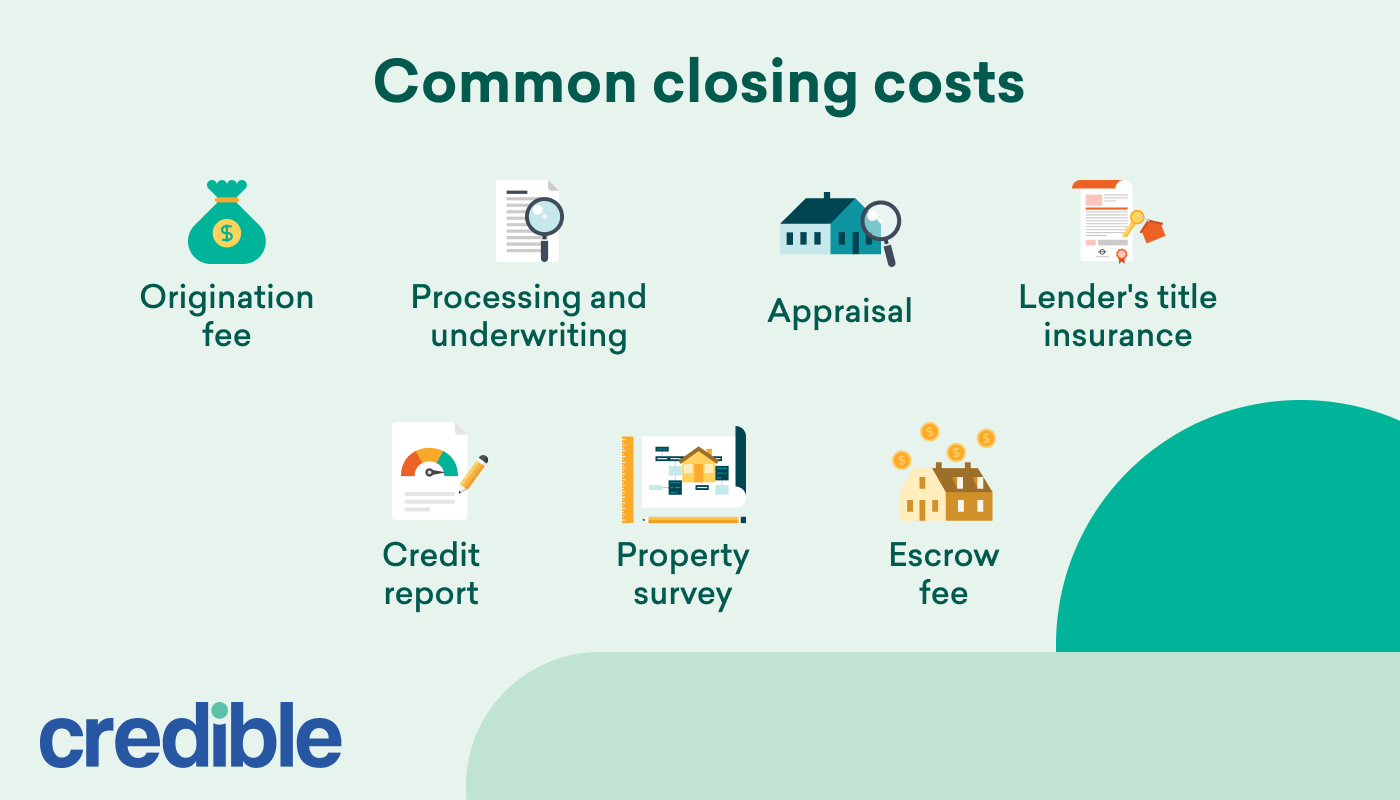
Your lender isn't just going to wave a magic wand and rearrange your debt — though honestly, wouldn't that be something? Here are the most common closing cost culprits.
Application fees are what your lender charges just to look at your paperwork. You're basically paying them to consider whether you're worthy. How flattering, right?
Origination fees cover the lender's work in creating your new loan, and this bad boy can run you roughly 0.5% to 1% of the loan. It's like a tip for doing their job, except you didn't have a choice in the matter.
 What Is An Underwriting Fee And How Does It Impact Your Closing Costs
The appraisal fee pays for a professional to peek at your home and declare its value. It usually costs between $300 and $700, depending on where you live and how dramatic the appraiser feels that day.
Title insurance and searches protect everyone from accidental property drama — the kind that belongs on a soap opera, not in your escrow account. Expect to pay a few hundred bucks here.
Credit report fees are a small charge to run your credit. This is weirdly your chance to spend money to find out if you have enough money. Life is a beautiful paradox.
 Closing Costs
Surprise! There's More
Oh, and don't forget about recording fees, where the local government charges you for updating public records. Nobody escapes the appetite of the government, not even at refinance time.
You may also need to pay prepaid interest, which covers interest that builds up between closing and your first payment. It's a tiny extra tax on being impatient, essentially.
How to Fight Back
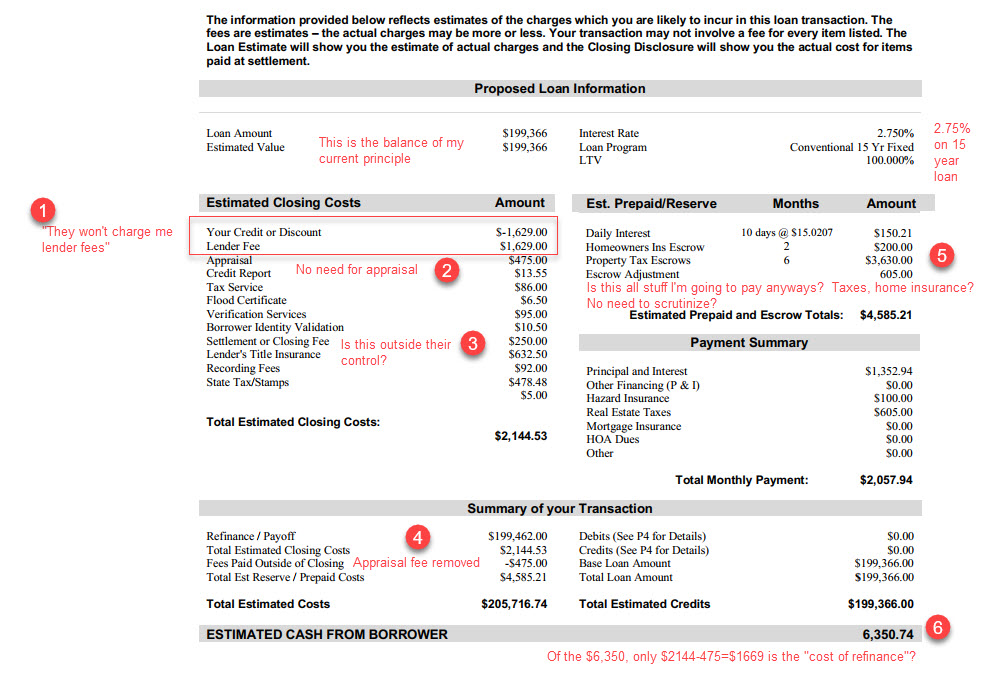
Here's the good news — closing costs are negotiable. Some lenders will eat part of the costs if you push back politely (or even not so politely — just kidding, be nice).
 Closing Costs For Refinance at Marsha Shain blog
You can also consider a "no-closing-cost" refinance, where the lender rolls those fees into your loan. Spoiler: that doesn't mean you aren't paying — you're just paying a little later and a little more. Nothing's free in this life.
The smartest move? Get at least three loan estimates from different lenders and compare them like a bargain-hunting champion. Closing costs don't have to break the bank — just your will to read all that fine print.
Refinancing can save you a fortune in the long run, so don't let fear of closing costs keep you on the couch. Just budget for it, laugh at the absurdity, and remember — every dollar spent here is another step toward a lighter mortgage.