
Okay, so let's talk about something that sounds incredibly boring but is actually secretly pretty cool. I'm talking about U.S. Bank Certificate of Deposit rates — or CDs, for short. Don't worry, I'm not going to put you to sleep. Stick with me on this one!
Ever put money in a jar labeled "vacation fund" so you wouldn't spend it on takeout? That's basically what a Certificate of Deposit does, only the bank actually pays you for your trouble. Your money sits there for a set period, and it earns more interest than it would just chilling in a regular savings account.
Why Should You Even Care?
Because your money deserves to work harder than you do! When you lock your cash into a CD at U.S. Bank, the bank rewards you with a higher interest rate in return. Think of it like tipping your money for being patient — it works while you forget about it entirely.
Must Read
Remember that neighbor who saved up for years and suddenly bought a boat? They might've been quietly earning solid returns on a Certificate of Deposit the whole time. Small, boring moves often add up to surprisingly sweet results.
How Do U.S. Bank CD Rates Work?
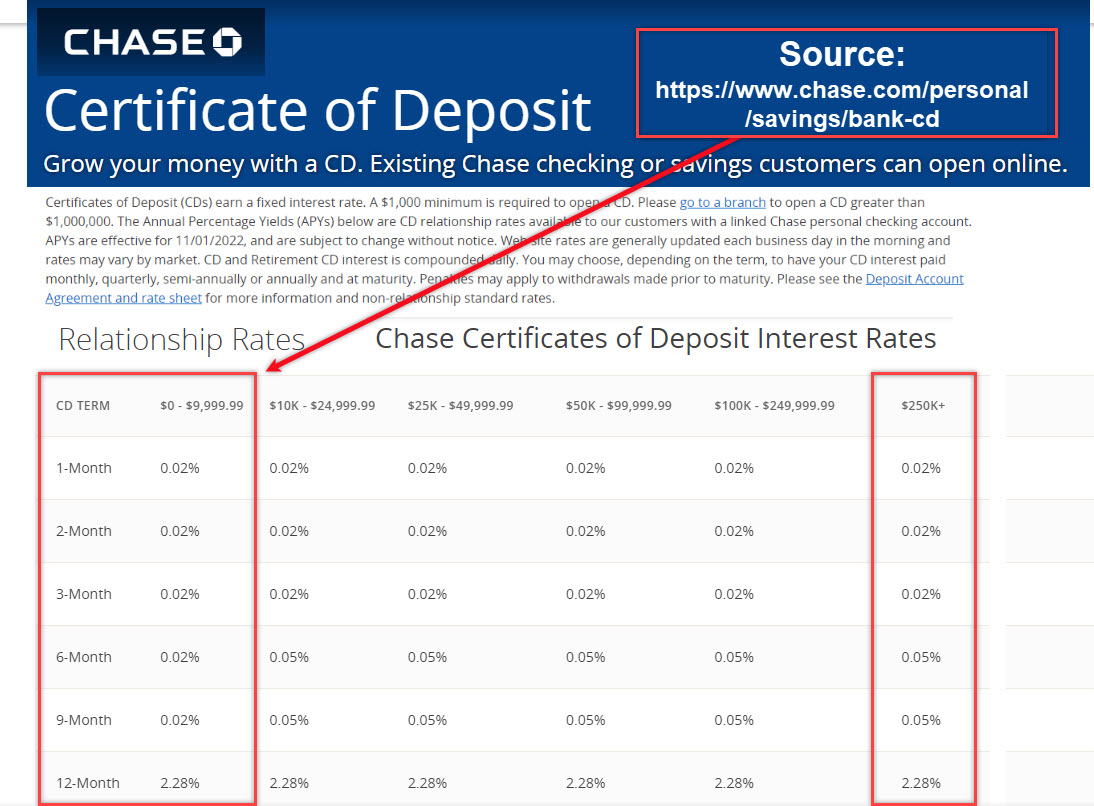
At U.S. Bank, you typically choose a term length — that's just a fancy way of saying how long your money stays put. Shorter terms might give you lower rates, while longer ones often pay more because you're committing for a longer stretch. It's a bit like ordering a subscription: if you commit to the yearly plan, you save more.
 Cash Invested and Available for Use – Know Your Flocks & Herds
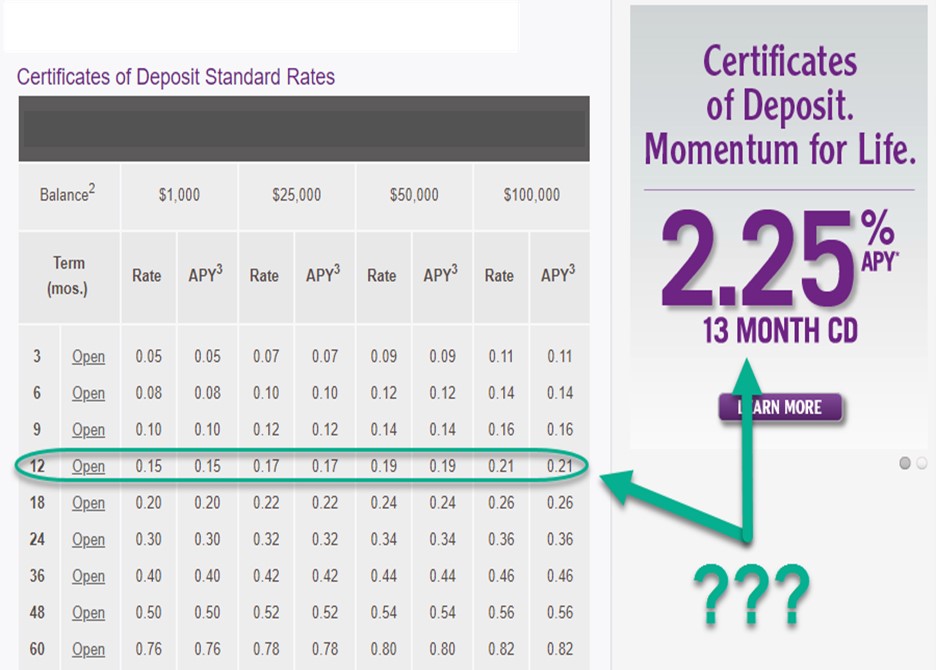
The rates themselves vary depending on how long you lock in your money. Whether it's a 3-month CD or a 5-year CD, U.S. Bank posts current rates that help you pick what fits your life. Rates can change, so it's always a good idea to check their website or drop into a branch.
One secret weapon here is the APY — Annual Percentage Yield. That's the number to watch, because it shows you the real, total return you'll earn over a year. Bigger APY means your money is making more friends behind your back.
Who Are These CDs Good For?
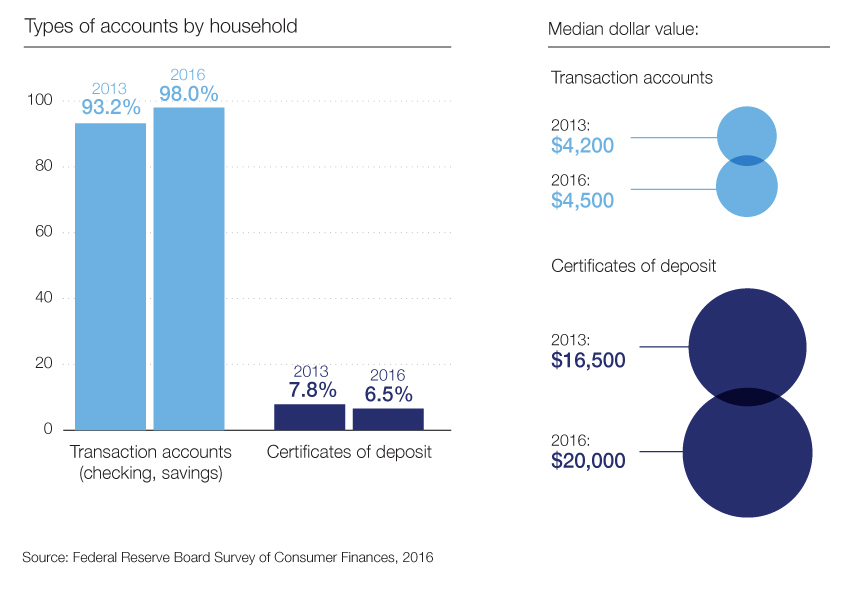
If you've got money you won't need for a while, a U.S. Bank CD can be a really chill way to watch it grow. Parents saving for college, folks eyeing retirement, or anyone just trying to beat inflation — this could be your groove. Even people saving up for a wedding could tuck away some funds safely.
 Managing Time Deposits - How To Use “Specials” And Odd-Month CDs
It's particularly great for anyone who struggles to keep their hands out of the savings jar. Let's be real: an easy-to-spend savings account and impulse purchases are like milk and cookies. A CD adds a little gentle pressure that actually helps your future self out.
A Little Word of Caution
Here's the deal — early withdrawal usually means a penalty fee, so make sure you won't need that cash before the term is up. Think of it as the bank asking, "Are you sure you're not going to need this?" before letting you off the hook. It's fair, and it keeps everyone honest.
The good news? Your money is FDIC insured up to standard limits, so it's completely protected. That means even if something wild happens, your balance is safe and sound. For anyone who likes sleeping peacefully at night, that's a winning perk.
 1 Year Certificate Of Deposit Rates – ZFBE
So, Should You Open One?
If the answer to "Can I leave this money alone?" is yes, then a U.S. Bank CD might be a fantastic fit for you. It's a simple, no-drama way to earn a little extra while your money rests comfortably. No complicated apps, no streaks to maintain — just solid, old-fashioned savings.
Life is busy enough without money being another source of stress. A CD quietly does its thing in the background while you focus on living. Sometimes the smartest financial move is also the most laid-back one.
So go ahead, take a look at what U.S. Bank is offering right now. Your future self will probably thank you — probably while sipping something cold, watching YouTube, and totally not worrying about where their money went.