Picture this: you just made your last monthly home loan payment. The house is truly yours, no strings attached. What a feeling, right? But wait — did you pay it off early? Well, now we need to talk about something called the prepayment penalty.
Before you panic, take a deep breath. A prepayment penalty is essentially a fee your lender charges you for paying off your mortgage ahead of schedule. Think of it as the lender saying, "Hey, you're leaving the party early!"
So, What Exactly Is It?
A prepayment penalty is a clause buried somewhere in your mortgage contract. It kicks in when you pay off your loan faster than the agreed-upon timeline. Not every lender includes it, so cheer up — you might not even have one!
Must Read
The penalty usually ranges from 2% to 4% of your remaining loan balance. Can you imagine paying thousands of dollars extra just for doing a good thing? And yes, people find that a little envious of those penalty-free borrowers.
Why Do Lenders Even Bother?
Lenders make money on interest over time. When you pay off early, they lose out on those juicy long-term interest payments. It's basically a business decision, not a personal grudge against you.
 Penalty for paying off your Loan Early? - YouTube
Here's the fun part: most modern lenders have moved away from prepayment penalties altogether. Thanks to internal policies and regulations, the prepayment penalty has become much less common than it used to be. So you might be worrying about something that isn't even on the table.
How Do You Avoid It?
First, read your loan agreement before you sign anything. Look for the prepayment clause — it's usually hiding in the fine print. Treat it like a treasure hunt, except the treasure is keeping your money.
Second, ask your lender directly: "Is there a penalty for paying off early?" A straightforward question deserves a straightforward answer. You'd be surprised how many people never think to ask this simple thing.
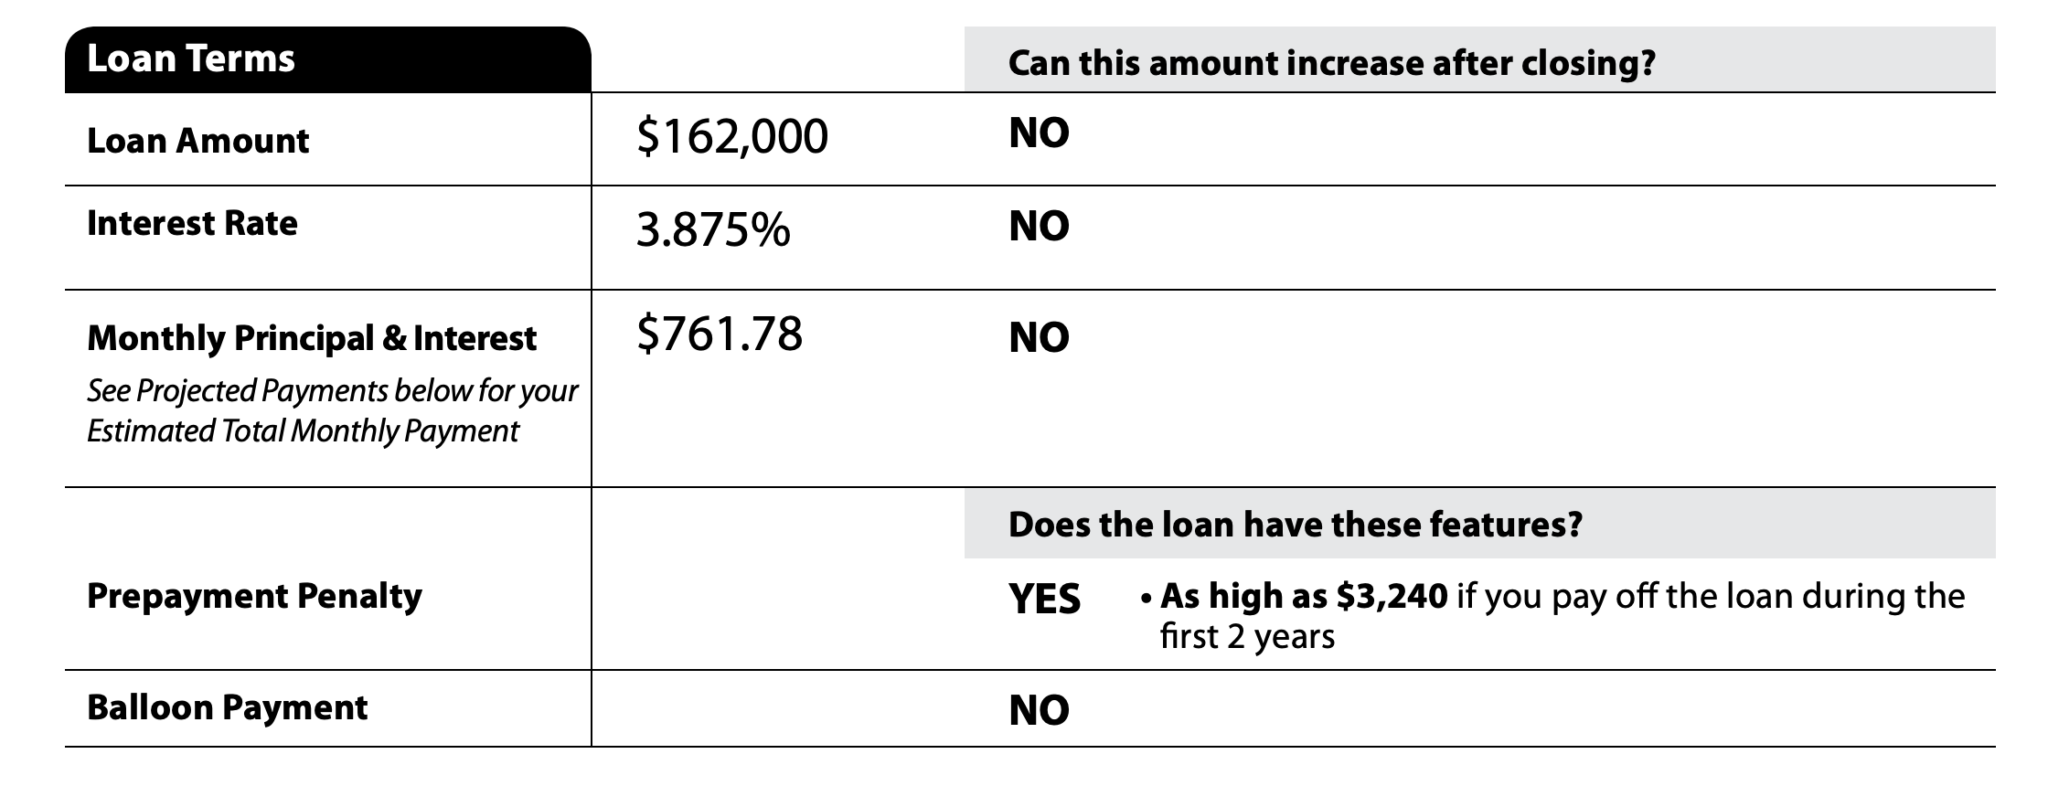 Calculating A Prepayment Penalty On Mortgage Step By Step – EOCRFT
Third, consider negotiating. If the penalty exists, you can sometimes work out terms that soften the blow. Wouldn't it be fun to become the savvy negotiator of your own finances?
Should You Still Pay It Off Early?
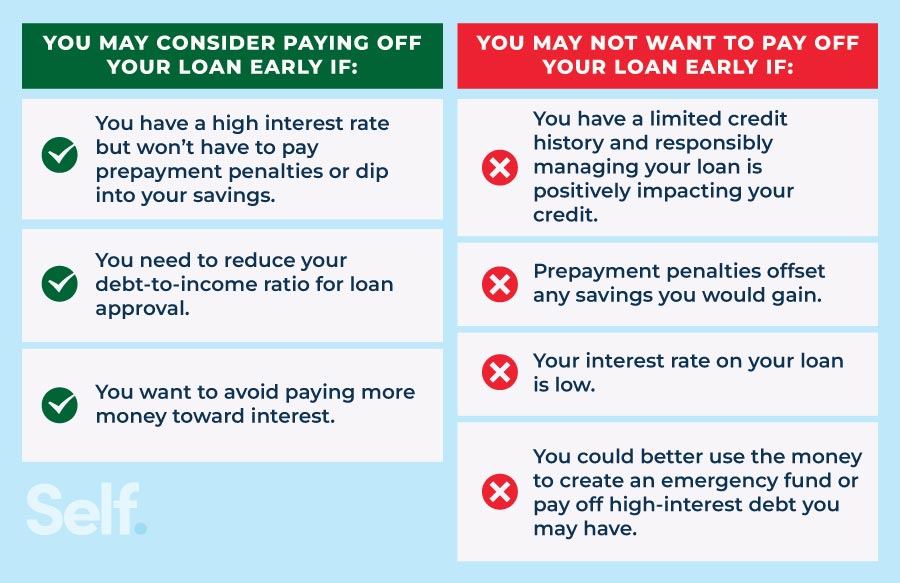
That's entirely your call. Paying off early can save you thousands in interest over the life of the loan. Imagine all the vacation funds you'd free up — or the impromptu kitchen renovation you could finally tackle.
 What Is a Prepayment Penalty on a Loan: Avoid Extra Costs
On the flip side, keeping your mortgage can sometimes be smarter if you have other high-interest debt or investment opportunities to chase. Debt isn't always the enemy when managed strategically.
Make It a Celebration, Not a Headache
At the end of the day, knowing about prepayment penalties puts you in the driver's seat. It removes the mystery and lets you make decisions with confidence and a smile. Knowledge like this can genuinely make managing money feel more like a game and less like a chore.
The house may be just bricks and mortar on paper, but it's the dream you're investing in with every payment. Weigh the numbers, know your rights, and choose the path that makes you happiest. Life's too short to stress over fine print — go learn it, own it, and enjoy the ride!