Klarna has become one of the most popular payment options for people who want flexibility when shopping online. From fashion to electronics, millions of users rely on it daily to split costs. But one question keeps coming up: is it actually bad to extend your due date?
The short answer is not always. Sometimes life throws curveballs — unexpected bills, a lower paycheck, or an emergency — and pushing your due date can be a smart move instead of defaulting entirely. Missing payments altogether leads to credit score damage and potential fees, so a planned extension often saves you from worse outcomes.
Take Mia, a college student who bought textbooks through Klarna. When her part-time job cut her hours, she extended her due date twice. It wasn't ideal, but it kept her account in good standing. Meanwhile, her friend who ignored the deadline ended up with late fees and a hit to their credit.
Must Read
However, extending too often can create a cycle of debt. If you find yourself constantly pushing dates, it might signal that you're borrowing beyond your means. Klarna may also restrict your spending limit or flag your account over time, which nobody wants.
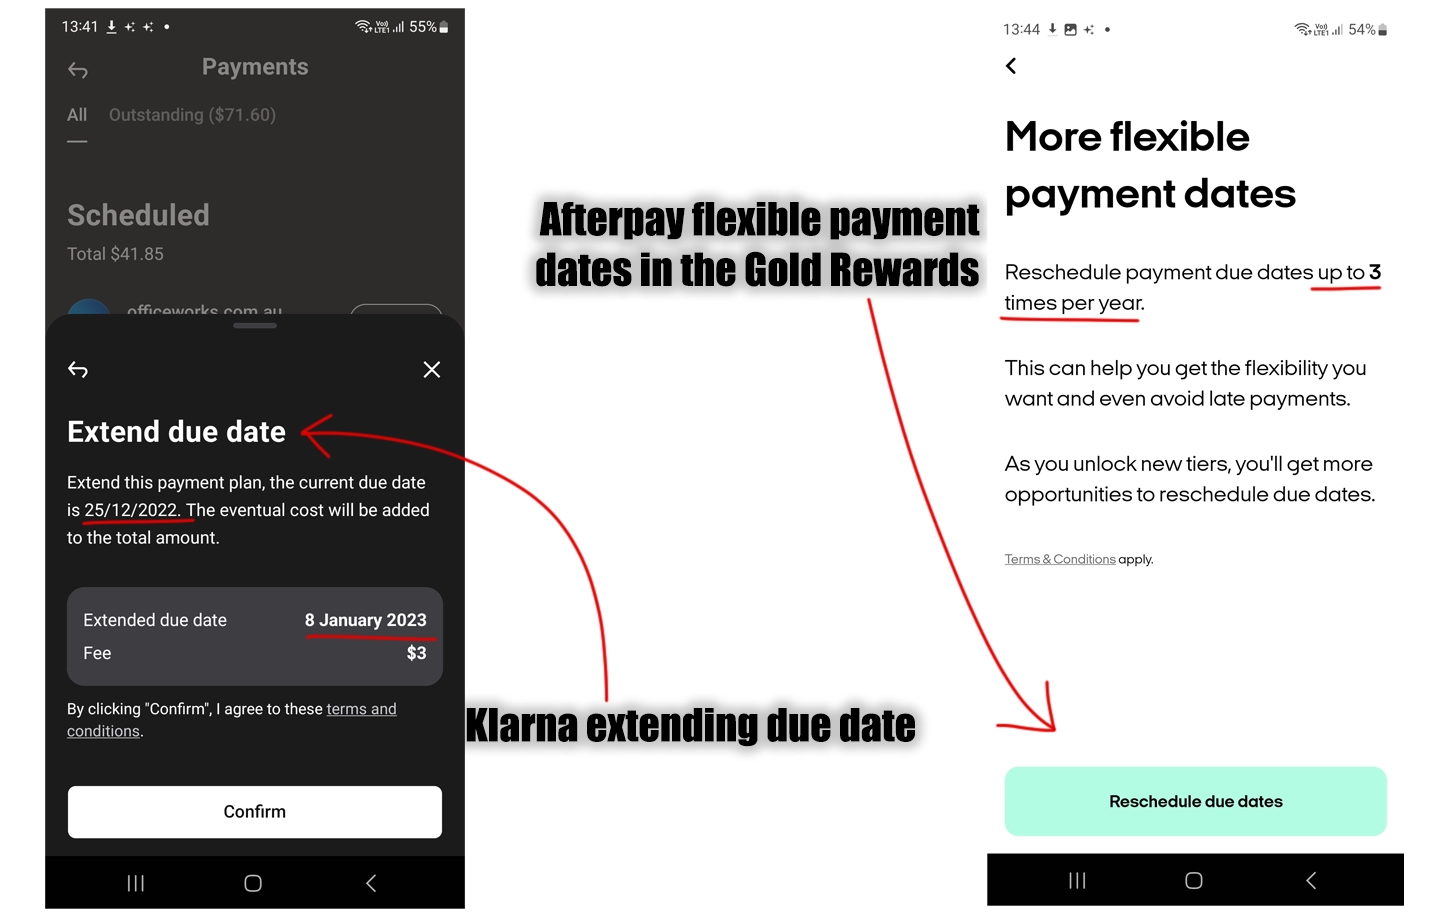 Klarna vs. Afterpay (2023) - Which One is for You?
Try this: only extend when genuinely necessary, track your due dates in a simple reminder app, and set a personal limit — maybe no more than one or two extensions per cycle. This keeps you accountable while preserving the safety net Klarna offers.
Ultimately, extending a due date isn't inherently bad. Used wisely, it's a practical tool that helps individuals manage money stress without derailing their finances completely. The key is balance and knowing when it's a bridge versus a habit.