Ever dreamed of buying a house without saving up a tiny fortune first? Yeah, you're not alone. Zero down mortgages sound like a myth, but they're absolutely real.
Imagine walking into a home you love and having the bank say, "Don't worry, you don't need a down payment." Sounds crazy, right? But that's exactly what some loan programs offer.
You don't have to be rich or a housing market wizard to pull this off. It's more about knowing which doors to knock on. So let's break it all down in the simplest way possible.
Must Read
What Exactly Is a Zero Down Mortgage?
A zero down mortgage is basically a home loan where you don't put any money upfront. Think of it like renting a movie without paying for it — the bank covers the cost, and you pay it back over time. Of course, it's not completely free money.
You'll still have monthly payments, interest, and closing costs to think about. The "zero" only applies to the down payment itself. That's still a huge deal for anyone busting their savings account.
Who Typically Qualifies?
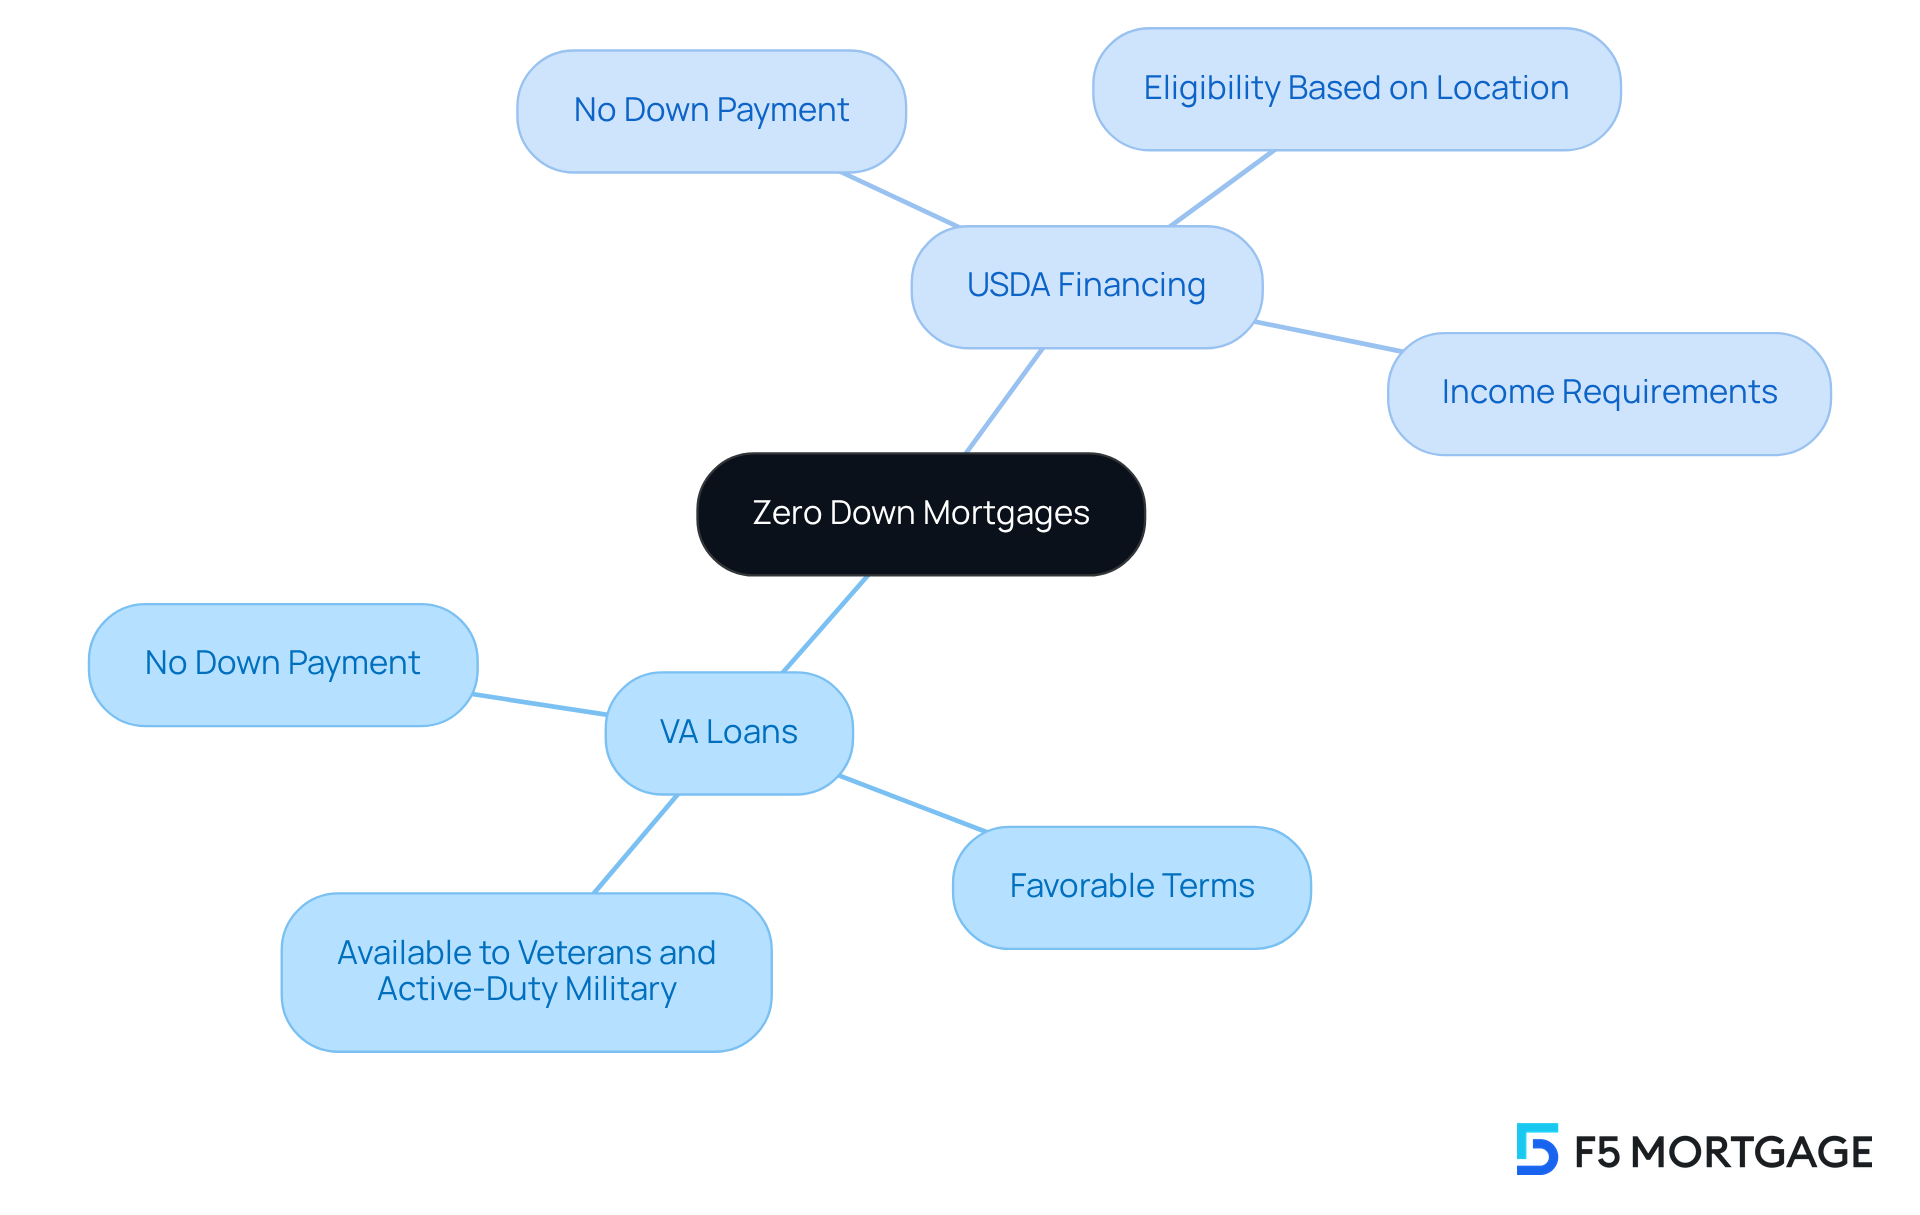
Most zero down programs target a few specific groups. Veterans and active military members have it especially good thanks to VA loans. Eligible buyers in certain rural areas can snag USDA loans too.
 What if I told you there are mortgages that allow for zero or even as
Your credit score matters a lot here. Most lenders want to see a score in the mid-600s or higher, though some VA packages are more flexible. Without solid credit, getting approved gets way tougher.
You'll also need a decent debt-to-income ratio, usually under 43%. That means your existing debt shouldn't eat up too much of your income. Basically, lenders want to know you can actually handle the payments.
Why Do These Programs Even Exist?
Here's where it gets interesting — these programs aren't charity. They're designed to boost homeownership in underserved communities. Think of them as a carrot on a stick to stimulate certain housing markets.
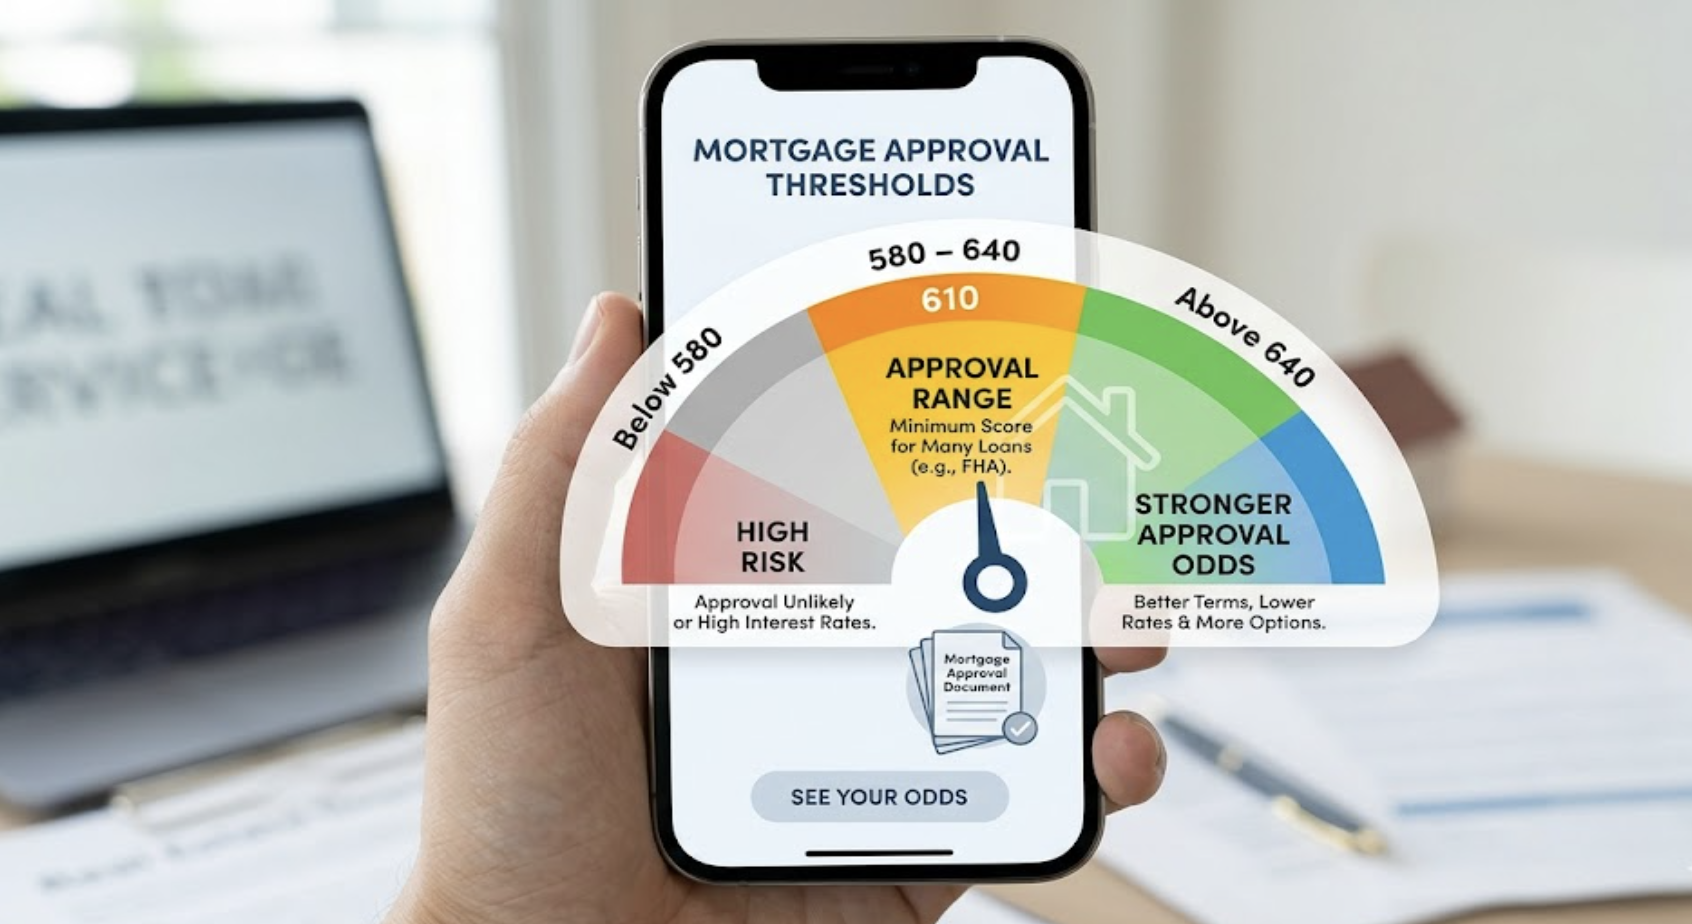 Zero Downpayment Mortgage Credit Score Requirements | ASAP Credit
VA loans reward people who served their country. USDA loans help revitalize rural towns that big builders usually ignore. Everyone gets a little something out of the deal.
Tricks to Boost Your Odds
Start by checking your credit report for errors. A single wrong number can knock off a score you don't even know about. Fix those mistakes before applying — it's free and surprisingly effective.
Keep your credit utilization under 30%. Avoid taking on new debt right before applying because lenders notice that stuff. Consistency is your best friend here.
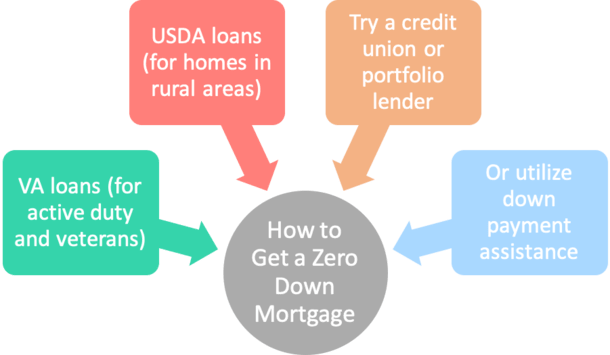 Mortgages with No Money Down: What Are the Options in 2024?
Also, gather your tax returns, pay stubs, and bank statements early. Having paperwork ready shows lenders you're serious and organized. Nobody likes a slow applicant, trust me.
Is It Actually Worth It?
Zero down sounds dreamy, but there's a flip side. You'll likely pay private mortgage insurance or slightly higher interest initially. But for folks without savings, it can be a total game-changer.
Consider this — waiting years to save a down payment versus getting the keys right now. Which one gives you more time to build equity? Sometimes starting dirty beats not starting at all.
So, is a zero down mortgage perfect? Nope. But it's one of the coolest options for first-time buyers who don't have a pile of cash sitting around. Check your eligibility, check your credit, and start exploring — you might be closer to owning than you think.