You know that moment when a check shows up at your door, but it's got someone else's name on it? Yeah, it happens more often than you'd think. Let's dive into this little puzzle together and figure out what you can actually do about it.
Wait, Is That Even Allowed?
First things first – depositing a check with someone else's name on it isn't exactly a casual, walk-in-the-park situation. Banks have rules for a reason, and they're not trying to ruin your day. Think of it like showing up to a party without being on the guest list – things get a little tricky.
So why would this even happen? Maybe a company mailed a check to your old address, or perhaps a friend sent funds to the wrong person. Life is weird like that, right?
Must Read
The Golden Rule: Endorsement
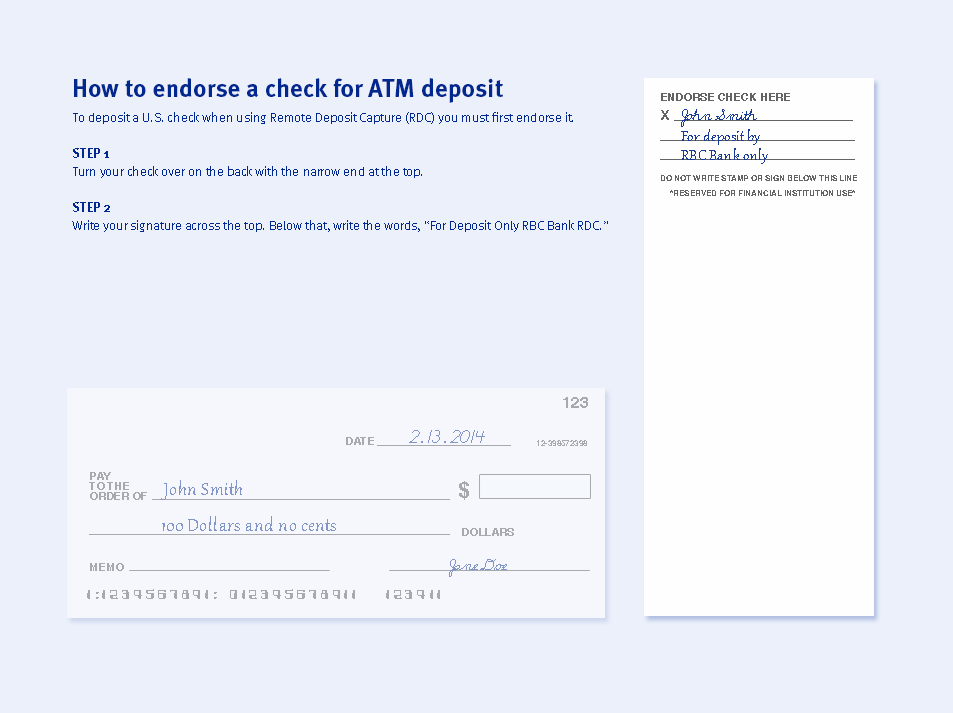
The most common way to handle this is through endorsement. The person whose name is on the check signs the back, essentially saying "hey, I'm cool with this." After that, you do the same thing and add your signature as well.
This is called multiline endorsement, and it's like a chain of trust. The original payee vouches for you, and the bank sees two names – problem solved. Cool, right?
What If You Can't Reach the Person?
Here's where it gets a little stickier. If you cannot physically contact the person named on the check, banks will usually give you the side-eye. You wouldn't lend your house keys to a stranger, would you? The bank feels the same way about missing signatures.
 Restrictive Check Endorsement Example
In that case, you may need to ask the original payee to contact the sender directly. Sometimes the issuer can simply stop payment and reissue the check in your name. It's frustrating, but patience really is the name of the game here.
Some Banks Are More Flexible
Guess what? Not every bank treats this situation the same way. Some will let you deposit with just a note or a small written explanation attached to the check. Others might ask for ID and extra paperwork to confirm you're legit.
Calling your bank beforehand can save you a ton of headaches. Why wait in line just to be told "no" when you could plan ahead instead?
 Making a deposit » RBC Bank
Power of Attorney: The Big Weapon
If this is a regular thing for you, consider getting a power of attorney document. This legally lets you act on behalf of another person – kind of like being their financial superhero. It's not a joke; banks actually take this seriously once the paperwork is proper.
Of course, only hop into this if you have a genuine, ongoing relationship with the person. Banks can smell something fishy from a mile away, so honesty always wins the race.
Quick Tips Before You Walk Into the Bank
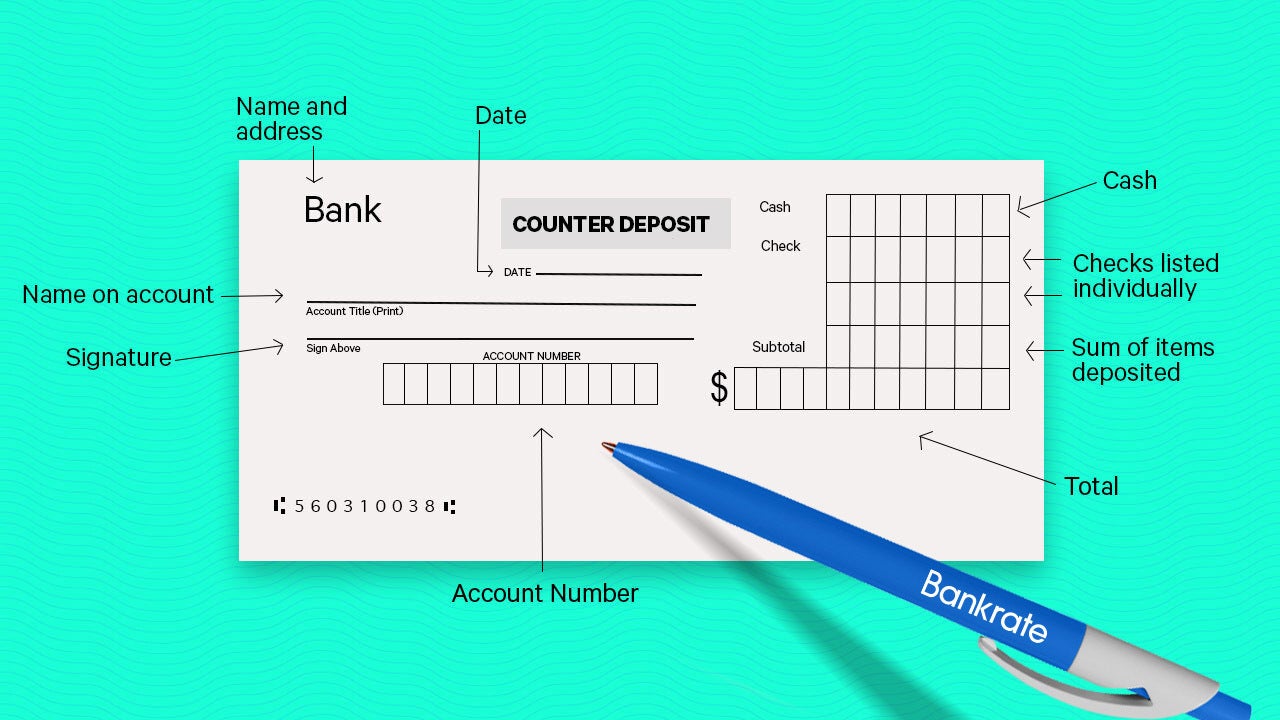
Here's your mini cheat sheet: check the name carefully, contact the payee, and call your bank before visiting. These three steps can turn a frustrating errand into a smooth five-minute trip.
 How To Deposit A Check | Bankrate
Also, make sure you have valid identification and any supporting documents ready. Nobody likes digging through backpacks while the teller waits behind the counter.
Final Thoughts
Depositing a check that isn't technically yours can feel like cracking a small code, doesn't it? It's one of those everyday challenges that teaches us how money systems really work behind the scenes. So next time this pops up, you'll already know the playbook – no stress, no confusion.
Just remember: communication, proper endorsement, and a little bank research are your best friends. And honestly? It's pretty satisfying when you figure it out on your own.