
Ever looked at your mortgage and thought, "I wonder if I can switch this up again?" Spoiler alert — you totally can. Refinancing a home loan isn't a one-time affair. It's more like a revolving door!
Let's talk about this wild world of refinancing. It's surprisingly more flexible than you'd ever imagine. And honestly? It's kind of addictive once you get the hang of it.
So, How Often IS Anyway?
Short answer: as often as you want. Yep, there is no legal limit on how many times you can refinance your home loan in most places. The mortgage gods are generous that way.
Must Read
One month? You can refinance. One day later? Go ahead. It's like a buffet — grab as many helpings as you like. Nobody's cutting you off from the mashed potatoes here.
But hold on — just because you can doesn't always mean you should. Refinancing too often can trigger costs. And those costs add up faster than you'd think.
Wait, There's a Catch? There's ALWAYS a Catch.
Most lenders have a seasoning requirement. This means they want you to hold your current loan for a certain period — usually six months to a year. It's their polite way of saying, "Give it a minute, buddy."
 Does Refinancing Reset Your Loan? The Truth Most Homeowners Miss
Also, there's something called recoupment time. This is how long it takes for your interest savings to cover all the fees you just paid. If that takes forever, you're basically just moving money around for fun.
And here's a quirky little twist: some lenders actually charge you a prepayment penalty if you refinance too soon. Imagine being fined for switching. It's like getting a ticket for changing lanes!
The Golden Refinance Rule
The sweet spot? Refinance when your new rate is at least 0.5% to 1% lower than your current one. That's the number most experts toss around. Anything less and it just isn't worth the hassle.
 How Often Can You Refinance Your Home? — RISMedia
There's also the "break-even point" — the moment when your savings from the new rate finally pay off all those closing costs. Most people hit it between 12 and 24 months. Give yourself time here.
Refinance FOMO Is Real
Seriously, people get refinance anxiety. They hear the neighbors are saving $200 a month and suddenly they're panic-refinancing. Chill! The rates aren't going anywhere.
It's fun to talk about because it feels like you're playing a financial game. Lower rate = win. But rushing in without thinking? That's a classic blunder.
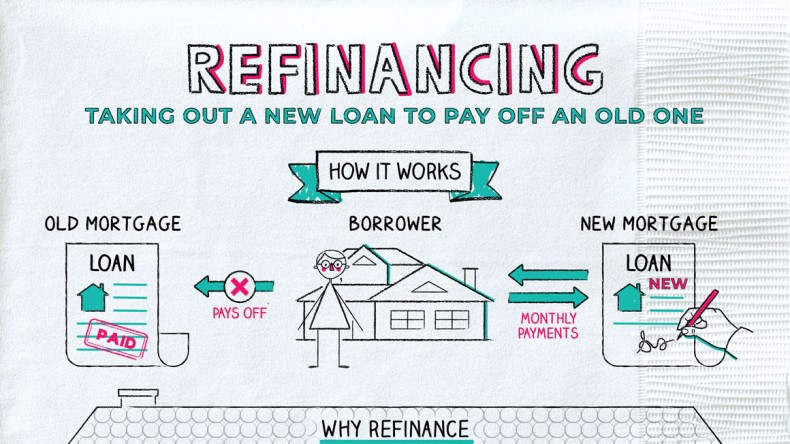 Loan Refinance, Refinancing a Mortgage, When Can I Refinance My House
Sometimes the smartest move is to do absolutely nothing. Boring, sure. But it keeps more cash in your pocket. And cash in pocket beats cool story every single time.
Make It Count!
Each refinance comes with closing costs. These can range from 2% to 5% of your loan. That's no pocket change, friend.
Think of refinancing like a second date with your mortgage. You're renegotiating the relationship. Make sure it's genuinely better before you pop the question again.
So go ahead — refinance when it makes sense. But don't treat it like a picky eater at a salad bar. Sometimes the original dish tastes just fine.