Buying a house? Oh boy. That's a big deal. Like, bigger than your entire college dorm room big.
People toss around the term "down payment" like it's an obvious thing. But honestly? Most folks have no clue what number to aim for. And guess what? There's no single right answer. It's kind of like asking, "How much hot sauce is too much?"
The Classic 20% Rule
For decades, everyone swore by putting down 20% of the home's price. That number came straight from old-school X99yency guidelines designed to protect lenders. It was basically the mortgage industry's favorite golden rule.
Must Read
Here's a fun twist — that 20% rule was never actually a law. It was just a smart suggestion. And yet, somehow, it became gospel in every coffee shop conversation about homeownership.
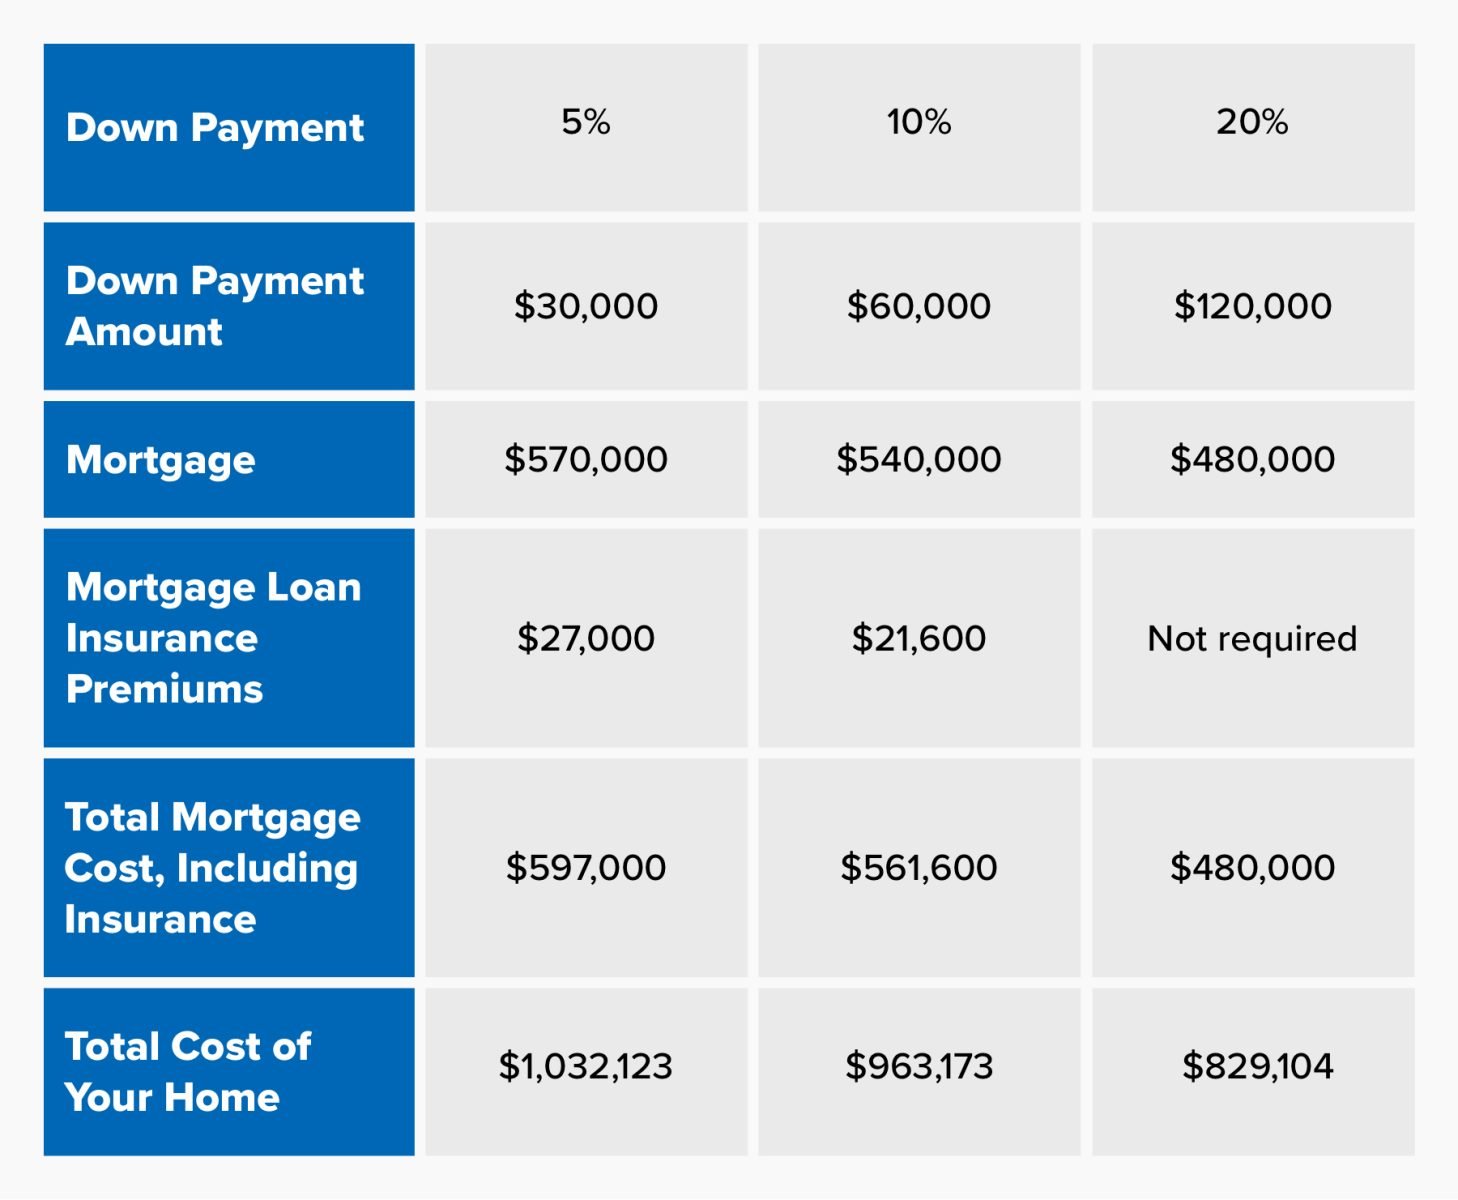
Why does 20% matter? Because it lets you skip private mortgage insurance (PMI). PMI is basically a fee you pay because the lender still sees you as a tiny bit risky. Nobody likes extra fees, right?
The Tiny Down Payment Crew
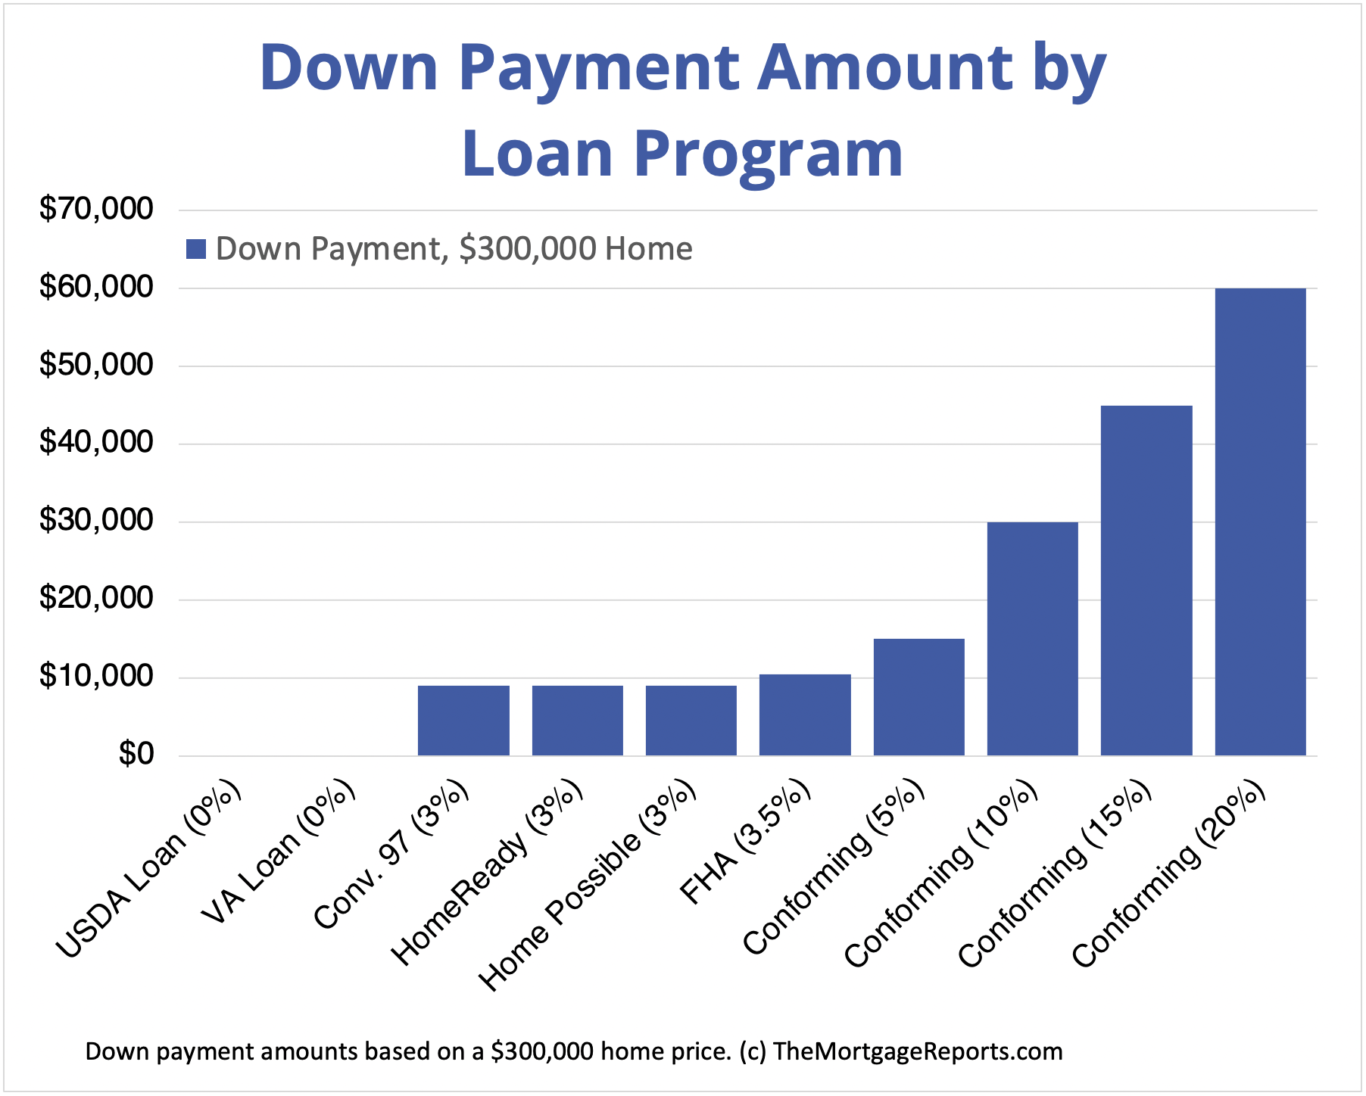
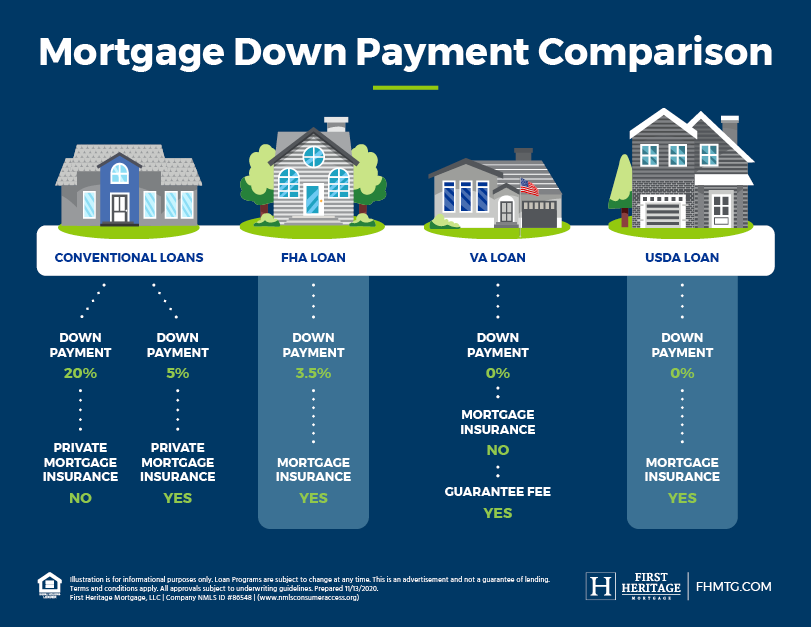
Plot twist: You don't need 20% to buy a house. Some loans let you put down as little as 3.5%. Yup, three and a half percent. That's practically pocket change compared to the full price.
 How Much is a Down Payment on a House? | GTA-Homes
FHA loans are the MVPs here. They were created to help everyday people become homeowners. How cool is that?
There are even zero-down options through USDA and VA loans. VA loans are for military folks, while USDA loans focus on rural areas. Free rides on the down payment? Yes, please.
Big Down, Small Down — What's the Vibe?
Putting down more cash means a smaller loan amount. That translates to lower monthly payments. Your wallet breathes a little easier every month.
But a huge down payment also means less cash in your emergency fund. Imagine scraping together every last dollar, then your car suddenly needs a $2,000 repair. Oof. That's a rough Tuesday.
 What Is A Good Down Payment On A $300K House?
On the flip side, a smaller down payment keeps more money in your pocket today. You stay flexible and prepared. Plus, you still get the keys to your brand-new house.
Quirky Down Payment Trivia
Want a weird fact? The average first-time buyer in the U.S. puts down about 6% to 7%. Not 20%. Not 3.5%. The real-world average sits somewhere smack in the middle.
Some buyers even receive down payment assistance from state programs or grants. It's like finding a discount code for one of the biggest purchases of your life. Who wouldn't want that?
And here's the cherry on top — certain lenders let you use gifted money from family. Grandma essentially becomes your down payment fairy godmother. You can't make this stuff up.
 How much home can you afford? | Houseful
So What Should YOU Put Down?
There's no universal answer. Each person's situation is wildly different. Your income, your savings, your climate debts — they all play a role.
Ask yourself some quick questions: How much can I comfortably spare? Will I sleep well at night? Do I still want money for tacos afterward? All crucial considerations.
The bottom line? Play with the numbers. Talk to a lender. Run some scenarios. Figure out that sweet spot where your down payment feels brave but not foolish.
Because buying a house should be exciting, not terrifying. So grab your calculator, grab your favorite snack, and crush those numbers. Your future front door is waiting.