
OK, picture this. You want to buy a house, but the bank says, "Nope!" Your credit? Bumpy. Your savings? Laughable. Suddenly, someone appears and says, "Hey, I'll just finance you myself." Welcome to owner finance in Texas! It's bite-sized, it's unconventional, and honestly? It's kind of wild.
Wait, What's Owner Finance?
Owner finance, sometimes called seller carryback, means the seller plays bank for you. Yep, that super generous homeowner just became your lender. No mortgage company, no nosy underwriter, no endless paperwork mountain. The seller carries the loan directly, and you pay them back over time instead of a big scary institution.
You sign a deed of trust, hand over a down payment, and start making installments. The seller keeps the title until you've paid them off entirely. Then? The property flips to you like a card trick. Boom.
Must Read
Why Does Texas Love This Stuff?
Texas is practically the owner finance capital of the universe. You know why? Because the laws around it are clear, cut, and super friendly. The Texas Property Code lays out exactly how owner financing must happen, and sellers here know the playbook by heart.
Rural land, empty lots, fixer-uppers — this deal thrives in all of them. Texas has acres upon acres of land, and not every buyer wants a fancy mortgage. Sometimes a handshake and a contract beat everything else.
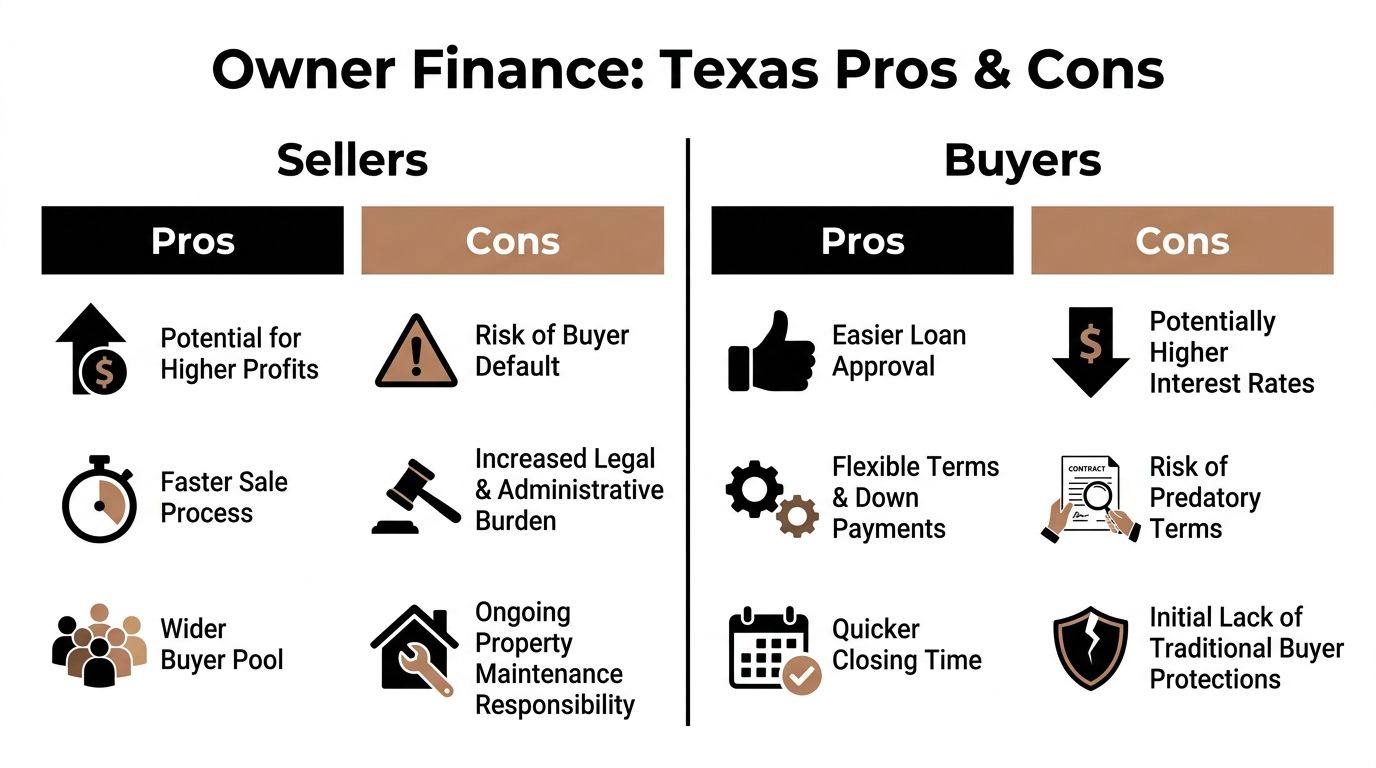 Owner Finance Texas Home: Your 2026 Comprehensive Guide
The Sweet Nuts of How It Works
First, you negotiate a price and interest rate directly with the seller. Think of it like shopping but with fewer price tags and more flexible math. Down payments usually range from 10% to 30%, depending on how brave everyone feels.
You agree on monthly payments, a loan term, and maybe even a balloon payment at the end. The seller records the deed of trust at the county clerk, which tells the world you've got rights to the property as long as you pay up. Simple, right?
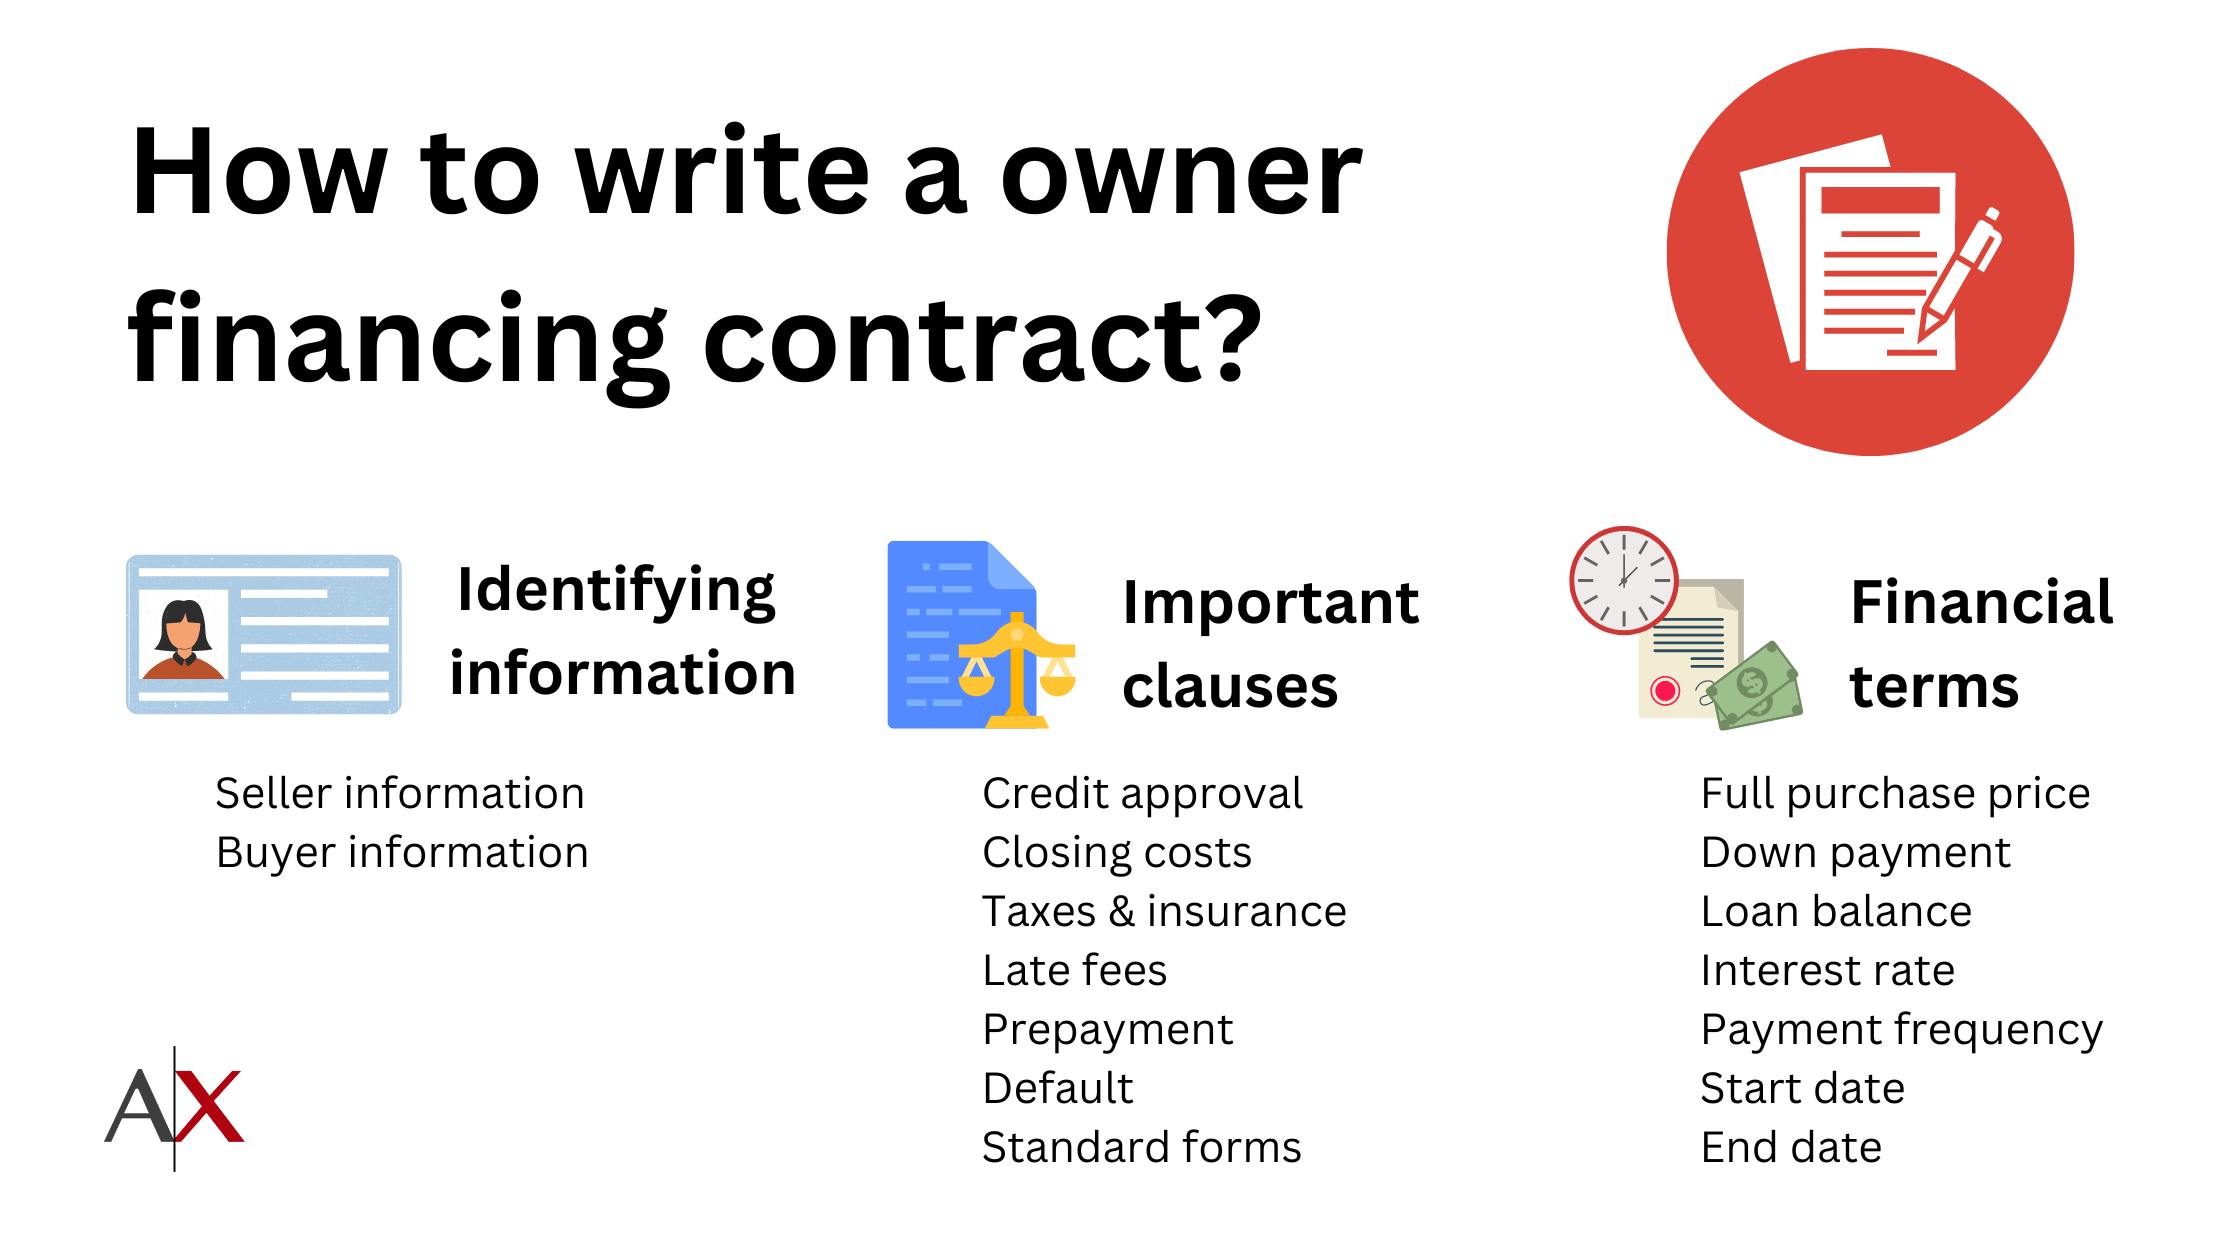 Owner Financing Contract Template | Free Forms [Updated 2025]
The Fun Quirks You Didn't Expect
Here's a quirky bonus: no closing costs rollercoaster! You skip lender fees, origination charges, and all that jazz. Your savings account gets to breathe a little.
Another fun fact? Since sellers often take on smaller loans, they attract buyers traditional banks would slam the door on. Credit score below 600? Owner finance doesn't flinch. It actually whispers, "Let's talk."
 How Does Owner Financing Work?
What About Risks? (The Not-So-Party Part)
Too good takes a turn? Sellers can put a balloon clause in your agreement — that's a big final payment due at the end. If you aren't ready, that balloon might pop spectacularly.
Also, some sellers press inflation onto the interest rate. Texas caps RSF at 10% in some cases, but always read the fine print. Better yet? Get a title company involved to keep everything honest and tracked.
The Takeaway (Punchline, Really)
Owner finance in Texas is like bargaining at a flea market but for a property. It's casual, it's creative, and it makes homeownership feel way less scary. So next time someone offers to be your bank — say yes but read the contract first. Then go move into your new place!