Ever wondered why a credit‑card company can thrive even when most of us barely think about how they make money? Understanding their business model is surprisingly fun and practical, because it reveals the hidden fees we all encounter. Knowing where the income comes from helps you see the bigger picture of personal finance.
This article’s main purpose is simple: to break down the three core ways a card issuer makes a profit, so you can spot them in your own statements and make smarter spending choices. By the end, you’ll recognize each revenue stream and learn how to work with them instead of against you.
The first and biggest earner is the interchange fee—a small percentage (usually 1–3 %) that a merchant’s bank charges the card‑issuing bank for each swipe. Whether you buy a coffee or a new phone, that fee flows straight into the issuer’s bottom line, making sales volume the most crucial metric for them.
Must Read
Second, the interest earned on balances that aren’t paid off in full is a steady cash‑flow source. Even a modest 0.3 % daily APR can add up, especially when combined with annual fees, late‑payment penalties, and cash‑advance charges—all designed to keep the issuer’s engine humming.
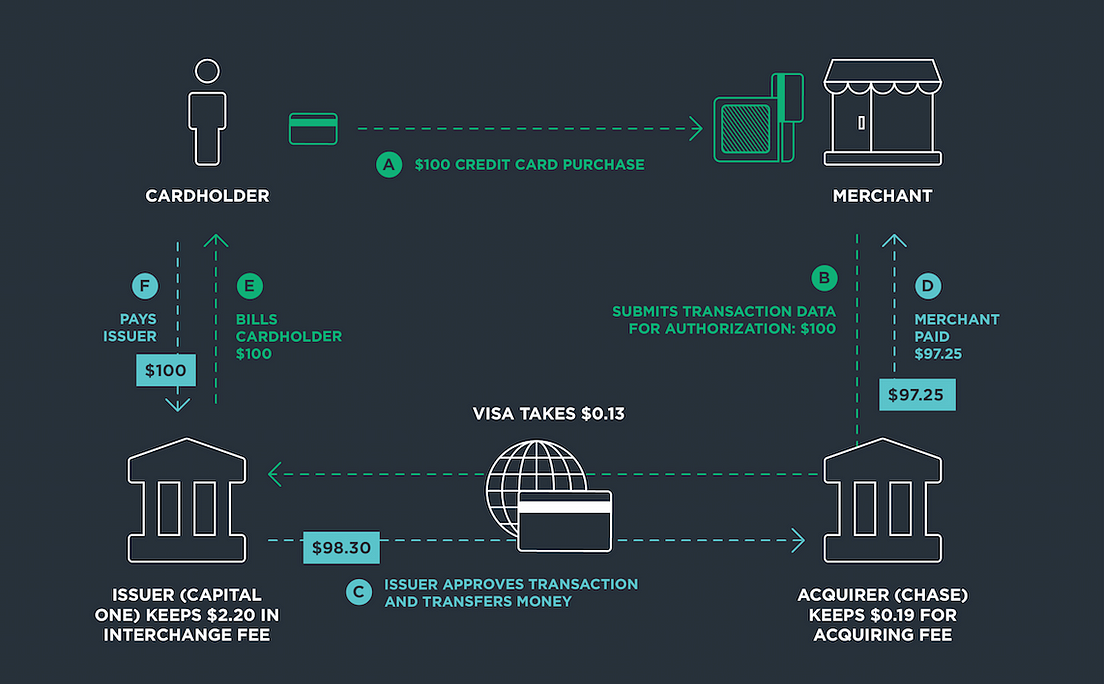 How do Credit Card companies make money — The Business Model | by
Finally, data plays a surprising role. Issuers can sell anonymized spending trends to advertisers or partner with retailers for exclusive rewards, turning your everyday purchases into marketing insights. These strategic deals add another layer of income beyond the obvious fees.
To make the most of this knowledge, start by checking your statement for any annual fees or late‑payment charges you can avoid. Next, choose a card with a low APR if you carry a balance, and look for rewards that match your spending habits. Finally, track your payment date to sidestep penalties, and you’ll keep money while enjoying credit perks.