Ever looked at your 401(k) balance and thought, “What if I could tap into that cash for a quick adventure?” Spoiler: you can, and it might be one of the smartest‑looking decisions you ever make. Just remember, this isn’t a free pass to raid the nest egg without a game plan.
Why a 401(k) Loan Can Feel Like a Mini‑Vacation
First off, a 401(k) loan lets you borrow against money that's already earning interest for you, which means you’re essentially using a loan from your own future self. No credit check, no sneaky fees—just a straightforward request that can be approved in a day or two. That kind of speed gives you the freedom to seize a last‑minute road trip or grab that dream guitar without waiting for payday.
Because the interest you pay goes back into your own retirement pot, you’re essentially loaning money to yourself rather than handing it over to a bank. That means the loan can actually feel like a tiny contribution to your future, even while you’re using the cash today. And because you’re repaying on a set schedule, the habit of paying yourself forward becomes a daily reminder that good things come from disciplined planning.
Must Read
How to Pull It Off
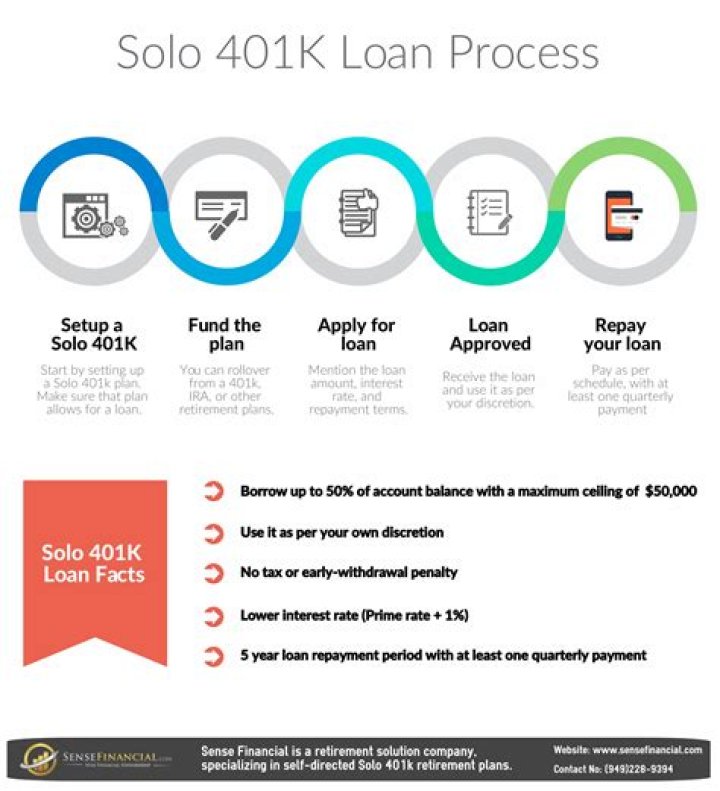
Check with your plan administrator first—most 401(k) plans have clear guidelines about loan amounts, repayment periods, and interest rates. Typically you can borrow up to the lesser of $50,000 or 50% of your vested balance, though the exact limit depends on your employer. Fill out a simple form, choose a repayment schedule that fits your budget, and watch the cash flow straight into your checking account—no hidden drama, just peace of mind.
 401 K Hardship Withdrawal
The Fun Factor
Imagine the grin on your face when you finally take that vacation to the coast with money you already own instead of asking friends to chip in. Or picture the thrill of finally buying that sleek road‑bike you’ve been eyeing, riding it right after the loan hits your account. Both experiences become more exhilarating when you know you’re using your own retirement savings responsibly, not a risky credit card.
Potential Pitfalls (But Keep Smiling)
Before you dive head‑first, remember that missed payments can turn your loan into a taxable distribution, which can lead to extra taxes and penalties. So set up automatic transfers from your paycheck—your future self will thank you for staying on track. And if you ever feel unsure, a quick chat with a financial advisor can clear the fog and keep the fun rolling.
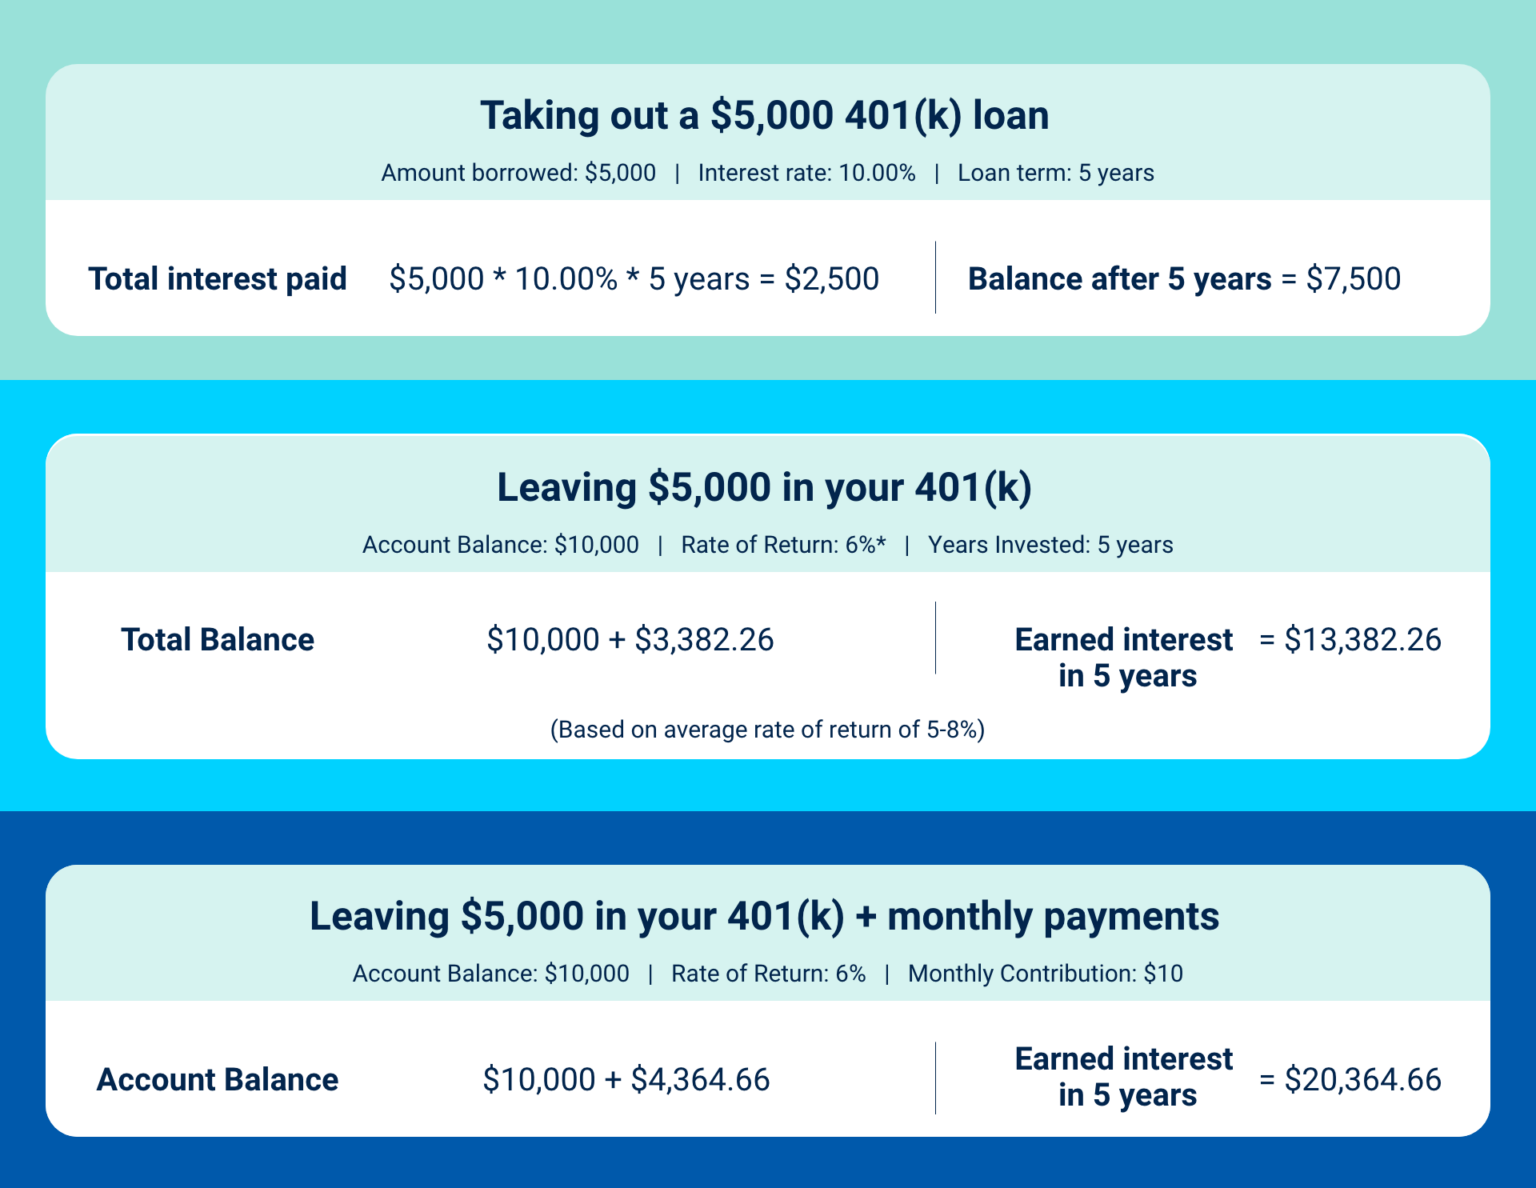 Should You Use a 401(k) Loan to Pay Off Debt? | Credello
Make It Part of Your Financial Playbook
Think of a 401(k) loan as a tool in your toolbox, not a shortcut you’ll regret later. Use it for a home repair that boosts property value, a tuition payment that opens new doors, or even a celebration that reminds life is meant to be enjoyed. Each smart decision you make reinforces the idea that money can be both practical and playful.
So the next time you glance at your 401(k) grin, ask yourself: could this be the ticket to a brighter, more adventurous tomorrow? With the right plan, you can turn dormant dollars into living‑loving memories, and the excitement will ripple through every corner of your life. Stay curious, explore extra resources, and see how one loan can ignite endless adventurous confidence for you.