So, you've dipped your toes into the wild world of cryptocurrency. Maybe you bought some Bitcoin back when it was cheap (lucky you!), or you've been trading Ethereum for fun. Either way, here comes the unavoidable question everyone dreads: do you have to claim this on your taxes?
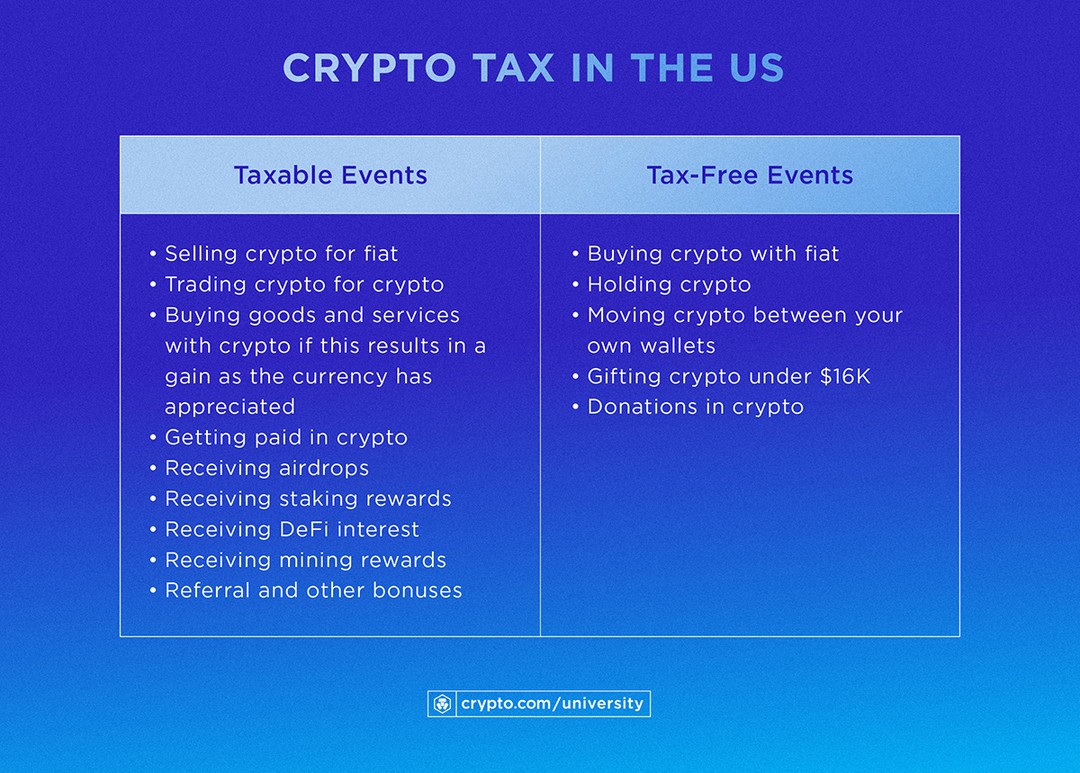
Short answer? Yes. Long answer? Also yes, but with a little more nuance. In most countries, including the U.S., the IRS treats crypto as property—not currency—meaning every transaction where you profit counts as a taxable event. That includes selling, trading, or even spending it on a fancy coffee. Yep, that $6 latte just got complicated.
Now, don't panic just yet. You only owe taxes if you actually made a gain. If your crypto tanked, congratulations—no tax owed on losses (though you might be able to deduct them, silver lining ever). The tricky part is keeping track of everything: buy prices, sell prices, all those little trades at 2 a.m. when you couldn't sleep.
Must Read
Pro tip? Use a crypto tax tool or spreadsheet to log your transactions. Your future self—and your accountant—will thank you. Also, keep records of everything. The IRS loves a paper trail almost as much as crypto enthusiasts love the number three.
 Crypto Tax Guide for US Investors in 2026
Here's the thing though: taxes on crypto aren't there to ruin your fun. They're just the price of doing business in a world that's going digital. Think of it as the cover charge for the party—without it, nobody gets in.
So take a deep breath, grab a snack, and tackle those numbers with a smile. You've already survived market crashes and wallet scares—taxes are no match for you. Now go live your best, fully accounted-for life. You've got this!