So, you're house-hunting, and someone drops the phrase FHA loan into the conversation. Naturally, you wonder: do these babies come with lower interest rates? Great question — and spoiler alert, the answer is a little more nuanced than you'd expect.
Here's the deal: FHA loans are backed by the Federal Housing Administration, which basically gives lenders a safety net. Because of that government partnership, lenders are more chill about handing out loans to folks with lower credit scores or smaller down payments. And yes, that often translates into rates that are competitive with or even lower than conventional loans, especially if your credit score isn't exactly living its best life.
Think of it like this — a conventional loan might be like dating someone with a perfect résumé. An FHA loan is more like dating someone who might not have every checkbox ticked but has a trustworthy co-signer (hello, Uncle Sam!). Lenders feel comfortable, so they offer decent terms.
Must Read
Now, before you start celebrating, keep in mind that FHA loans come with mandatory mortgage insurance premiums — sometimes for the life of the loan. That insurance can bump up your monthly payment, offsetting some of those lower rates. So the real question isn't just about the interest rate — it's about the total cost.
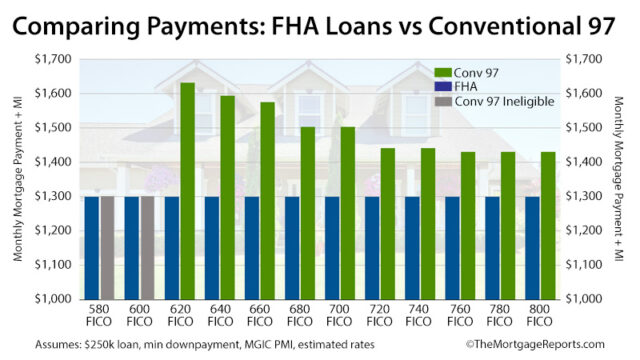 Conventional Loan vs FHA Loan | 2025 Rates and Guidelines
Bottom line? FHA loans can absolutely offer lower interest rates, particularly for first-time buyers or those with less-than-stellar credit. Just crunch the numbers on everything — the rate, the insurance, the fees — before making your move.
Because at the end of the day, finding the right loan is like finding the right pair of shoes: it's all about what fits you perfectly. And hey — there's a home out there with your name on it, and it's waiting with open arms. Go get it! 🏡

