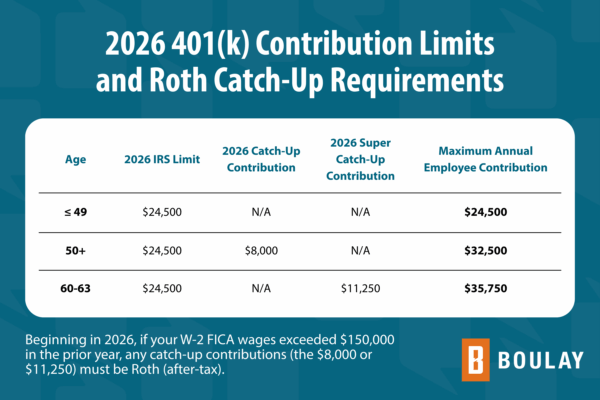
Okay, here's a question that sounds totally bonkers at first: Can you actually throw money into both a traditional 401(k) AND a Roth 401(k) at the same time? Spoiler alert: Yes, you absolutely can! And honestly? It's one of the coolest money moves hiding right under your nose.
Most people read that and go, "Wait... really?" And yeah. Really. Your 401(k) plan might be holding a hidden superpower you never even noticed.
Wait, What's the Difference Again?
A traditional 401(k) lets you invest money before taxes. Think of it as hitting "skip" on your taxable income right now. You pay taxes later when you withdraw.
Must Read
A Roth 401(k) flips the script. You pay taxes now, but your money grows completely tax-free forever. Future you gets to keep every single penny.
They're like two flavors of ice cream. Both delicious. Both filling. Just completely different vibes.
So Can You Mix and Match?
Absolutely. Delightfully. Gloriously.
Here's the fun part: the IRS sets one combined contribution limit for your 401(k). Right now, that's $23,000 if you're under 50. You can split that limit however you want between traditional and Roth.
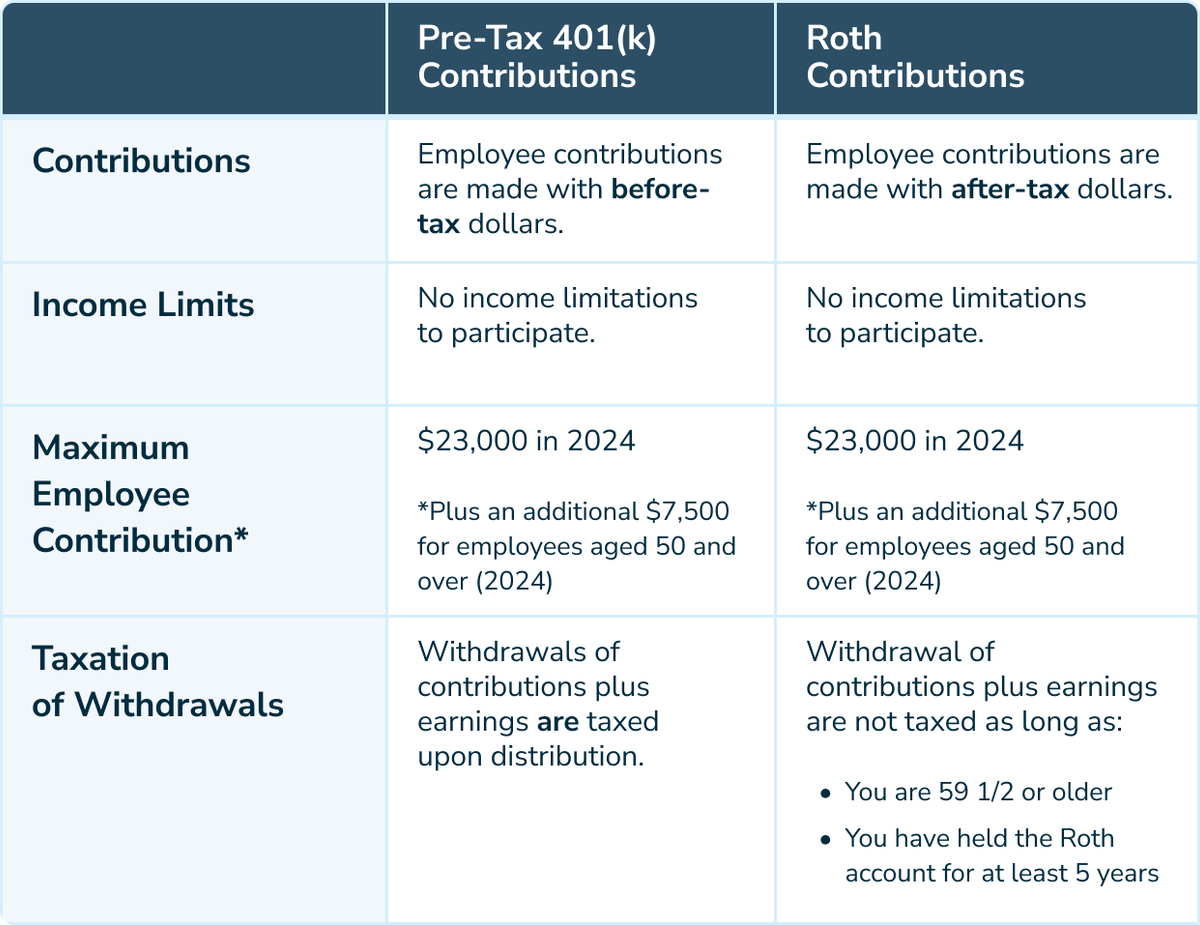 What’s the Difference Between Pre-Tax and Roth 401(k) Contributions
Pour $10,000 into traditional and $13,000 into Roth? Done. Go $5,000 and $5,000? That works too. You're basically building a custom money cocktail, and the bartender is the IRS.
Why Would Anyone Want Both?
Genuine question. Why smear peanut butter on air?
Here's a weirdly fun truth: nobody knows what tax rates will look like in 30 years. Space jellyfish? Economic collapse? Flying cars? Your tax bill could be sky-high or on the floor.
By splitting contributions, you're hedging your bets like a genius. You get some money tax-deferred now and some completely tax-free later. It's a backslash of financial insurance, and it's clever af.
Besides, diversification isn't just for stocks. It's for taxes too.
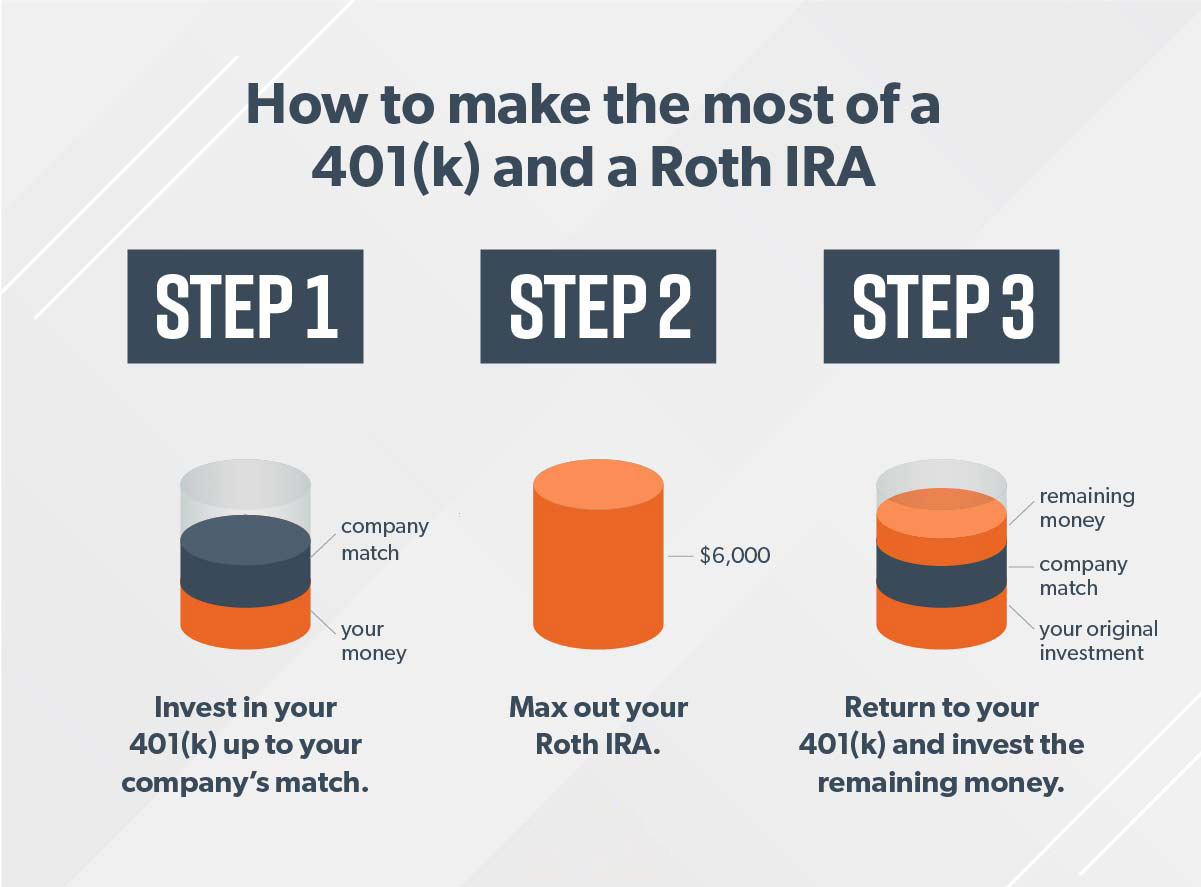 How Much Can You Contribute To 401k Roth
The Catch (Because There's Always One)
Not every employer offers a Roth 401(k) option. Some plans just haven't gotten the memo yet. Check your benefits portal before you do a happy dance.
Also, traditional 401(k) contributions could lower your current taxable income, which means you pay less tax this year. Roth contributions won't do that. So if you're in a high tax bracket right now, the traditional side gives you immediate relief.
But hey — future retiree you might high-five you for stocking up on those Roth dollars. That's priceless.
How Do You Actually Do It?
Check your company's 401(k) settings. Most modern plan providers let you designate a split right in the portal.
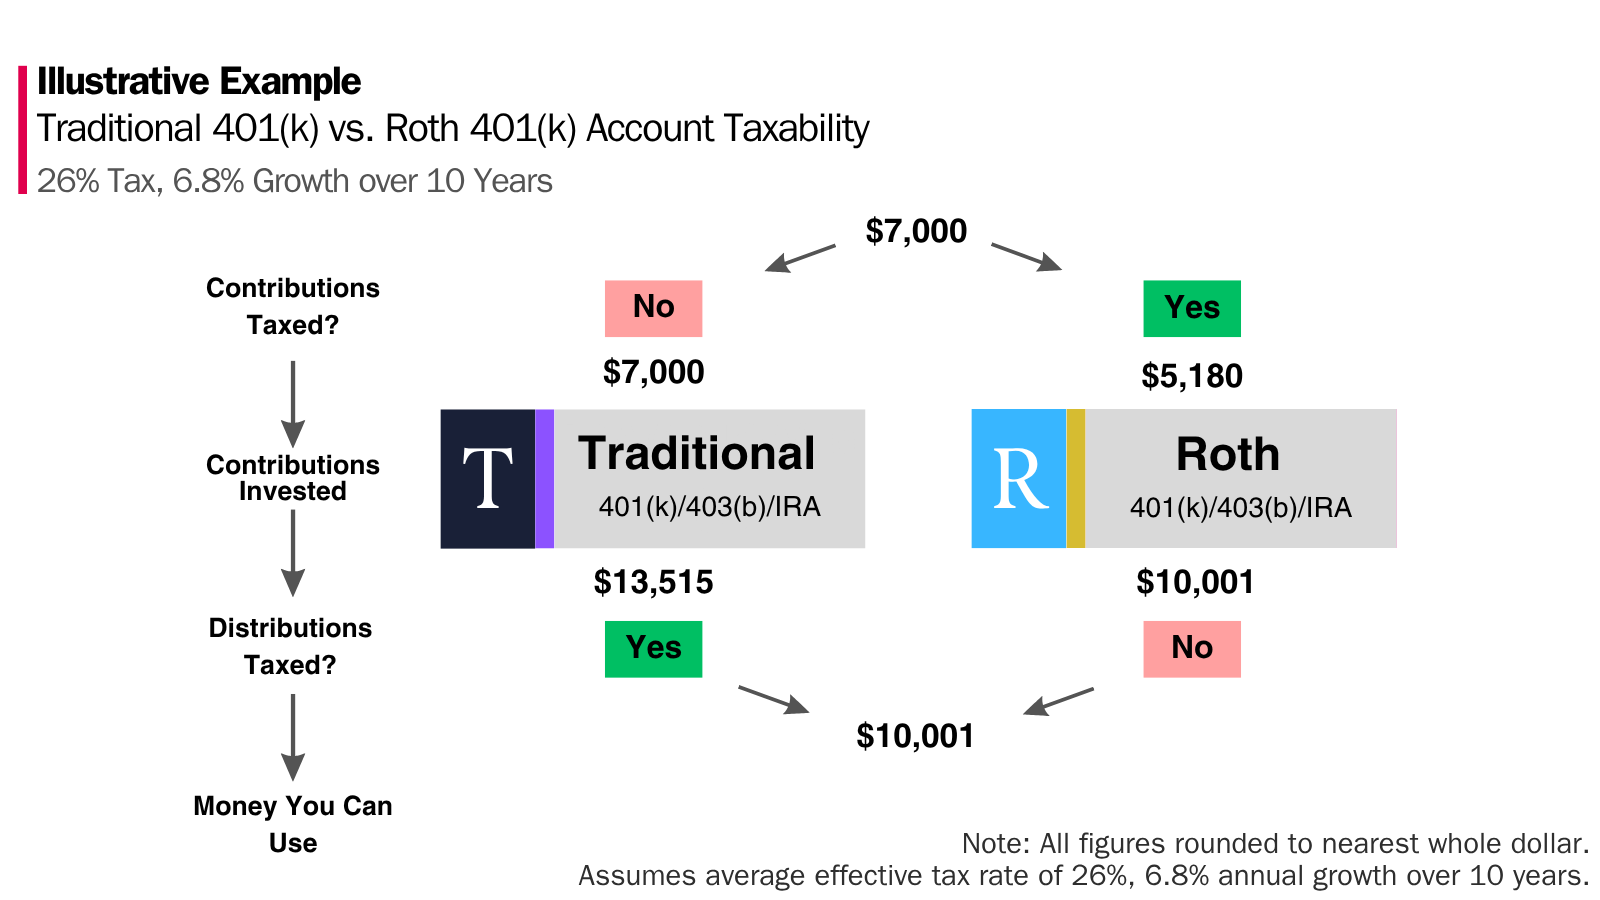 Plan with Purpose: 401(k) and IRA Contribution Limits for 2026
Some setups default to 100% traditional, so you'll need to manually flip the switch. It takes about two minutes. Less time than it takes to microwave leftovers.
If your plan doesn't allow it, politely ask HR. Companies update plans all the time, and your question might spark a whole new benefit rollout.
Quick and Quirky Recap
You can contribute to both a 401(k) and a Roth 401(k) simultaneously. The IRS gives you one shared contribution limit, and you decide how to slice it.
It's like financial Tetris — fit the pieces together however works best for your life. And honestly? There's something thrilling about optimizing your money game this way.
So go check that 401(k) dropdown menu. Your future self is waiting, wearing sunglasses, sipping something cold, and totally vibing with your tax strategy.