
Okay, let's be honest — almost nobody wakes up excited to think about home equity loan rates. But stick with me here, because understanding how a 30-year fixed home equity loan works might just save you a small fortune. Think of it as learning the rules to a game where the house always wins — except this time, the house is your house.
So what's the deal with a home equity loan? Imagine you've paid off some of your mortgage over the years, and your home is now worth more than what you still owe. That extra value? It's called equity, and you could borrow against it like dipping into a savings jar you didn't know you had.
Why the "30-Year Fixed" Part Matters
Ever notice how some loans feel like that friend who keeps getting louder as the night goes on? Variable rates can bounce around like a toddler on a trampoline. A 30-year fixed rate, on the other hand, is the reliable friend who shows up on time, every time.
Must Read
Fixed means your rate — and your monthly payment — stays the same for the entire life of the loan. That could be three long decades of sameness, which honestly feels pretty comforting when uncertainty is the default setting in life. You always know exactly what's leaving your account each month, no surprises, no panic attacks on the 15th.
What Do the Rates Actually Look Like?
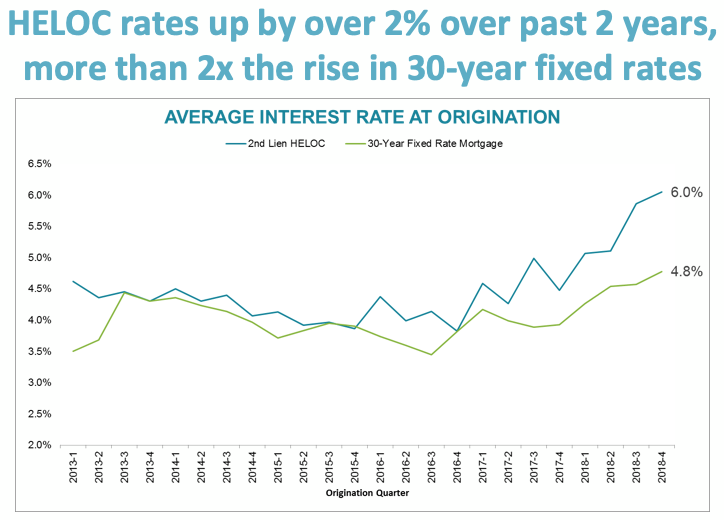
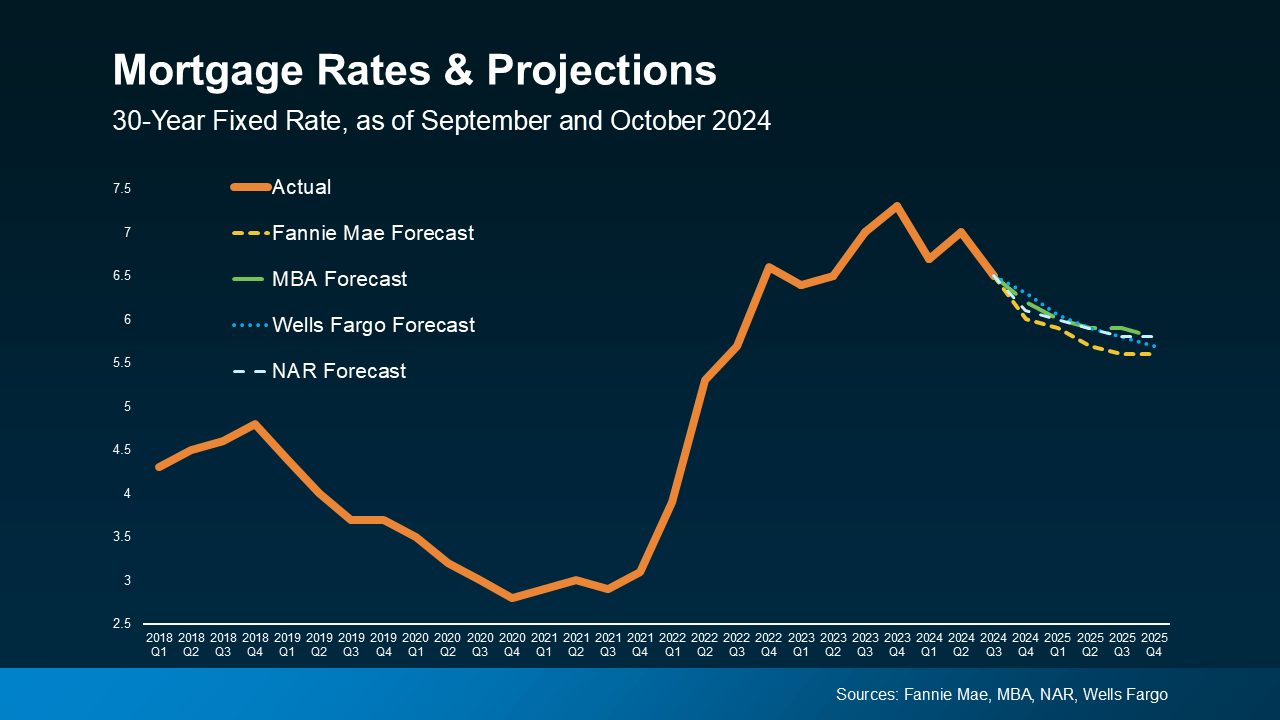
Now here's the part everybody googles at 2 a.m. — what are the rates right now? Depending on your credit score, the market, and the lender's mood, 30-year fixed home equity loan rates can range from around 7% to 9% or more. It's like shopping for shoes: the better your credit score, the fancier the pair you can afford.
 Home equity loans are cheaper than credit cards, end of story - The
Your lender will consider things like your debt-to-income ratio, how much equity you've built, and whether your house could double as a prop in a real estate magazine. All this stuff together determines the number that shows up on your paperwork. And trust me, that number matters a lot over 360 monthly payments.
So Why Should You Actually Care?
Maybe you've been dreaming about renovating that kitchen that screams "1987" every time you walk in. Or maybe you're thinking about paying off a few high-interest credit cards that have been quietly bleeding your wallet dry. A home equity loan could fund those plans without draining your checking account — as long as you borrow wisely.
 Your Guide to Current Mortgage Rates | DSLD Mortgage
But here's the gentle-yet-important warning: your house is the collateral. That means if you fall behind on payments, you're not just dealing with a cranky phone call. You could be dealing with something far more serious, so borrow only what you can comfortably repay.
How to Get the Best Rate You Can
Start by giving your credit score a little love — a quick check could reveal easy fixes that nudge it upward. Compare offers from at least three lenders, because rates can vary more than you'd expect between banks and credit unions. And don't be shy about asking questions — a good lender won't roll their eyes at a curious homeowner.
 What To Expect from Mortgage Rates and Home Prices in 2025 - Real
It also helps to have a clear idea of what you need the money for. If you can point to a concrete plan — new roof, college tuition, debt consolidation — the entire process feels less scary and more strategic. You're not just borrowing money; you're making a deliberate investment in your future.
So the next time someone mentions home equity loan rates, you can nod with a knowing smile instead of a blank stare. It's not the most thrilling topic at a dinner party, but it could absolutely change your financial life. And honestly, that's worth a second look.