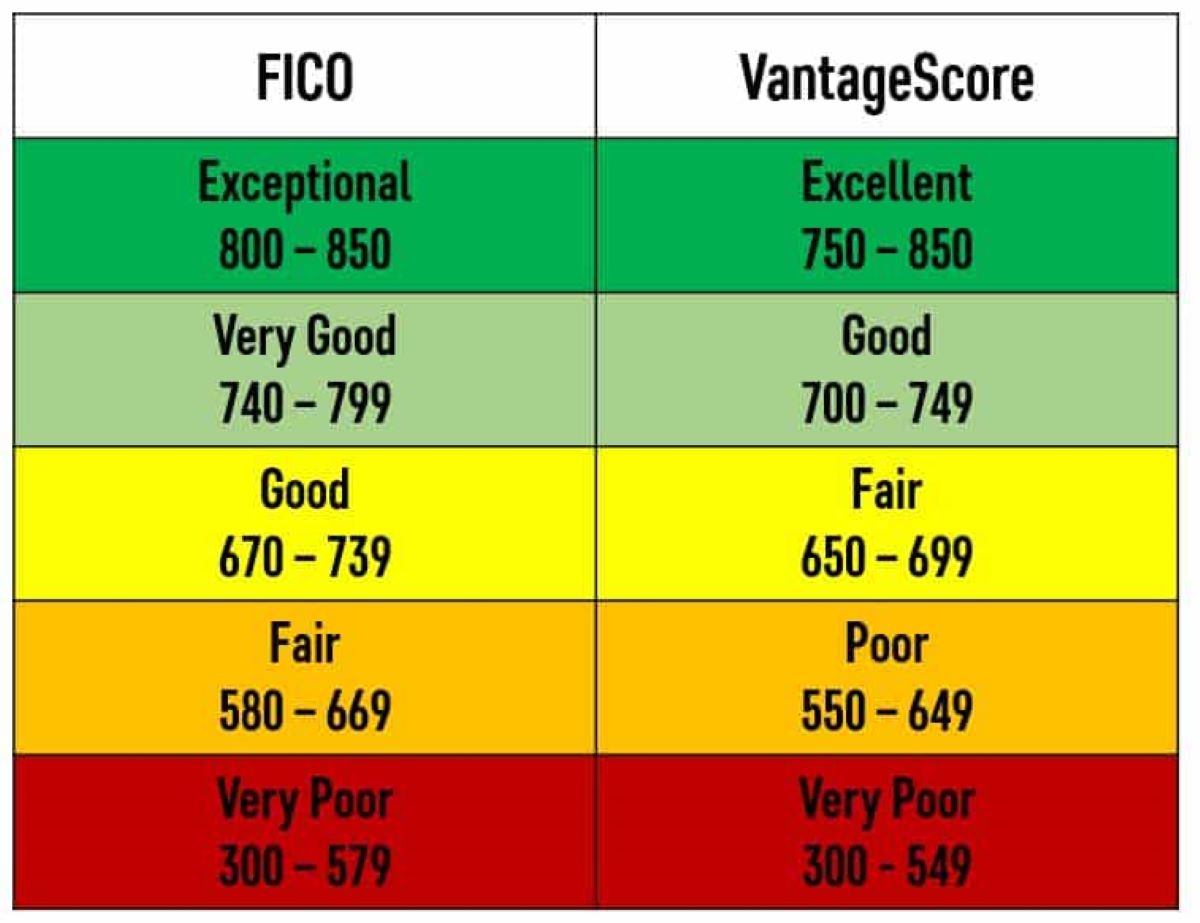
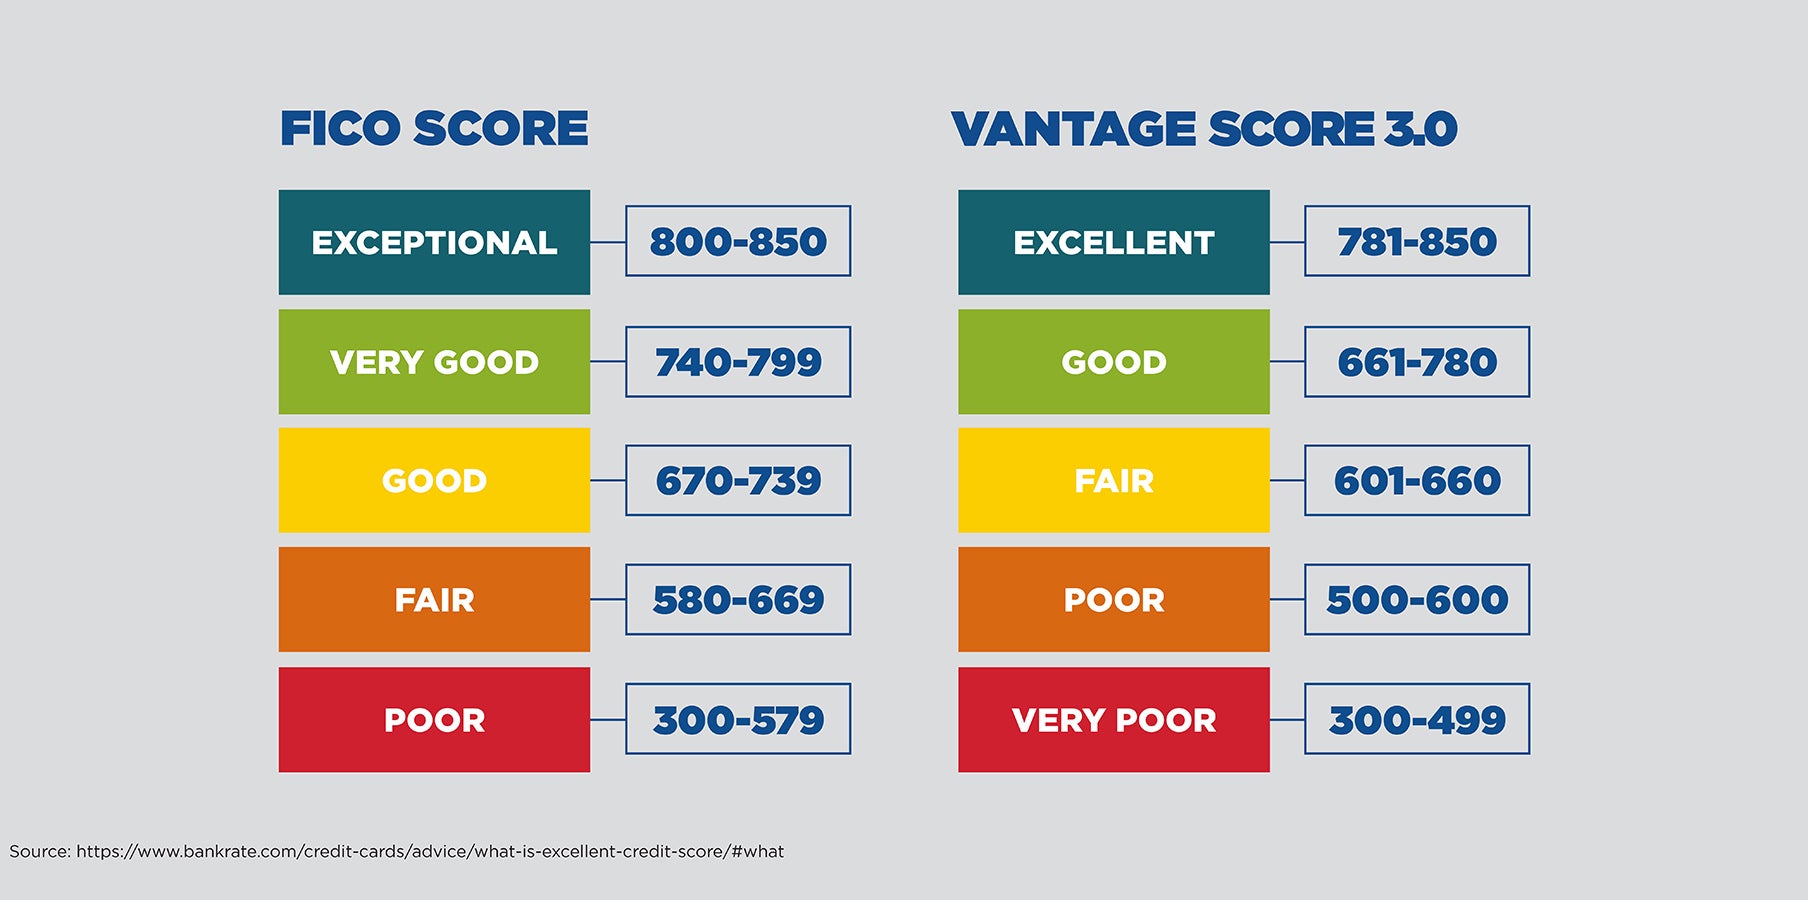
So here's your Tuesday morning coffee, a splash of oat milk, and a confusing mystery: you check your credit scores and one says 740 while the other says 690. One is your FICO score, the other is your VantageScore, and you're now convinced the financial universe personally has it out for you. Let's figure out why your VantageScore keeps showing up looking like it just lost a speed eating contest to your FICO.
Two Companies, Two Rulebooks
Here's the thing: FICO and VantageScore are different products made by different people. Think of it like Pepsi versus Dr. Pepper — same category, dramatically different personalities. Each company has its own secret sauce for crunching your credit data.
FICO was built by Fair, Isaac and Company way back in 1989, and it became the score lenders have been obsessed with for decades. VantageScore showed up much later in 2006 as the scrappy newcomer, developed jointly by the three credit bureaus. They're both trying to measure your creditworthiness, but they're reading from completely different instructions.
Must Read
The Data Diploff
FICO typically needs at least six months of credit history before it'll even recognize you exist. VantageScore, on the other hand, can score someone with as little as one month of history — which is cute, but it also means it's scoring a wider, messier crowd of borrowers. More data points in the pool sometimes means your number gets dragged down if that extra periphery thing you've got going on looks sketchy to VantageScore.
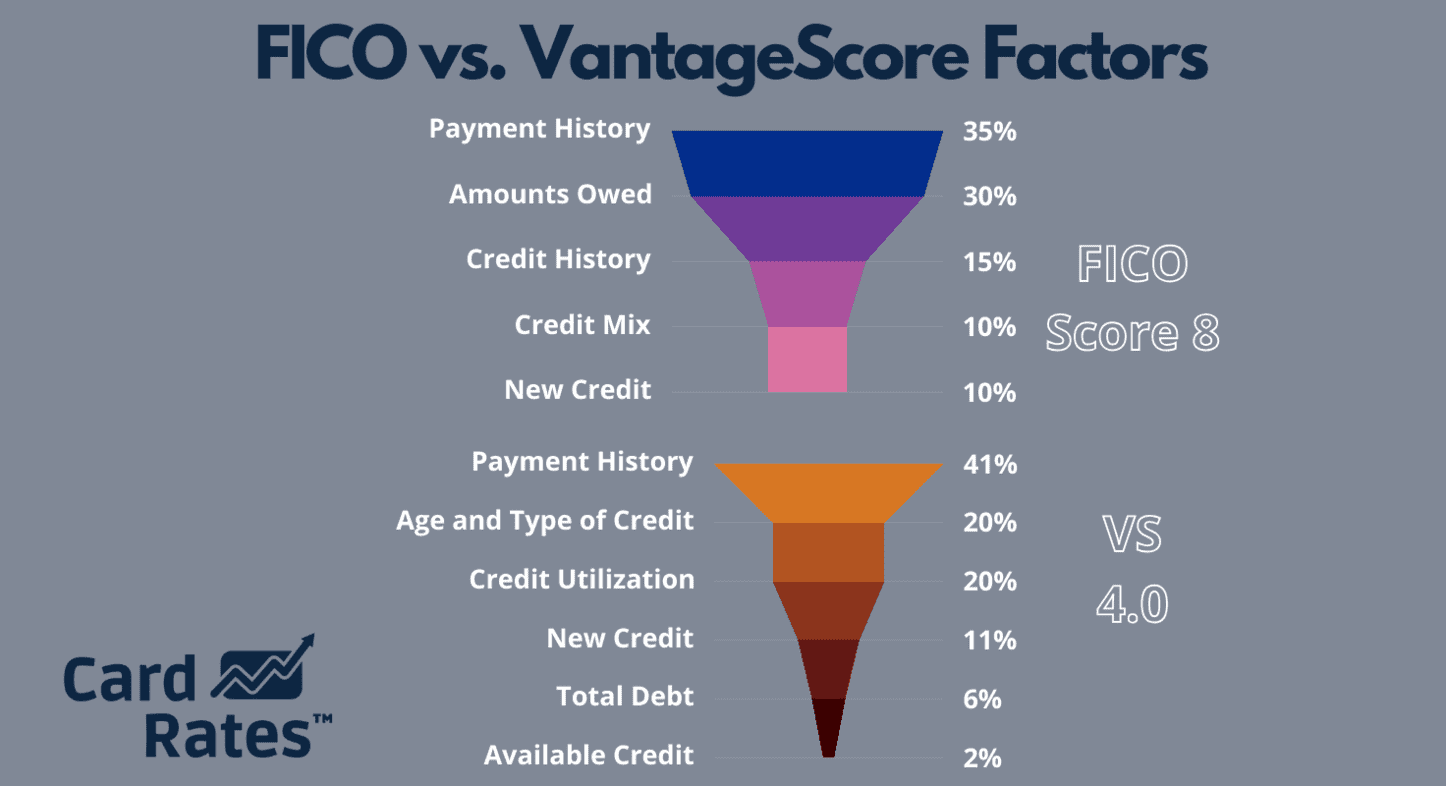
Each model also weights categories differently. VantageScore tends to lean harder on things like recent credit inquiries and shorter payment histories, while FICO might give you a bit more credit for long-standing accounts. It's like one teacher focusing on homework and the other obsessing over pop quizzes.
 What's a Credit Score? | First Command
The Algorithm Has Feelings (Sort Of)
VantageScore 4.0 introduced some pretty innovative tricks, like excluding medical debt from collection influence and factoring in utility payments. Yet despite these upgrades, it sometimes still reads your credit file with a stricter lens, especially if your profile is thin or slightly unusual. The higher number you saw from FICO might partly come from the fact that lenders based their assumptions around a model tuned for decades of real-world lending data.
Also, a mind-blowing fun fact: studies have shown that VantageScore historically produces lower average scores across the population compared to FICO. It's not that VantageScore is broken — it just tends to be a little more pessimistic, like a credit score dad who always says "expect the worst, hope for the best." Your numbers aren't lying; they're just viewed through slightly different glasses.
 What is a FICO Score? How it Impacts Lending Terms and Credit Decisions
What You Should Actually Do
First, relax — a lower VantageScore doesn't automatically mean your credit is in shambles. Most lenders still rely heavily on FICO, though VantageScore is sneaking into more and more places. Keep doing what you're doing: pay bills on time, keep balances low, and avoid opening too many new accounts at once.
Think of it as having two spectators watching your financial game: one claps wildly while the other takes notes with a cross on the review sheet. Neither one is completely right or wrong — it's just how they interpret your story.
So the next time your VantageScore makes you feel like you're governed by a credit score that woke up choose hostility, just remember: different math, different mood, same financial you. And honestly? If a credit score has you that stressed, maybe it's time to laugh about it over another cup of coffee — this time with fewer numbers involved.