The Credit Karma card has quickly become a favorite among users who want to monitor their credit and earn rewards in one place. Its popularity stems from a simple interface, free credit reports, and the promise of instant alerts when something changes.
When the card works smoothly, it gives individuals a clear picture of their financial health, helps families plan big purchases, and supports communities by encouraging responsible spending habits. A well‑timed credit score update can turn a doubtful loan application into a confident yes.
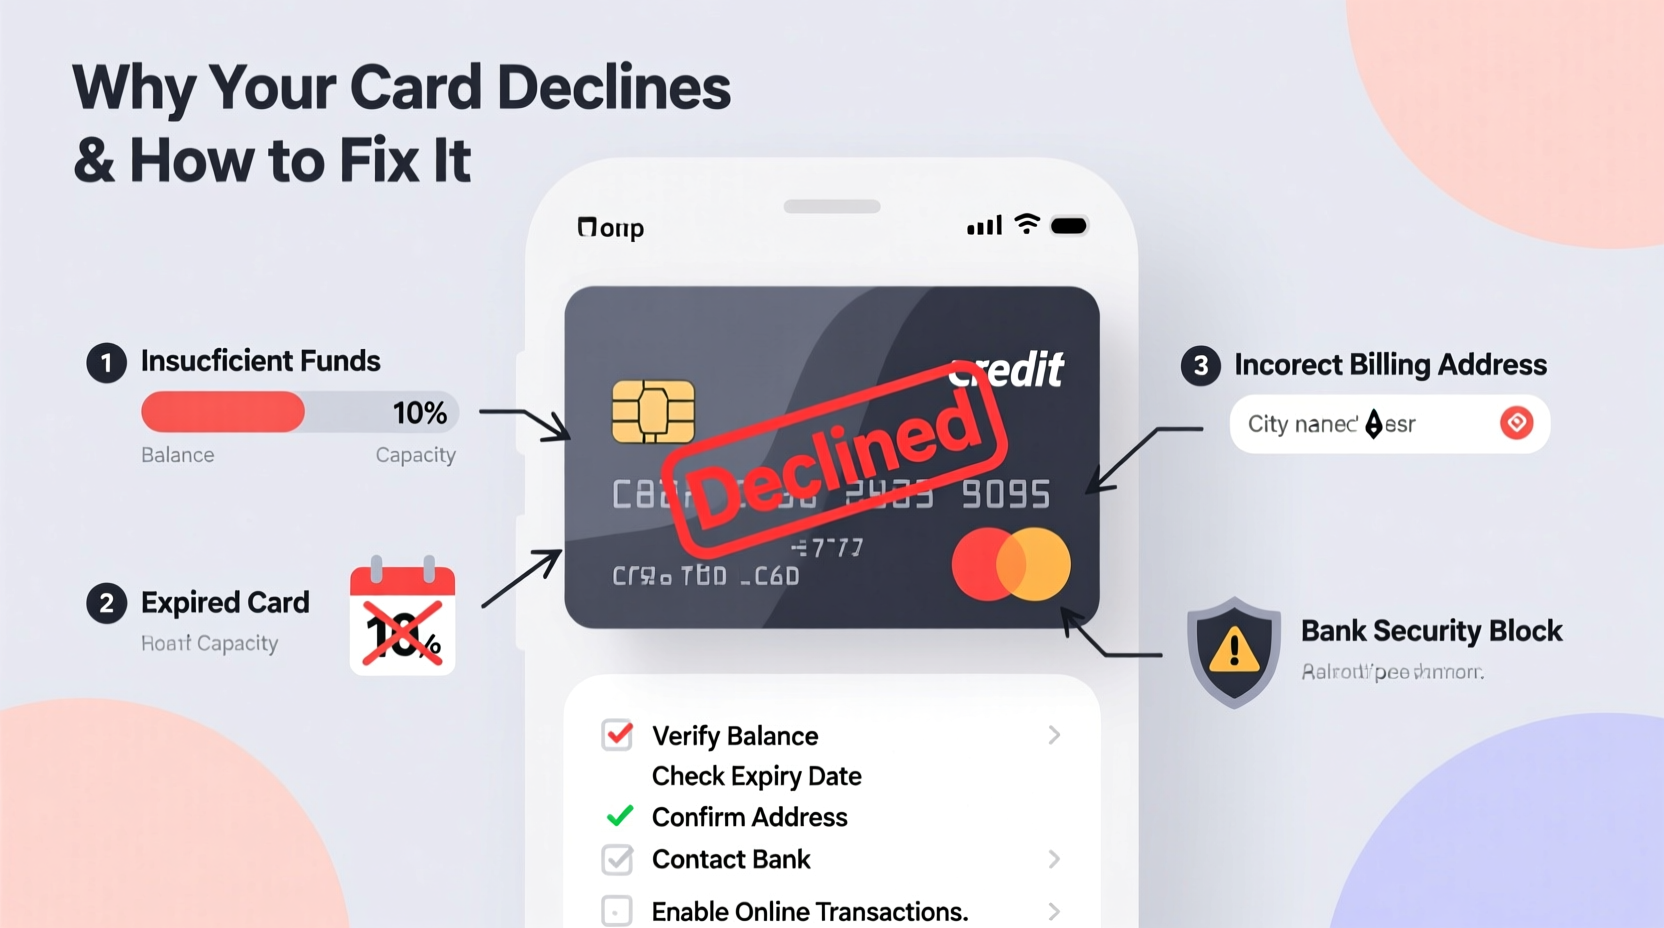
So, why does it sometimes decline? The most common culprits are a sudden dip in your credit score, recent large transactions that trigger fraud alerts, or an outdated billing address. In addition, a temporary hold can occur if the system detects unusual activity, protecting both you and the issuer.
Must Read
Take Emily, who saw her card rejected while buying a car; she later discovered a recent credit inquiry had lowered her score. Similarly, a family in Ohio experienced a decline after a vacation charge flagged as “outside usual spending,” but a quick call explained the situation.
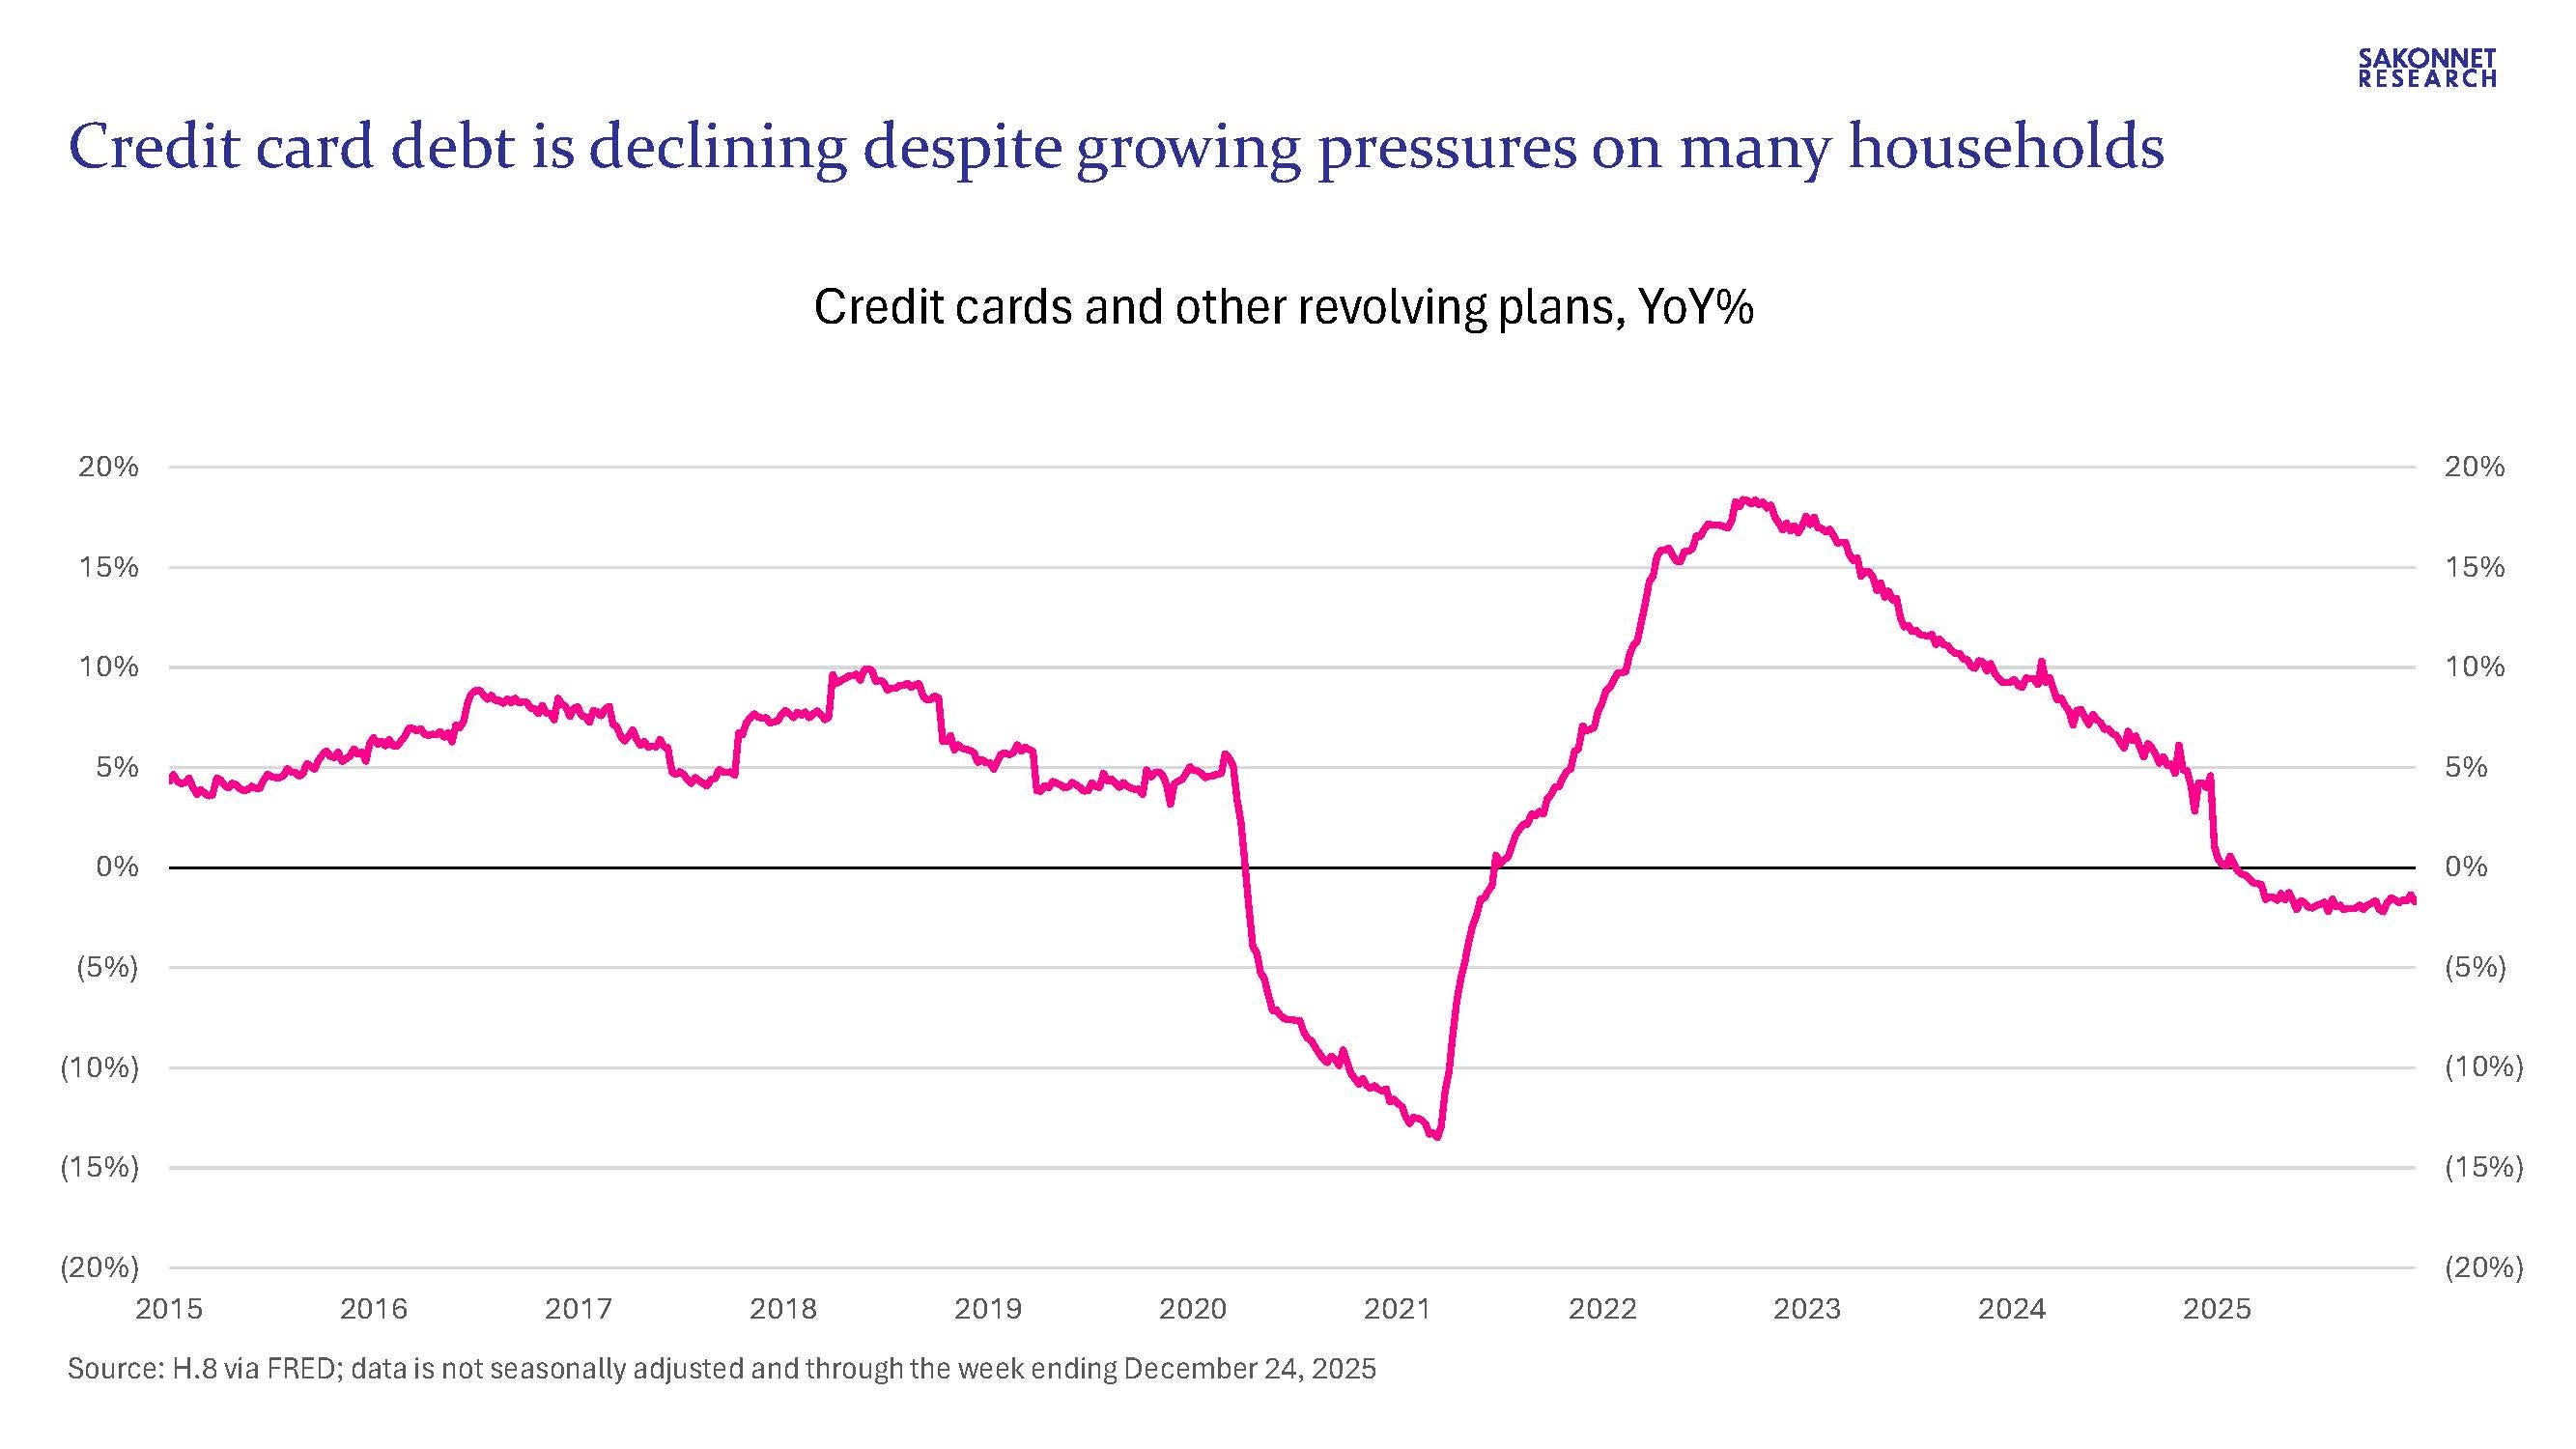
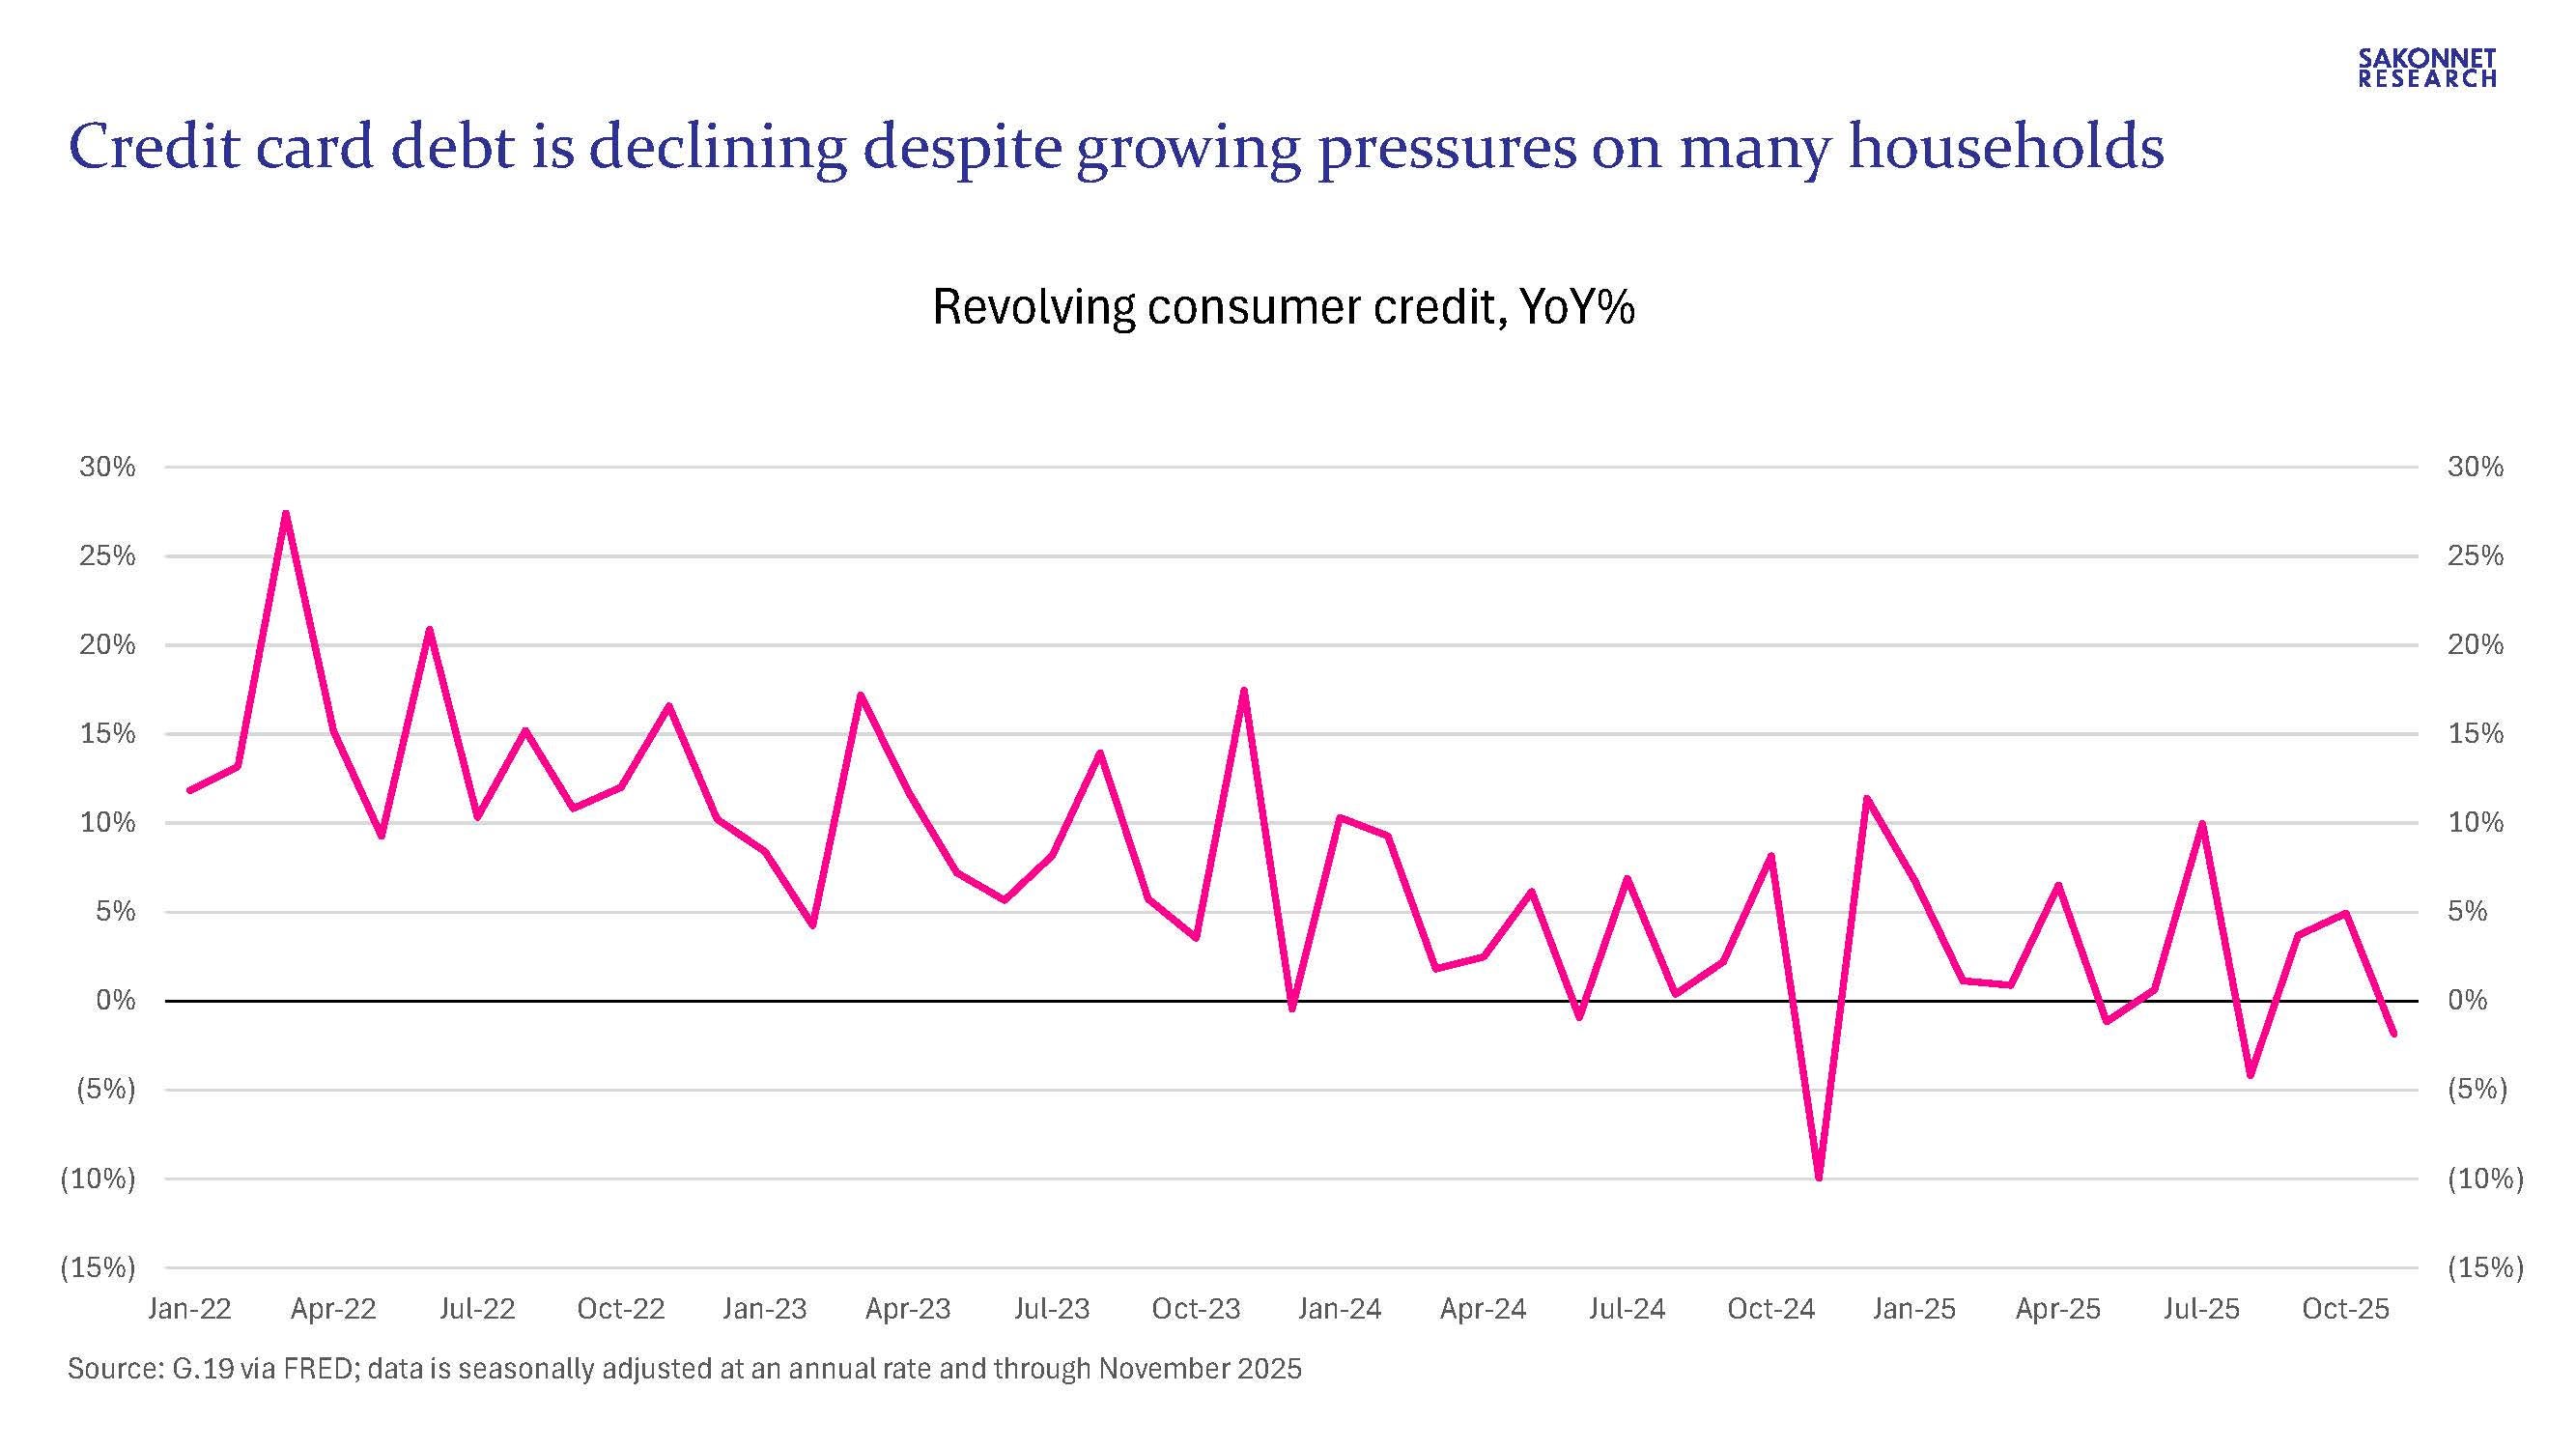 Credit Card Debt Declining Amid Growing Financial Pressures
To keep the card refilling your pockets without interruptions: regularly monitor your credit score, update contact info, and notify the issuer before large travel or purchasing sprees. Using the mobile app’s transaction alerts lets you act fast if something looks off.
Overall, the Credit Karma card remains a valuable tool for anyone seeking financial clarity. By staying aware of potential decline triggers and following simple safeguards, you can enjoy its benefits without surprise hiccups.