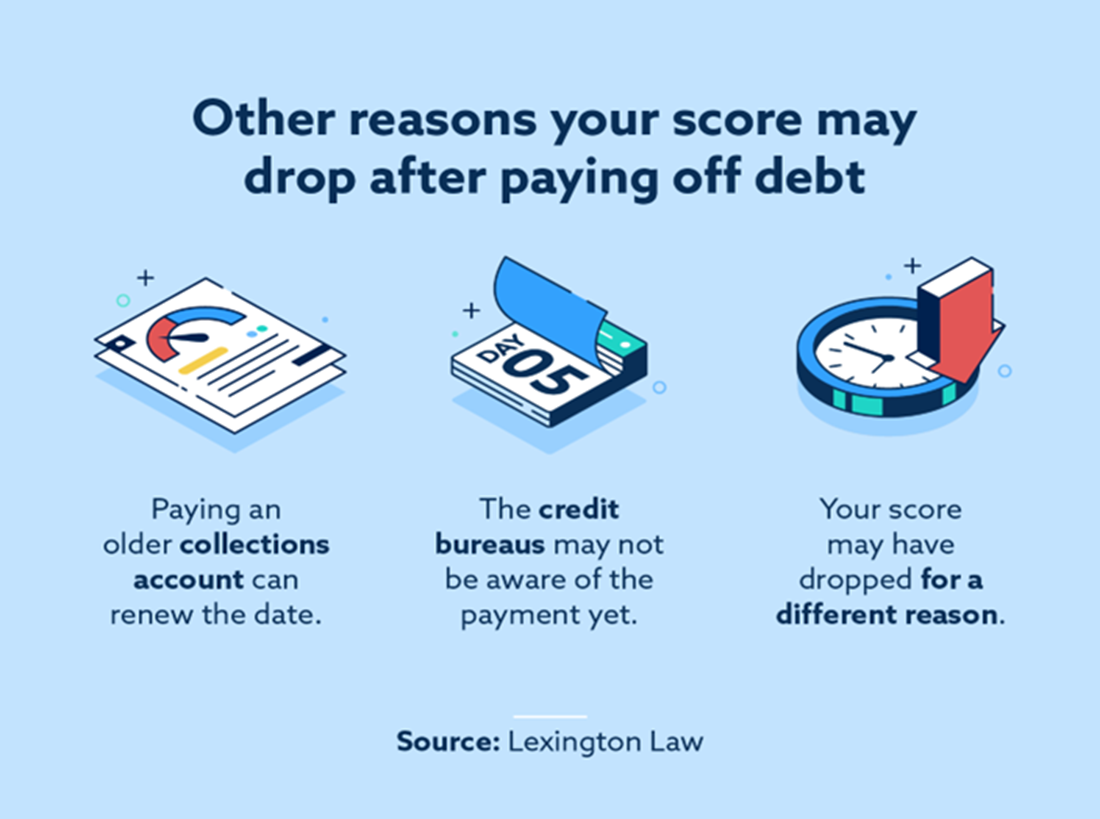
Ever logged into your banking app, casually checking your finances like a responsible adult, and noticed your credit score took an unprompted dip? Don't panic — you haven't accidentally insulted anyone's grandmother. Credit scores are dynamic, and sometimes they shift for reasons that seem totally random but are usually pretty explainable.
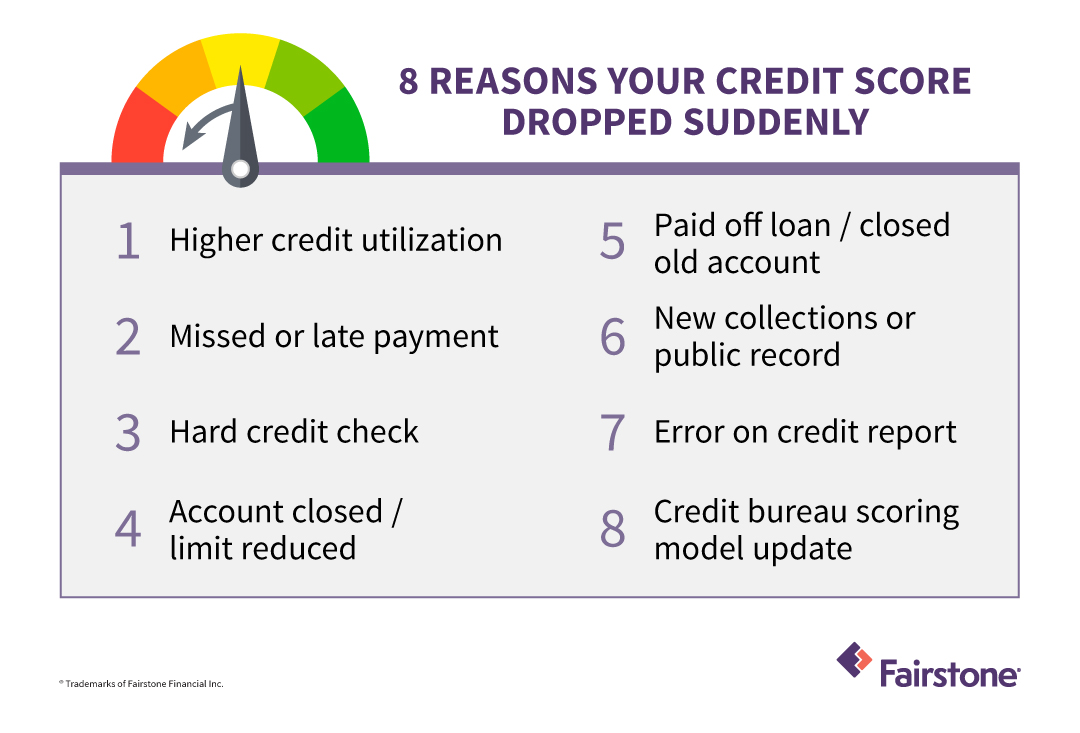
The most common culprit? Payment history. If you missed even one small payment — yes, even that $12 subscription you forgot about — it can ding your score. Your payment history is everything in the credit world, and lenders remember everything. Spooky, right?
Another sneaky reason is credit utilization. If you suddenly maxed out a card paying for something exciting (hello, Black Friday), your score might dip because you're using a larger chunk of your available credit. Try keeping that number below 30%, folks.
Must Read
Then there's the big one: hard inquiries. Applying for a new credit card, auto loan, or mortgage triggers a hard check, which temporarily lowers your score. Think of it like a neighbor peeking into your finances — it happens, and it's noticed. Meanwhile, those free credit monitoring apps you signed up for? Those are soft inquiries, so they're harmless. Phew!
Also, empty credit history hurts. If you closed an old credit card account, you may have shortened your credit age, which isn't great for your score. Lenders prefer a long, steady track record.
 Credit Score Dropped 100 Points For No Reason | Detroit Chinatown
The good news? Credit score dips are almost always temporary. Pay your bills on time, keep balances low, and avoid opening too many accounts at once, and you'll bounce right back. Your score isn't a permanent stamp — it's more like a mood ring, constantly shifting based on your financial habits.
So take a deep breath, snake oil, and remember: your financial journey is a story, not a sentence. Every dip is just a plot twist before the happy ending. You've got this — and your credit score is rooting for you too! 😊