Let's be real: seeing your credit score dip by even 10 points can drive you crazy. It's one of the most-searched credit questions out there because it affects how much you pay in interest, whether you get approved for loans, and even some job prospects. Understanding why it happened puts you back in control.
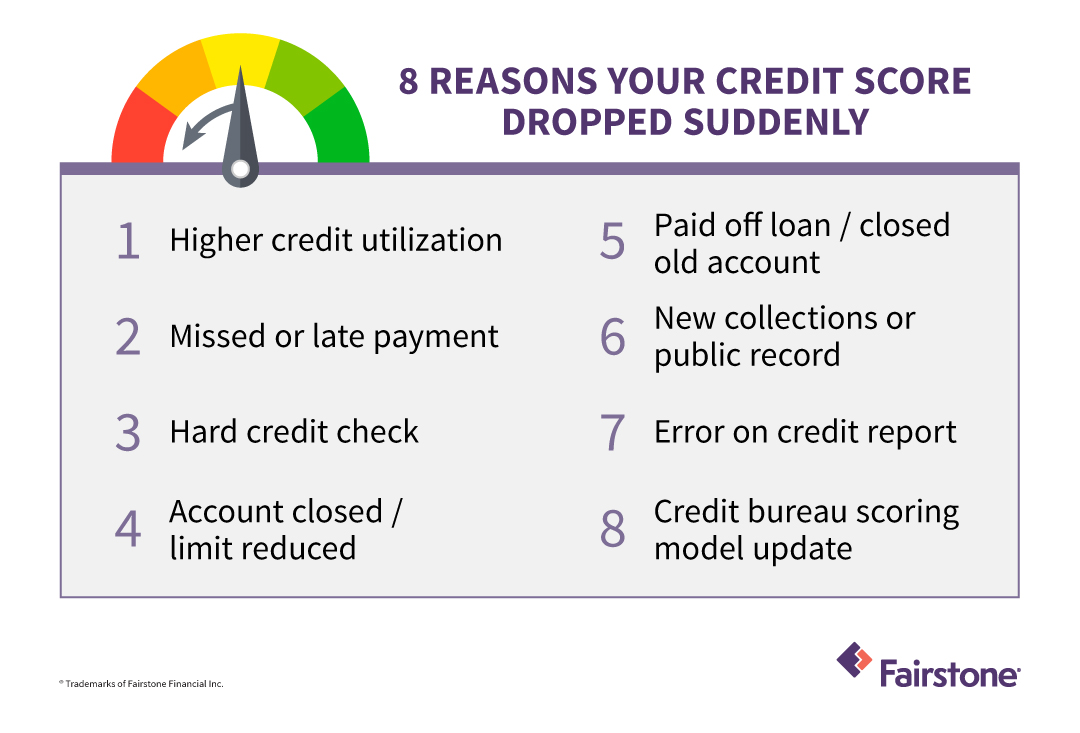
One common culprit is a sudden spike in your credit utilization ratio. If you charged a big-ticket item — say, a new refrigerator — your available balance shrinks fast. Even if you pay on time, that jump alone can account for a 10-point slip. Keep spending under 30% of your limit whenever possible.
Another culprit is hard inquiries. Applying for a mortgage, car loan, or even a new credit card triggers a lender's credit check. Each check can shave a few points. Families shopping for homes often notice this when they compare multiple lenders in a short window — totally normal, but it stings to watch.
Must Read
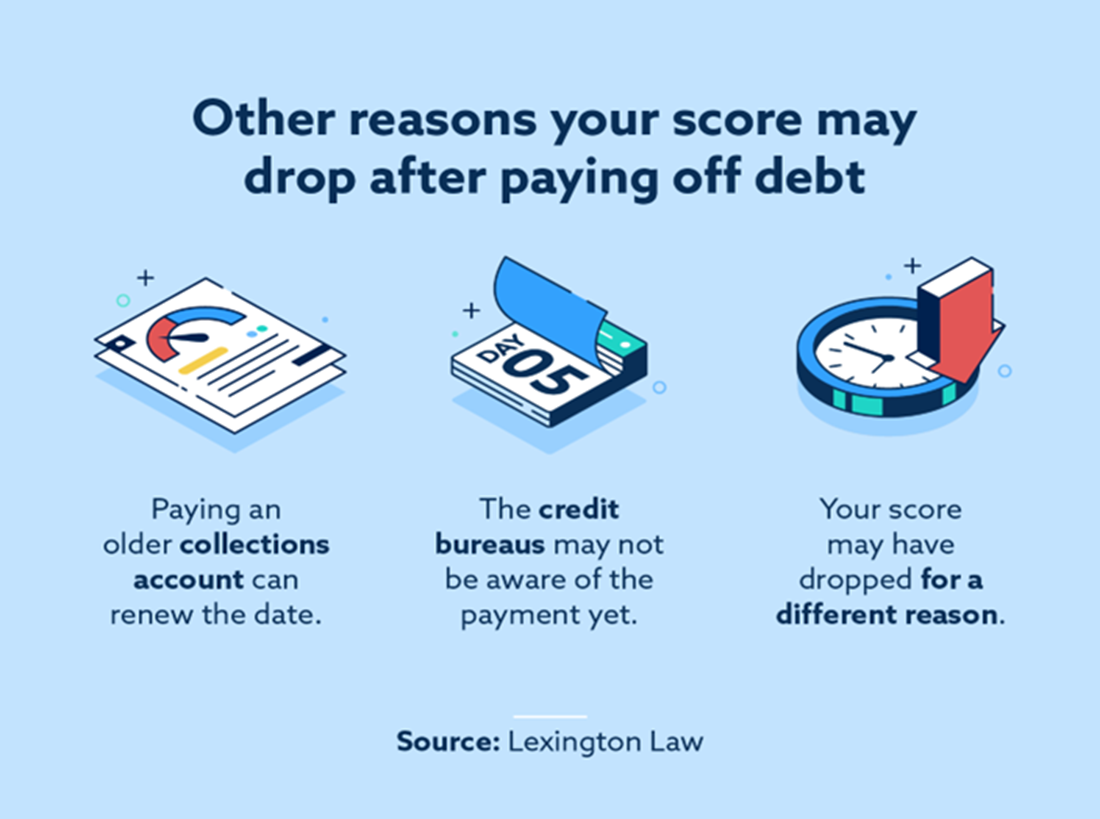
Timing matters too. Sometimes your score drops simply because an older negative item is still hanging around, or because payment histories got newer. Credit scoring formulas constantly recalculate, so your score can move without any mistake on your part.
 Why Your Credit Score Dropped (and What to Do About It) | The Dispute Coach
Community-minded tip: check your report for errors. A wrongly reported missed payment from two years ago could be dragging you down unfairly. Disputing it is free and can restore points quickly.
To stay proactive: set payment reminders, keep balances low, and avoid unnecessary hard pulls. Credit scores are built for the long game — one small dip won't define you. Stay informed, act calmly, and your score will recover. You've got this.