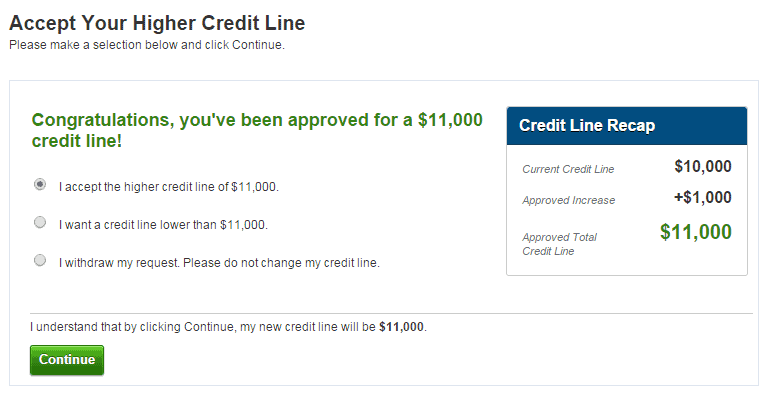
Opening a surprise gift that makes everyday purchases smoother and opens doors to bigger opportunities. It’s a quick, friendly move that keeps your budget flexible, your credit score very happy, and rewards you with more buying power.
A higher credit line gives you more breathing room for unexpected expenses, reduces the chance of hitting your original limit, and improves your credit utilization ratio—a solid key factor in your overall score. Benefits include smoother cash‑flow management, better perk eligibility, and a sense of financial freedom.
The sweet spot to ask is typically after you’ve built a solid payment history for at least six months. If you’ve just landed a raise, secured a new job, or paid down existing debt, these signals show lenders that you’re a reliable borrower ready for a larger line.
Must Read
Think beyond basics—some cardholders request increases ahead of a family vacation, a home‑improvement project, or an emergency fund sprint. Mapping those upcoming needs to a higher limit turns the request into a strategic plan rather than a random ask, making approval more likely.
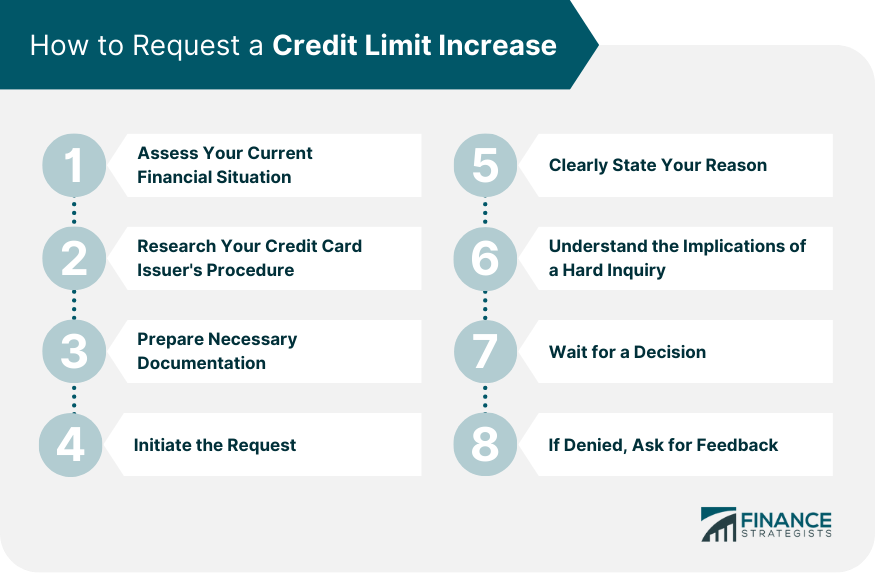
Start by checking your current account status—log in, locate the increase request option, and prepare recent statements that show on‑time payments. Submit the form right after you receive a favorable credit‑score update; timing the request with good news often nudges banks to say yes.
 How Often Does Credit One Increase Credit Line at Lynn Morgan blog
Finally, follow up courteously if there’s a delay, and monitor your limit for any automatic adjustments. Keep using the new credit responsibly—pay in full, stay under 30% utilization, and enjoy the extra cushion that makes budgeting feel like a game you’re winning.
Remember, a credit‑limit increase isn’t a one‑time stunt—it’s an invitation to treat your card as a flexible tool. By timing your ask, showcasing good habits, and staying vigilant, you turn a simple request into a long‑term boost for both your wallet and credit health.