
You've probably heard someone say, "Don't touch your retirement savings!" But what does that actually mean when it comes to your IRA? Let's break it down in a way that doesn't put you to sleep.
An Individual Retirement Account (IRA) is basically your future self's piggy bank. It's money you tuck away now so that when you're sipping lemonade on a porch at 65, you don't have to worry about bills. The government gives you sweet tax perks for keeping your hands off it.
The General Rule: Wait Until You're 59½
Most of the time, you can't withdraw money from your IRA before age 59½ without paying a penalty. Think of it like a frozen treat straight from the freezer — you could try eating it, but it's going to hurt. That 10% early withdrawal penalty is the "ouch" factor nobody enjoys.
Must Read
On top of the penalty, you'll owe regular income taxes on whatever you pull out. So a $5,000 withdrawal could actually cost you a lot more than $5,000. Ouch, indeed.
But Life Isn't Always Patient
Here's where things get a little friendlier. The IRS understands that life throws curveballs, so there are exceptions to the penalty. Think of these as emergency exits in a building — they're there for when things get real.
 Backdoor Roth IRA: How it Works · IMPACTADVISOR · Eliminate the Tax Drag
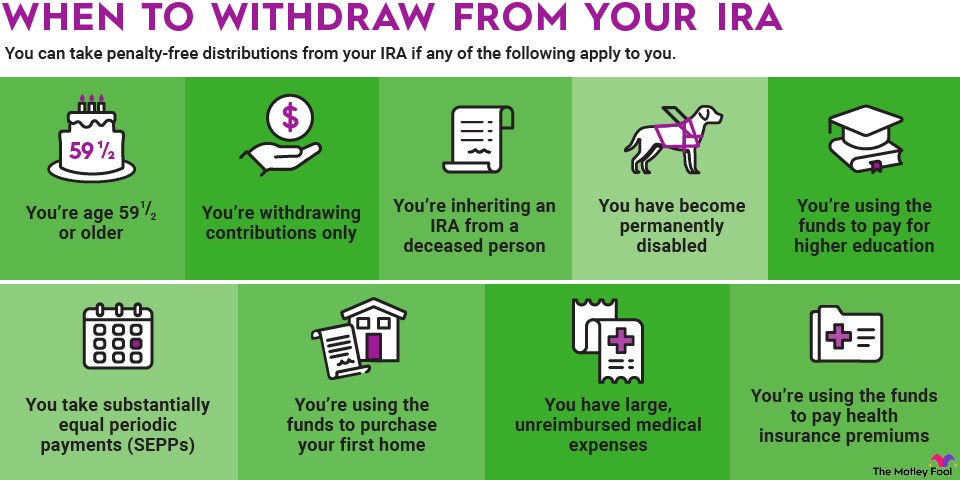
You can withdraw penalty-free if you're buying your first home. Imagine finally scraping together a down payment and running into a wall because of your own retirement account. The IRS says, "Okay, we'll let this one slide."
Medical Emergencies and Education
If a medical crisis hits and your insurance doesn't cover everything, you can dip into your IRA without the penalty. Nobody should have to choose between treatment and retirement savings during a scary moment. That just doesn't sit right with anyone.
Need to pay for higher education? Qualified education expenses qualify as another exception. Whether it's you going back to school or your kid heading to college, the penalty can be waived.
 IRA Withdrawal Age: Understanding IRA Withdrawal Rules | Blog
Disabilities and Unemployment
If you become permanently disabled, withdrawing from your IRA penalty-free is allowed. Life already changes everything at that point, and the IRS recognizes it. Sometimes flexibility is exactly what you need.
Lost your job after 55? There's a little-known rule that lets you pull money without the 10% penalty. It's not a huge window, but it can be a lifeline between jobs during a tough stretch.
Required Minimum Distributions (RMDs)
Once you hit 73, the government almost insists that you start taking money out. These are called Required Minimum Distributions, and skipping them brings its own penalty. It's like a scheduled meeting — you really don't want to be late.
 Rules for IRA Withdrawals | The Motley Fool
The amount depends on your account balance and age. It's the IRS's way of saying, "You saved well — now go enjoy it!" Fair enough, right?
Roth IRA? A Slightly Different Story
If you have a Roth IRA, there's a golden rule: contributions can come out anytime, tax and penalty-free. Since you already paid taxes on that money before putting it in, the IRS has nothing left to collect. It's one of the best perks of choosing a Roth in the first place.
Why You Should Care
Knowing your options is like having a game plan before the game starts. Impulsive withdrawals can cost you thousands, and that's pain no one needs. A little knowledge today saves serious money tomorrow — and that's definitely worth smiling about.