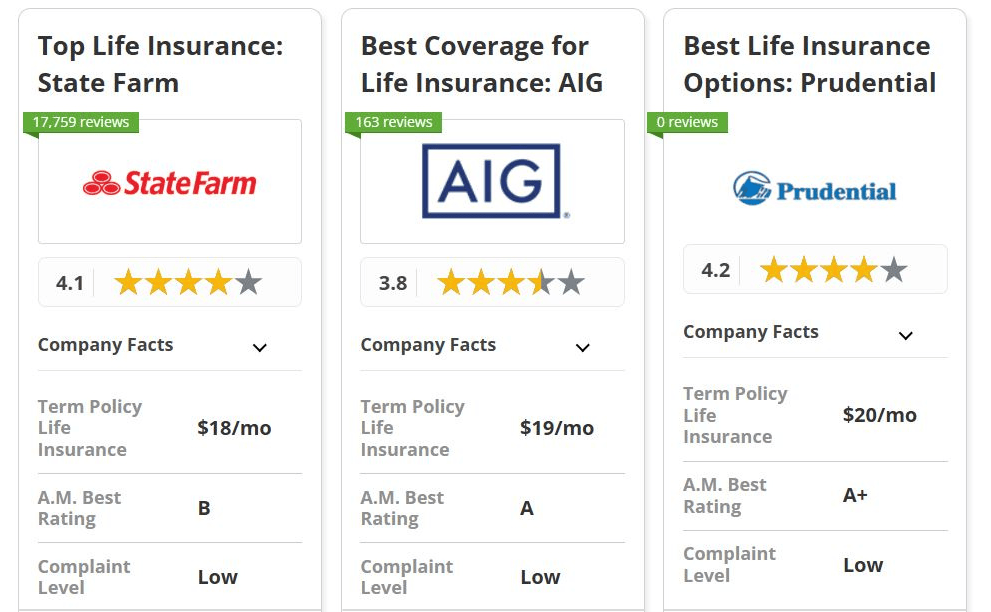
First, let's get one thing straight: life insurance is like a gym membership for your future. Nobody wants it, everybody thinks they'll need it "one day," and yet here we are, finally talking about it over coffee.
Here's a wild fact you probably didn't know—the concept of life insurance dates back to ancient Rome. Those gladiators had their own version of a policy. Grim, yes, but at least they were proactive about it.
Term Life Insurance: The Burger Kings of Policies
Term life insurance is the plain-transparency-wrap of the insurance world. You pay a low monthly premium for coverage that lasts a specific period—usually 10, 20, or 30 years.
Must Read
If you die during that term, your beneficiaries get paid. If you don't, the funds go back to the insurance company, and you've essentially bought peace of mind like a Netflix subscription your family gets to binge.
This option is perfect for young families, debt-heavy millennials, and anyone who wants maximum coverage without selling a kidney. It's affordable, straightforward, and doesn't come with a side of confusing investment jargon.
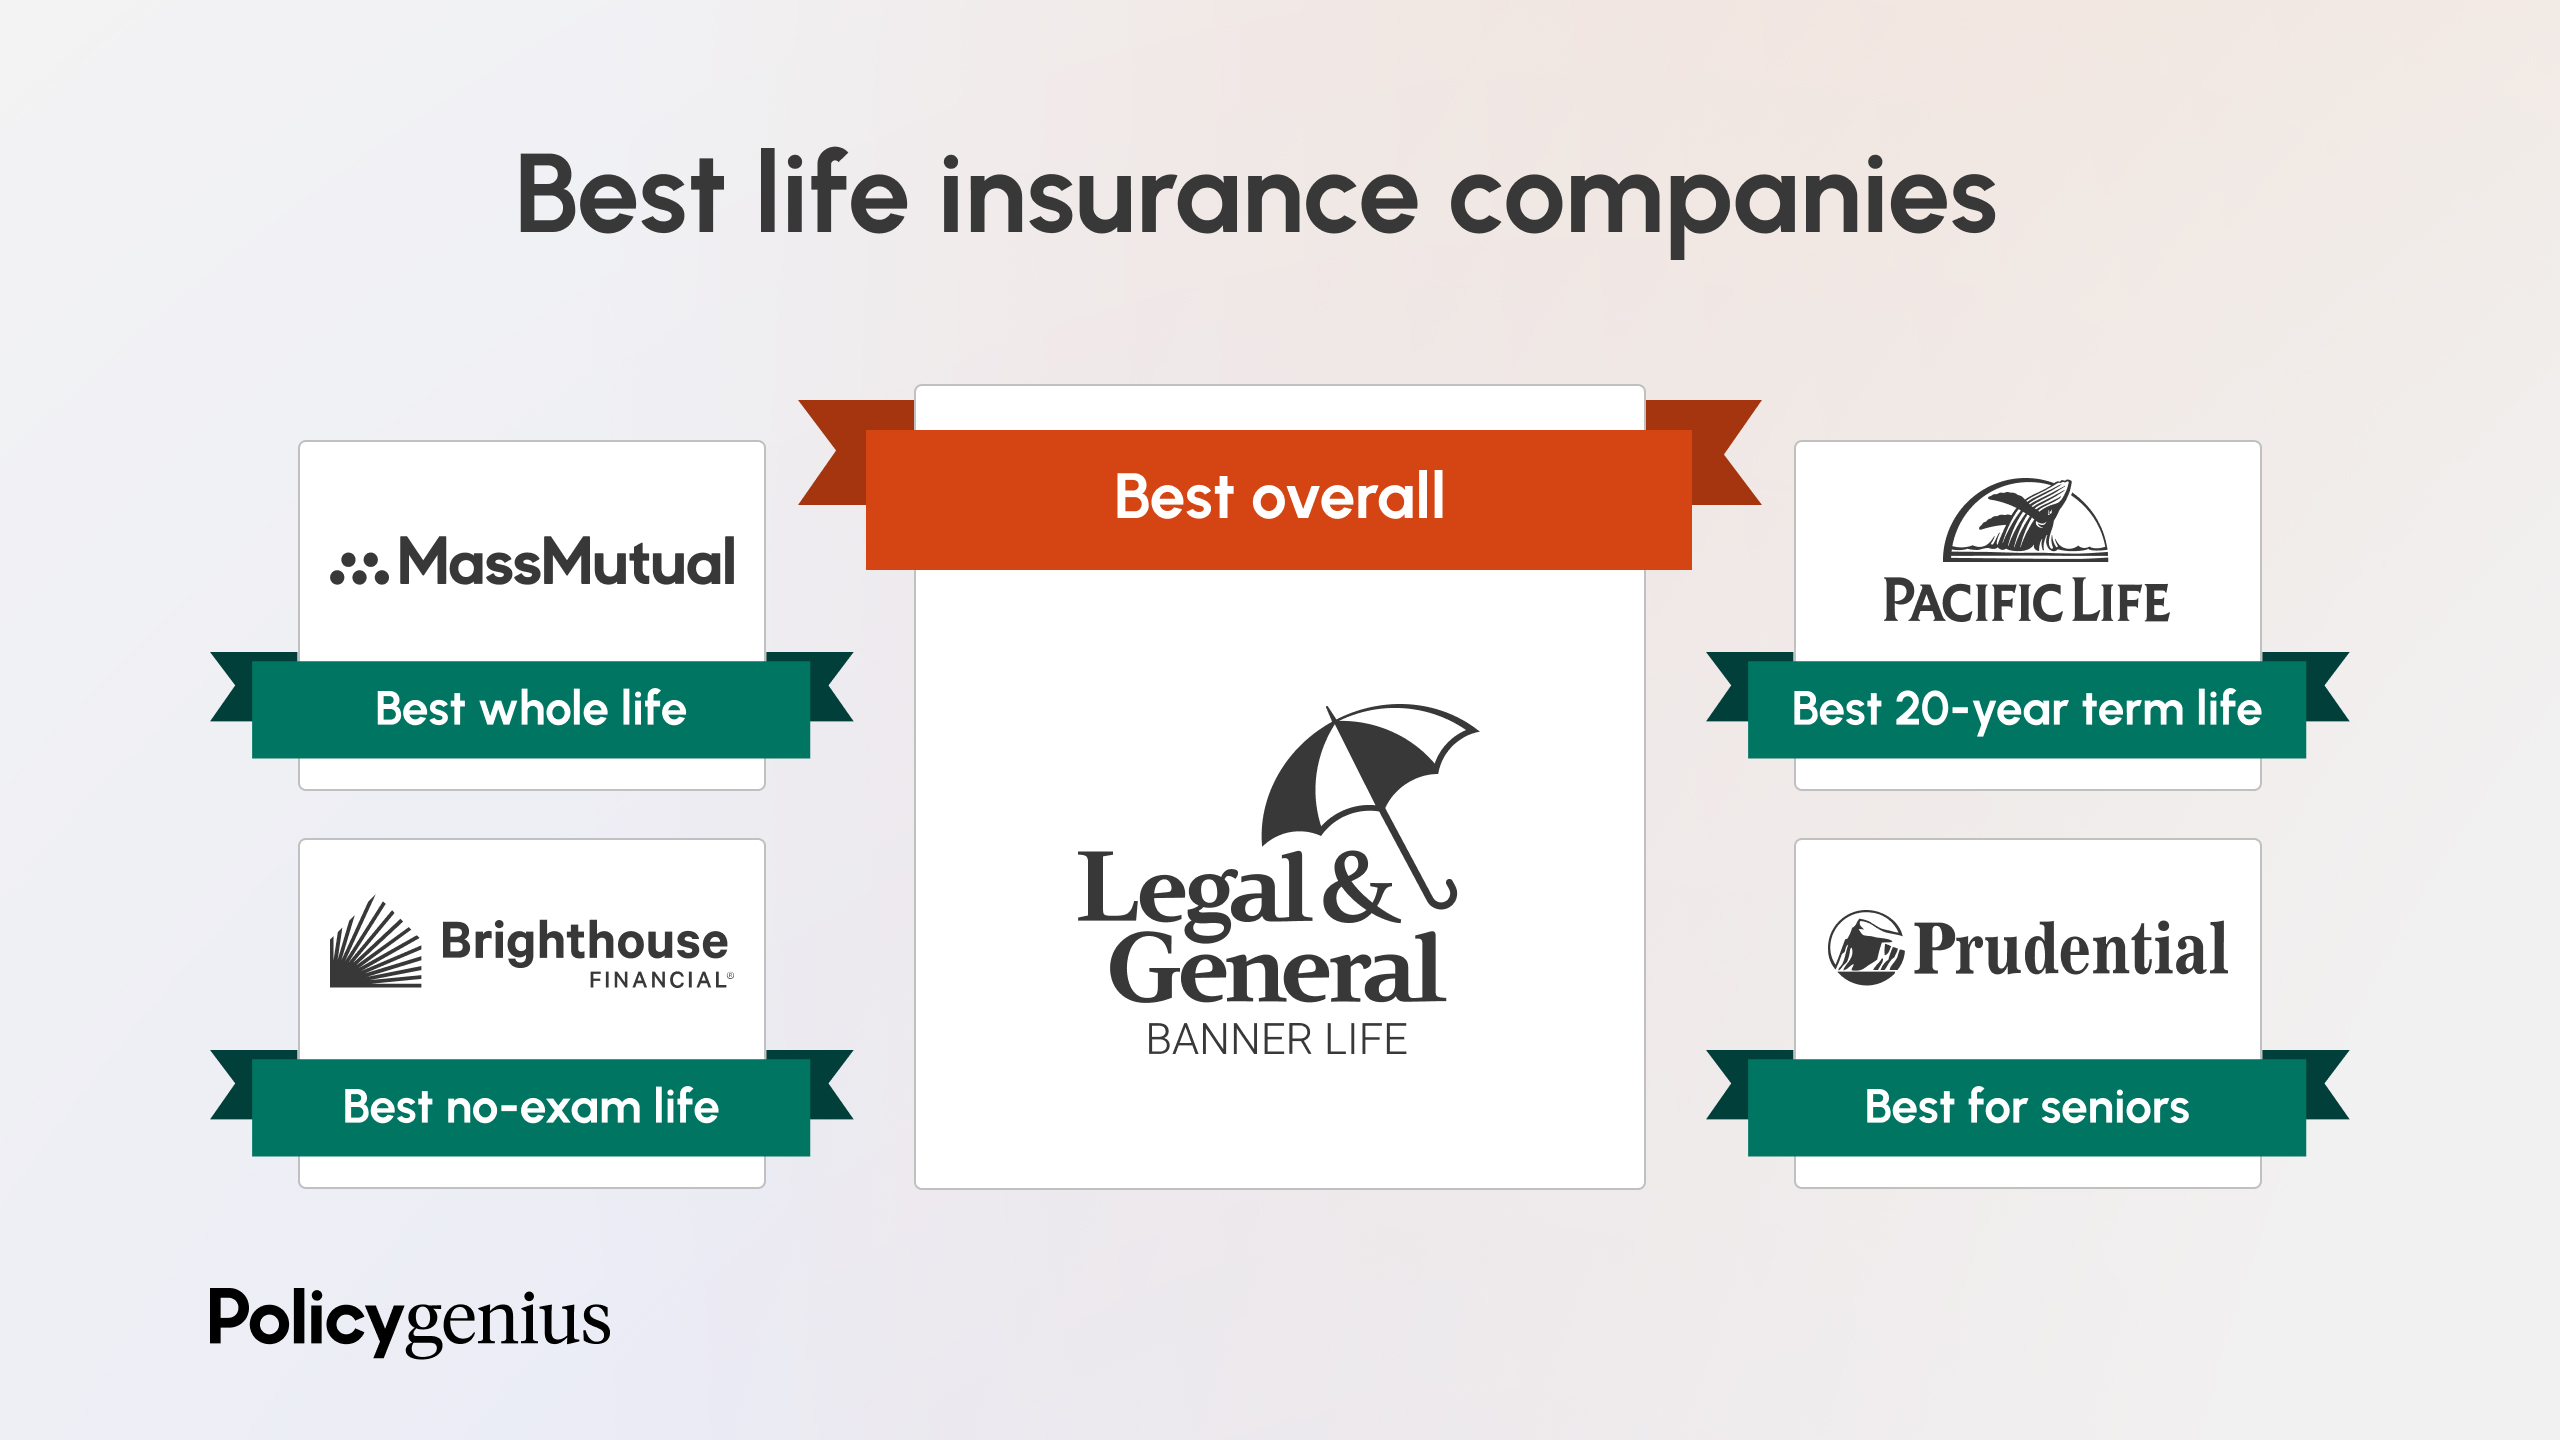 Best Life Insurance Companies – Policygenius
Whole Life Insurance: The All-You-Can-Eat Buffet
Whole life insurance sticks around forever—well, as long as you keep paying. It's more expensive than term life, but it builds cash value over time, kind of like a slow-cooking crockpot for savings.
If you drop dead before repenting your sins—which let's be honest, we all never do—the payout still happens. But if you outlive your policy needs, the accumulated cash value can actually be borrowed against or withdrawn.
Think of it as life insurance that also moonlights as a savings account. A savings account that takes 30 to 40 years to become really impressive, much like your uncle's carpentry skills.
 10 Best Life Insurance Companies in 2025 (Your Guide to the Top
Universal Life: The Chameleon You Never Asked For
Universal life insurance gives you the ability to adjust your premiums and death benefit over time. Imagine ordering a pizza where you can add toppings—or remove them—whenever you feel like it.
It combines the savings element of whole life with the flexibility of term life, but it's also more complex to understand. If you need a PhD-level brain just to figure out your policy, that's probably a red flag.
So Which One Should YOU Actually Buy?
Here's the golden rule, and please write this on your bathroom mirror: Buy what fits your situation, not what makes the salesperson happiest.
 Best Life Insurance Companies [Interactive Comparison Tool]
If you need affordable, no-nonsense coverage, start with term life. If you want money that grows while life goes on, explore whole life or universal options carefully.
Either way, doing something is infinitely better than doing nothing. Because the worst life insurance is the life insurance you keep saying you'll "get around to" one day—one day that never arrives.
So go ahead, be the person who actually thought about death on a Tuesday afternoon. Your future family will thank you, and your insurance agent will practically send you flowers.