
Let’s talk about a common worry that many homeowners face: “what to do if I can’t pay my mortgage.” It’s a practical topic that feels oddly comforting because it turns a stressful situation into a checklist you can actually follow. Knowing you have a step‑by‑step roadmap makes the whole experience feel more manageable and less like a looming catastrophe.
The main purpose of this guide is to give you a clear, actionable plan that protects your home and your credit. By understanding the options early, you can avoid costly penalties, keep your credit score from plummeting, and maintain a solid relationship with your lender. This benefits first‑time buyers, seasoned investors, and anyone caught in an unexpected financial dip.
Consider common variations you might recognize: a sudden job loss, an unexpected medical bill, or a temporary drop in freelance income. Each scenario has its own set of solutions, but they all start with the same basics: assess your current cash flow, prioritize essential expenses, and open a dialogue with the bank before the first missed payment.
Must Read
First, sit down with a simple worksheet and list every source of income versus expenses. Highlight any subscriptions or discretionary spending you can pause. This quick audit often reveals hidden cash flow you can redirect toward the mortgage while you explore longer‑term fixes.
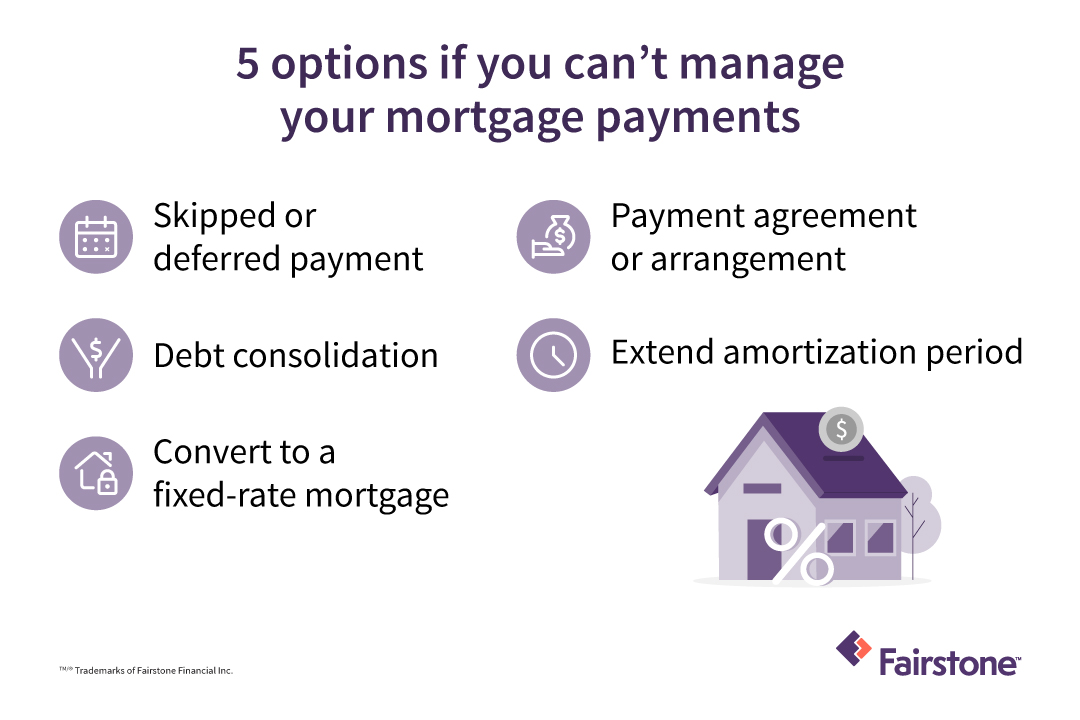 What are my options if I can’t afford my mortgage?
Next, call your mortgage servicer before the due date. Explain your situation honestly, ask about forbearance, loan modifications, or hardship programs. Lenders usually have a menu of options—some may reduce payments temporarily, others may restructure the loan term to lower the monthly amount.
Finally, research local and federal assistance. Programs like the Home Affordable Modification Program (HAMP) or state‑run relief funds can provide the extra cushion you need. Keep all communication in writing, and track every agreement so you can reference it if issues arise later.

