So, you've got an IRA just sitting there, growing its little interest hairs in peace. Suddenly, you need the money — maybe your car exploded, or your dog hired a lawyer. The temptation to cash out that IRA hits you like a wave of common sense you've never known.
The Big Bad 10% . . . and It's Even Worse
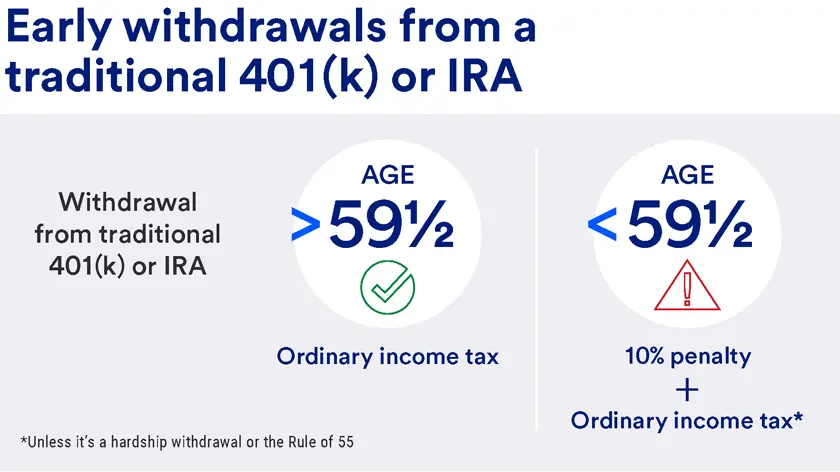
Here's the main course: if you're under 59½ and you pull money out of a traditional IRA, the IRS slaps you with a 10% early withdrawal penalty. That's on top of the ordinary income taxes you'll owe on the whole amount. In other words, you pay twice — once to the taxman and again for being impatient.
Imagine ordering a pizza and the delivery guy says, "Sure, but you owe us the dough, the mozzarella, and a fee for actually eating it." That's essentially what cashing out early feels like. The IRS is the room service of retirement accounts.
Must Read
Where Exactly Does the Money Go?
Let's break it down with a simple example. Say you withdraw $10,000 before your 59½th birthday — put on a party hat, it's coming up. You'd owe your normal income tax (let's say around 22% for many folks) plus the 10% penalty, meaning roughly $3,200 vanishes before you even see the cash.
That leaves you with only $6,800 from a $10,000 withdrawal. One-third of your nest egg just disappeared faster than chargers at a family gathering. Not exactly the smartest financial dance move.
 Ira Roth Withdrawal Penalty Irs: Roth Ira Withdrawal Rules – NQZJBQ
Excuses the IRS Might Actually Accept
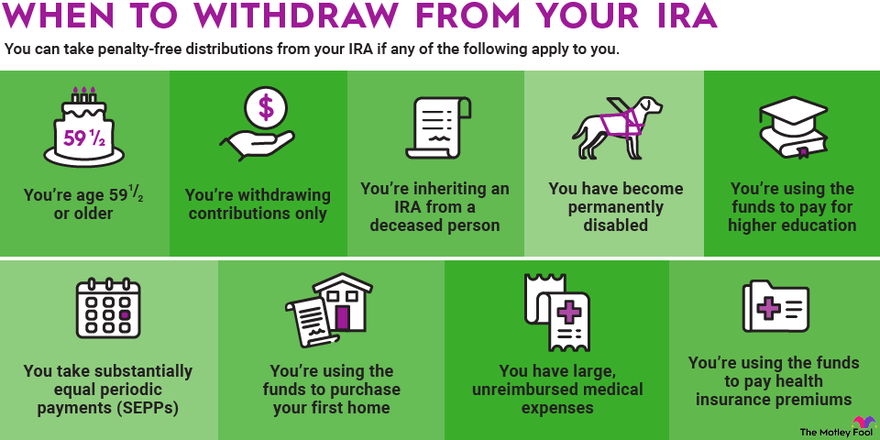
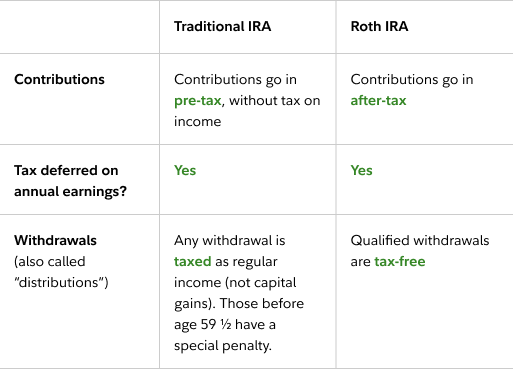
The good news? A few situations let you dodge the 10% penalty like a pro. Contributions to a traditional IRA can be taken back out tax- and penalty-free — contributions, not earnings, at any age. Please reread that golden sentence twice.
Other exception zones include first-time home purchase (up to $10,000), higher education expenses, and health insurance while unemployed. Death, disability, and IRS levies also make the exclusion list. It's like a very boring Costco sample tray of get-out-of-jail-free cards.
 IRA and 401(k) Withdrawal Rules | U.S. Bank
Age 59½: The Magical Firewall
Once you blow out candles at your 59½ birthday party, the penalty disappears entirely. You'll still owe taxes on traditional IRA withdrawals, but at least the IRS stops reaching into your pockets for the extra charge. A Roth IRA, meanwhile, is the chill cousin — qualified withdrawals come out completely tax-free.
Some people actually love the idea that money can't be tempted before retirement. A 10% penalty becomes a built-in babysitter for your savings. Whether you view it as prison or protection depends entirely on your impulse control level.
The Real Moral of the Story
Cashing out an IRA early is like unzipping your tent in the middle of a rainstorm because your marshmallow took too long. It works, sure, but you'll be cold, soggy, and questioning every choice that led to this moment. Unless you absolutely must — we're talking genuine emergencies — do yourself a favor and keep those funds locked in the fridge.
