Choosing the right health insurance plan can feel overwhelming, but understanding how HMO and PPO plans work is the first step toward making a confident decision. These are two of the most common types of health insurance, and each offers a different balance of flexibility, cost, and care access that appeals to people in different life situations.
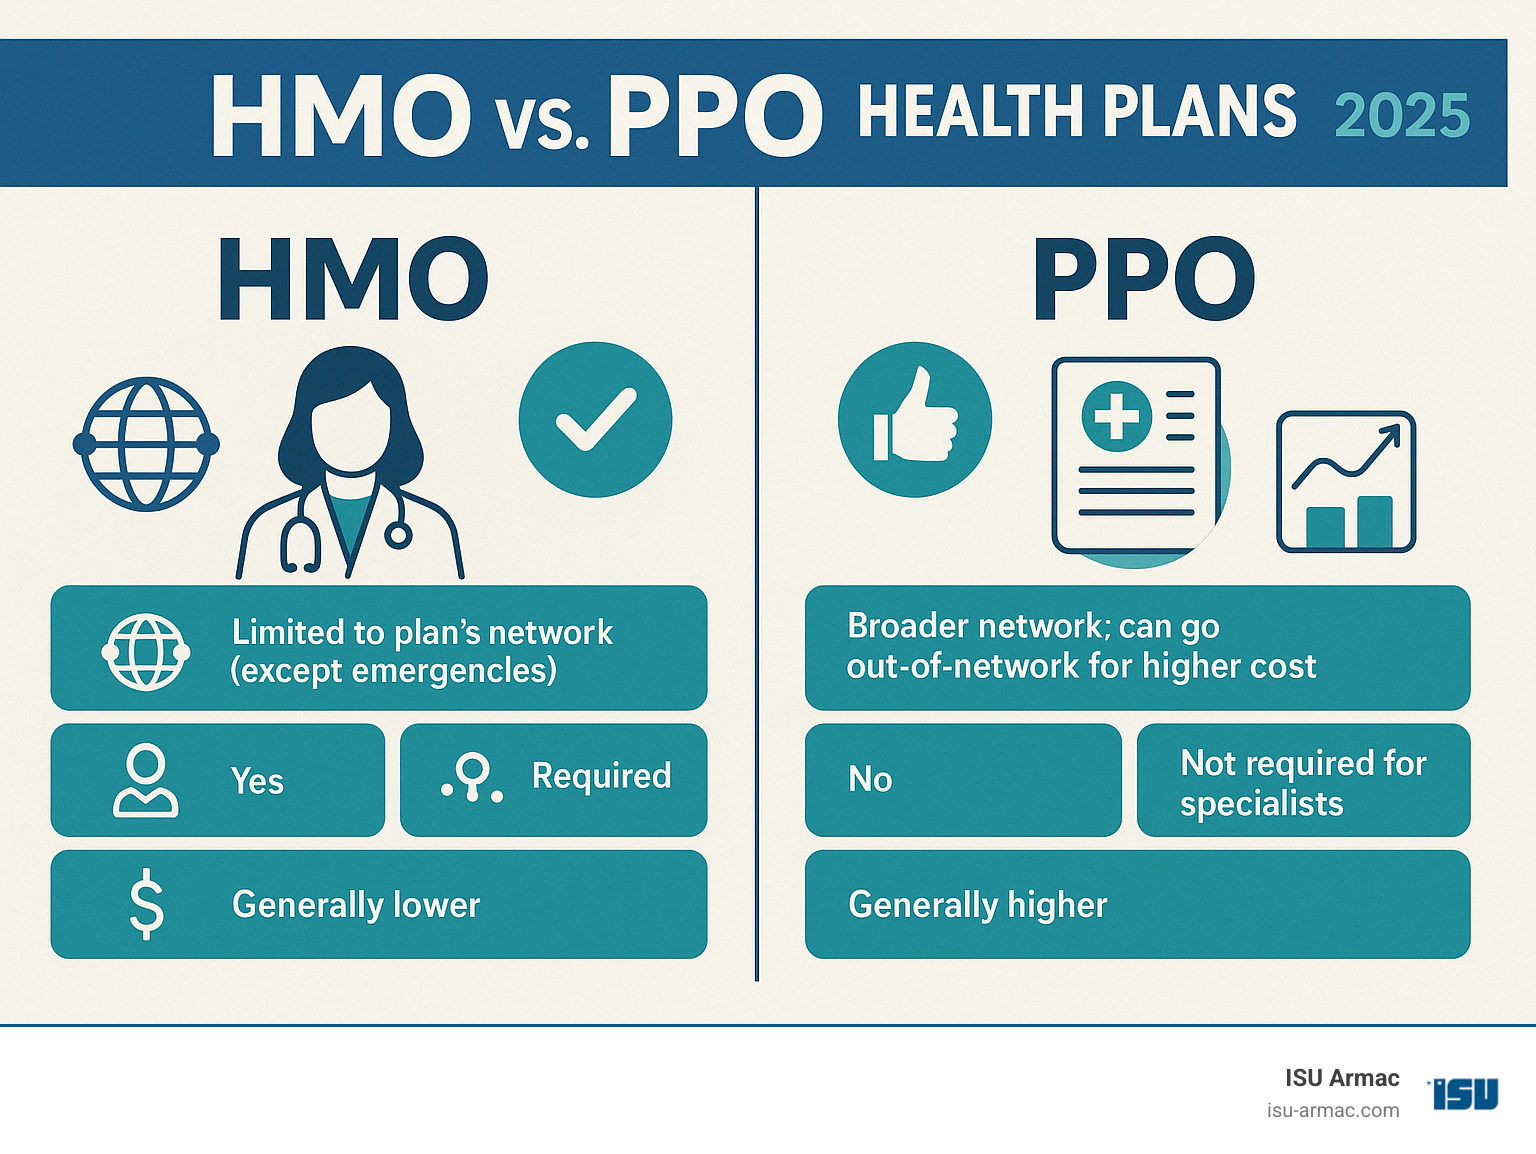
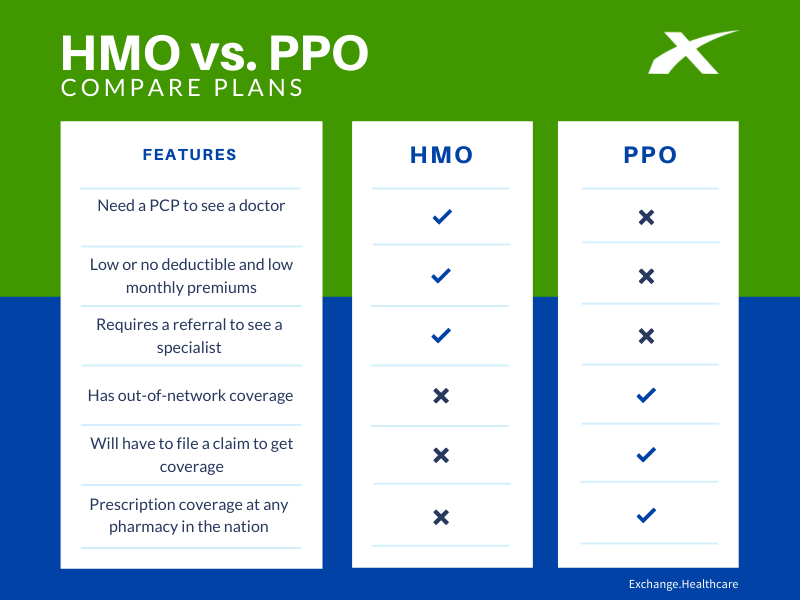
An HMO (Health Maintenance Organization) operates within a defined network of doctors and hospitals. To receive coverage, you are required to select a primary care physician (PCP) who coordinates all of your care. If you need a specialist, your PCP must provide a referral first. This structured approach keeps costs predictable and encourages preventive care, which benefits everyday life by ensuring health issues are caught early.
A PPO (Preferred Provider Organization) gives you far more freedom in choosing healthcare providers. You do not need a primary care physician or referrals to see specialists, and you can even receive coverage — though at a reduced rate — when visiting out-of-network doctors. This flexibility is invaluable for people who travel frequently or have established relationships with specialists.
Must Read
Consider a scenario: Sarah chooses an HMO because she stays in one city, sees the same doctor regularly, and wants to keep premiums and copays as low as possible. Meanwhile, John travels for work and frequently visits new cities, so he prefers a PPO for the ability to find care anywhere without long delays or referral requirements. Both plans protect them — just in different ways.
 PPO Vs HMO Health Insurance: Which Plan Suits You Better?
Cost is another key difference. HMO plans typically feature lower monthly premiums and smaller copays, but their coverage outside the network is usually nonexistent. PPO plans charge higher premiums and deductibles, yet they offer broader access and in return justify the extra expense for those who value choice.
To explore which plan suits you, start by comparing your current doctors against each plan’s network. Review your expected medical needs for the year, including any specialist visits. Finally, read the plan documents carefully, paying attention to copays, out-of-pocket maximums, and referral rules before enrolling.