Ever had that moment at the coffee shop when you tap your credit card and think, "I'll pay this next month, no problem"? We've all been there. But here is where the magic (or the trickery) happens: APR.
So, What Exactly Is APR?
APR stands for Annual Percentage Rate, and it is basically the yearly cost of borrowing money on your credit card. Think of it as the price tag on your debt. The higher the APR, the more interest sneaks onto your balance while you sleep.
Imagine lending your buddy twenty bucks and asking for an extra ten dollars a year. That would feel weird, right? Credit cards do something similar with your balance when you don't pay in full.
Must Read
How Much APR Is Considered Good?
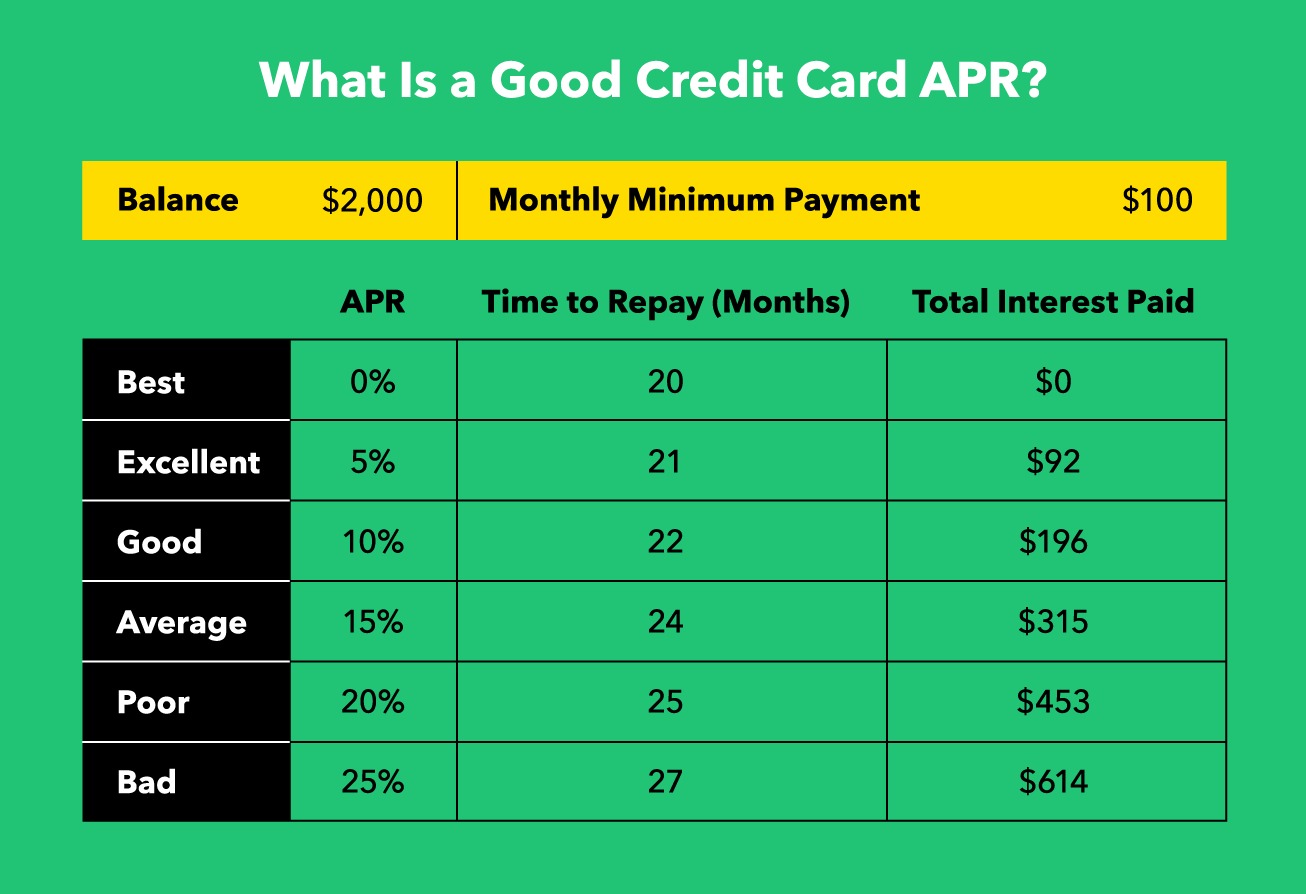
Here is the sweet news: a good APR for a credit card usually falls somewhere between 10% and 15%. Some cards even offer 0% introductory APR for the first year or so, which is like getting a free loan on your latest gadget purchase.
Anything above 20% starts getting expensive fast. For context, most credit cards in the US currently hover around the 20% to 28% range, which caught a lot of people off guard when rates went up recently.
Rewards cards and travel cards often carry higher APRs than plain basic cards, but you might earn points or cash back. It is a trade off: more perks or less interest, depending on how you use the card.
 Credit Cards - The Penny Hoarder
The APR Use Case Matters More Than the Number
If you pay off your balance every single month, you never pay interest anyway, and APR becomes irrelevant. The real question is how honest you are with yourself about your spending habit.
Here is a little story: my cousin once proudly showed me her travel rewards card with an 18% APR. Two months later, she carried a $3,000 balance on it and the free vacation suddenly didn't feel so free.
On the flip side, a friend who always pays in full loves her 24% APR rewards card. 0% and 24% behave the same when you never carry a balance past the due date.
 Understanding APRs on a credit card and it's types - Bright
What Should You Actually Look For?
If you carry a balance, hunt for a card with a low APR, ideally below 15%, or even a 0% intro offer. Negotiate with your bank if possible, because sometimes the constant squeaky wheel does get a better rate.
If you pay in full every month, focus instead on the rewards, perks, and fees. APR becomes your background noise rather than your alarm.
One more tip: read that little disclosure box when you get approved, because the APR can change from time to time according to market conditions. Your rate today is not guaranteed forever.
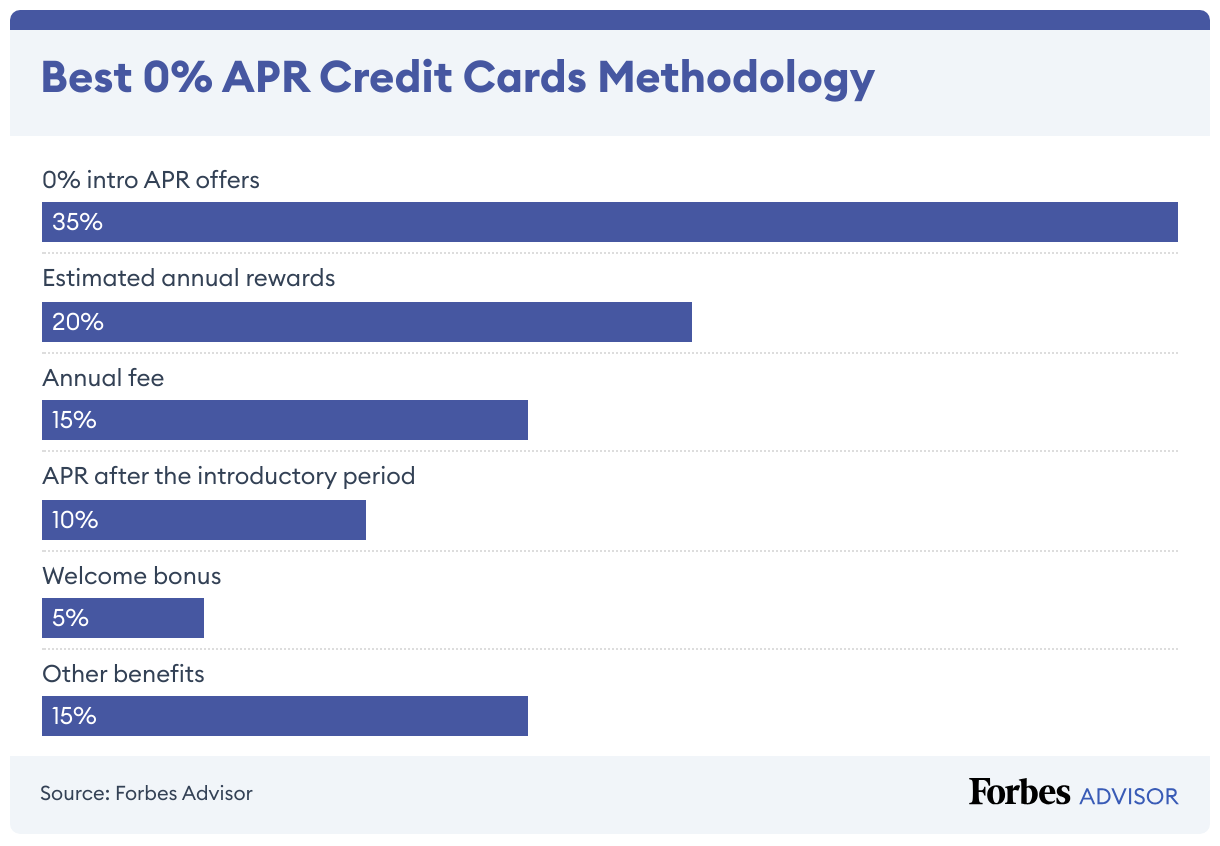 Best 0% APR Credit Cards Of December 2024 – Forbes Advisor
The Bottom Line
The best APR depends entirely on your personal money story. A card with a low APR works beautifully for someone rebuilding their balance, while a high-APR rewards card makes sense for disciplined pay-in-full users.
At the end of the day, understanding your APR is like knowing the rules of the road before you go for a drive. It keeps you out of surprises and puts you in the driver's seat of your finances.
So next time you swipe that card, pause and ask yourself: what borrowed cost am I really signing up for today? A little awareness goes a long way toward keeping your wallet happy.