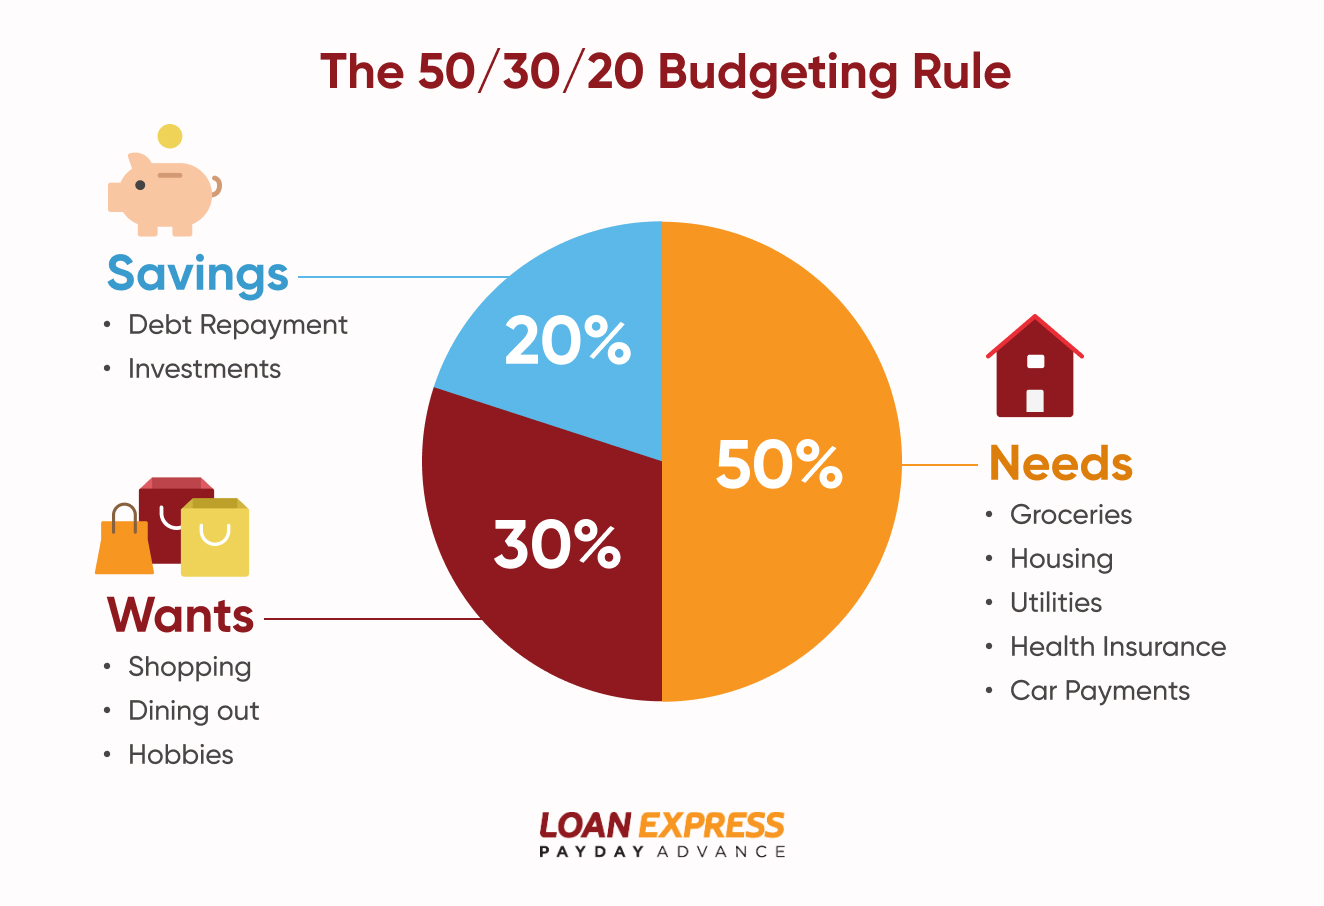
The 50‑30‑20 rule has become one of the most talked‑about budgeting shortcuts in recent years. From personal finance blogs to household chats, people love how simple it is to remember and how flexible it feels when life gets busy.
Why does it matter? Splitting income into needs (50 %), wants (30 %), and savings (20 %) gives families a clear roadmap. It helps individuals avoid the “where did my money go?” spiral, builds emergency funds, and even strengthens community savings clubs when everyone follows the same pattern.
Take Maya, a freelance graphic designer. She earns $4,000 a month. By setting aside $1,200 for rent, $1,200 for groceries and utilities, $400 for fun, and $600 for her retirement fund, she finds she can enjoy a night out without guilt, knowing her savings are growing.
Must Read
Consider a couple with two kids. Their combined paycheck of $6,000 is split into $3,000 for housing, $1,800 for school fees and food, $600 for family outings, and $1,200 saved for vacations. The rule keeps the household steady even when one partner loses a part‑time job.
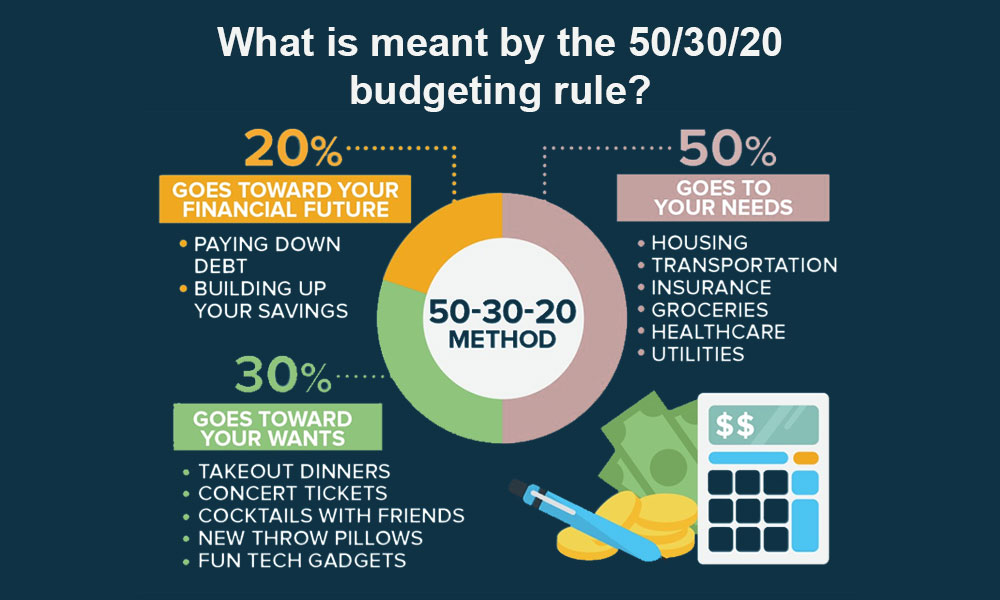 Smart Budget Bhutan
Practical tips? First, calculate your after‑tax income. Second, list fixed bills to see if you’re anywhere near the 50 % mark. Third, track discretionary spending with a simple app and adjust the 30 % slice if you notice “wants” creeping up. Finally, automate transfers to a savings account so the 20 % is locked in before you spend.
In short, the 50‑30‑20 rule stays relevant because it turns a complex financial puzzle into an easy, repeatable habit. Embrace it, tweak it to fit your life, and watch your money work for you.