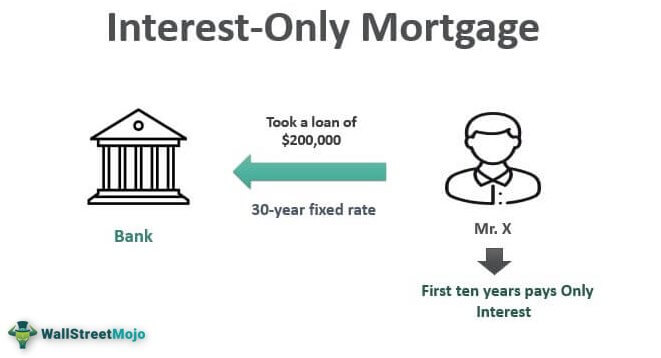
Ever dreamed of owning a home without the heavy monthly burden? An interest-only mortgage loan might just be your golden ticket. This creative financing option lets you pay only the interest on your loan for a set period, giving you breathing room in your budget while still building your dream life.
How does it work? Instead of paying both interest and the loan balance each month, you cover only the interest portion during the initial period—usually 5 to 10 years. After that, you begin paying off the principal as well. This structure keeps early payments significantly lower, freeing up cash for other goals like travel, education, or home improvements.
The advantages are hard to ignore. Lower monthly payments mean greater cash flow flexibility. If you're a young professional expecting higher earnings later, or a savvy investor redirecting savings into growing assets, this loan gives you a strategic edge. It's perfect for anyone who needs temporary financial relief without sacrificing homeownership.
Must Read
Imagine Sarah, a freelance designer who earns variable income. She chose an interest-only mortgage to keep payments manageable during slow months while routing her surplus toward building an emergency fund. Or consider Tom, a real estate investor who benefits from minimal immediate costs, allowing him to purchase a property and renovate it before his repayment phase begins.
 What is an Interest-Only Mortgage? Your 2026 Guide - EHF Mortgages
Practical tips: First, always have an exit strategy—know exactly when you'll start paying principal. Second, compare rates across lenders, as interest-only loans can carry slightly higher interest. Third, ensure your income is secure enough to handle larger payments later. Finally, build a solid budget so you can save extra during the interest-only period.
While interest-only loans require discipline, they offer an exciting opportunity to manage money smartly. With careful planning and the right lender, you could enjoy the home you love today while preparing confidently for tomorrow.