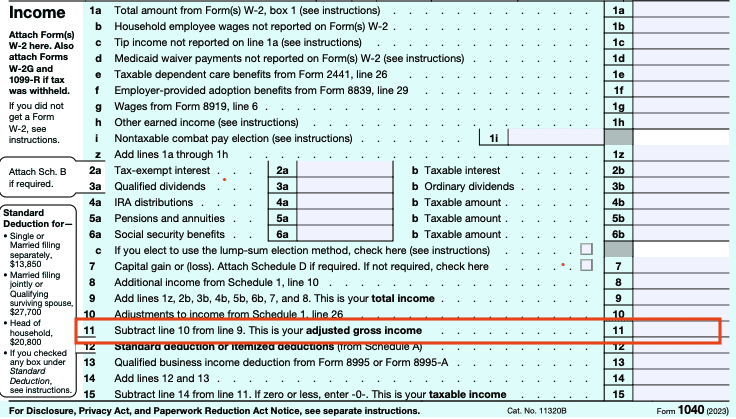
Okay, so you're staring at your Form 1040 and there it is — Adjusted Gross Income. You probably squint, whisper "AGI what now?", and maybe silently panic. Don't worry, friend. We've all been there. Let's break it down together like two buddies over coffee.
Adjusted Gross Income, or AGI, is essentially your total income minus certain deductions before we get into the bigger tax breaks. It's found right after you total up your wages, tips, and other goodies — then you subtract things like IRA contributions, student loan interest, and health savings account payments. Think of it as your income's glow-up: still messy, but a little more refined.
Why does it matter? Oh, it matters a lot. Your AGI determines whether you qualify for credits, deductions, and even certain tax loopholes. It also influences how much of your Social Security benefits are taxable. Basically, AGI is the gatekeeper deciding how much of your money gets to stay in your wallet — and how much waves goodbye to Uncle Sam.
Must Read
Here's a fun little tip: lower your AGI, open doors to more tax breaks. How? Max out your retirement contributions, deduct medical expenses if possible, and keep those miscellaneous deductions in check. It's like playing financial Tetris — fitting pieces just right can score you major points.
 PPT - Federal 1040 Overview PowerPoint Presentation, free download - ID
So next time April rolls around and you see AGI on your 1040, don't sweat it. You've got the inside scoop now. You're basically a tax-savvy rockstar without even trying.
Remember: taxes may feel overwhelming, but every financial goal starts with understanding the basics. You've already taken the first step, and that's worth celebrating. Here's to smarter money moves and a brighter future — you've got this!

