
So you've probably heard someone at a coffee shop or dinner party say, "I maxed out my Roth IRA." And you quietly wondered what on earth they were talking about while pretending you totally knew. Don't worry — you're about to become the person everyone leans in to listen to.
First, What Is an IRA Anyway?
IRA stands for Individual Retirement Account. Think of it as a special savings account that the government really wants you to open because retirement is kind of important. The two big flavors are the Traditional IRA and the Roth IRA.
Both let you tuck away money and invest it in things like stocks and bonds. The magic difference? When you get to enjoy the tax break — now or later.
Must Read
The Traditional IRA: The "Pay Me Later" Deal
Imagine you're at a checkout, and the cashier says, "Put this on your tab for later." That's basically the Traditional IRA. You contribute money now and get a tax deduction today, which lowers what you owe to Uncle Sam.
Here's a fun little story. My friend Dave had $6,000 in income he earned last year. He put that $6,000 into a Traditional IRA and instantly saved around $1,300 in taxes — that's like a missing receipt giving him free cash back.
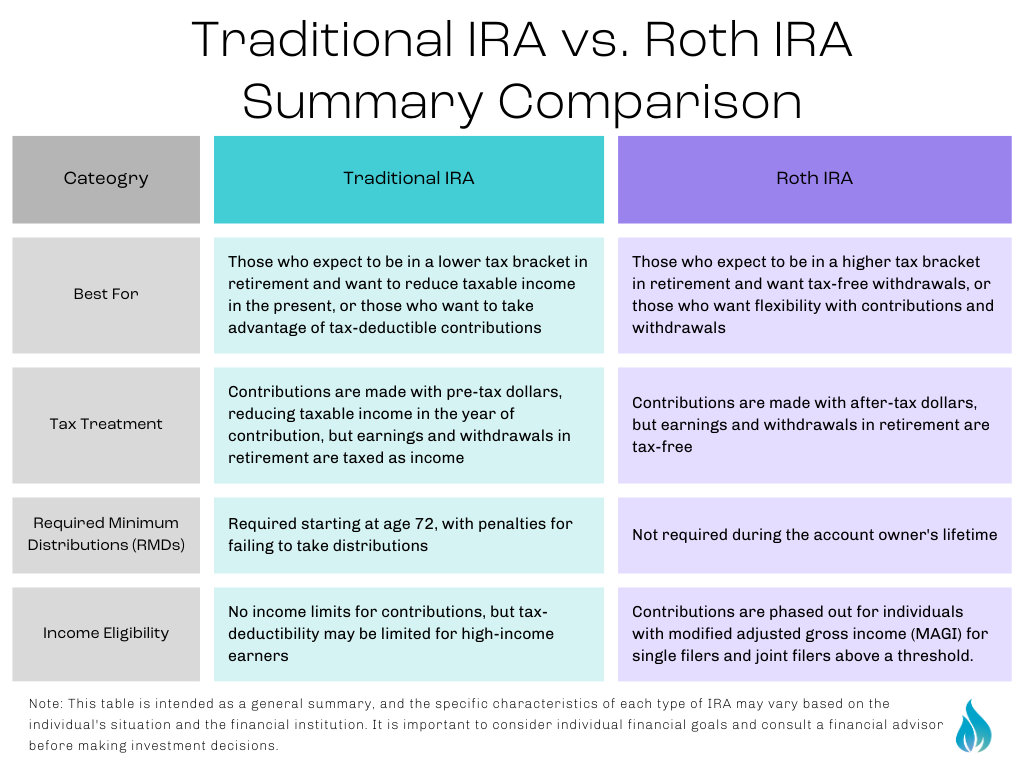 Finance 101: Roth IRA vs. Traditional IRA: A Comprehensive Guide to
But there's a catch, like a "free" vacation that charges resort fees. When Dave retires and pulls the money out, every penny is taxed as ordinary income. The money grows tax-deferred, but the bill still comes due eventually.
The Roth IRA: The "Pay Me Now, Play Me Now" Deal
The Roth IRA flips the script entirely. You pay taxes before the money goes in, so no tax break today. But here's the party trick: all your future withdrawals in retirement are completely tax-free.
This is where people get really excited. Imagine your $6,000 grows into $300,000 by retirement — that means $300,000 comes out with zero taxes attached. That's like finding a coupon for your entire grocery bill twenty years from now.
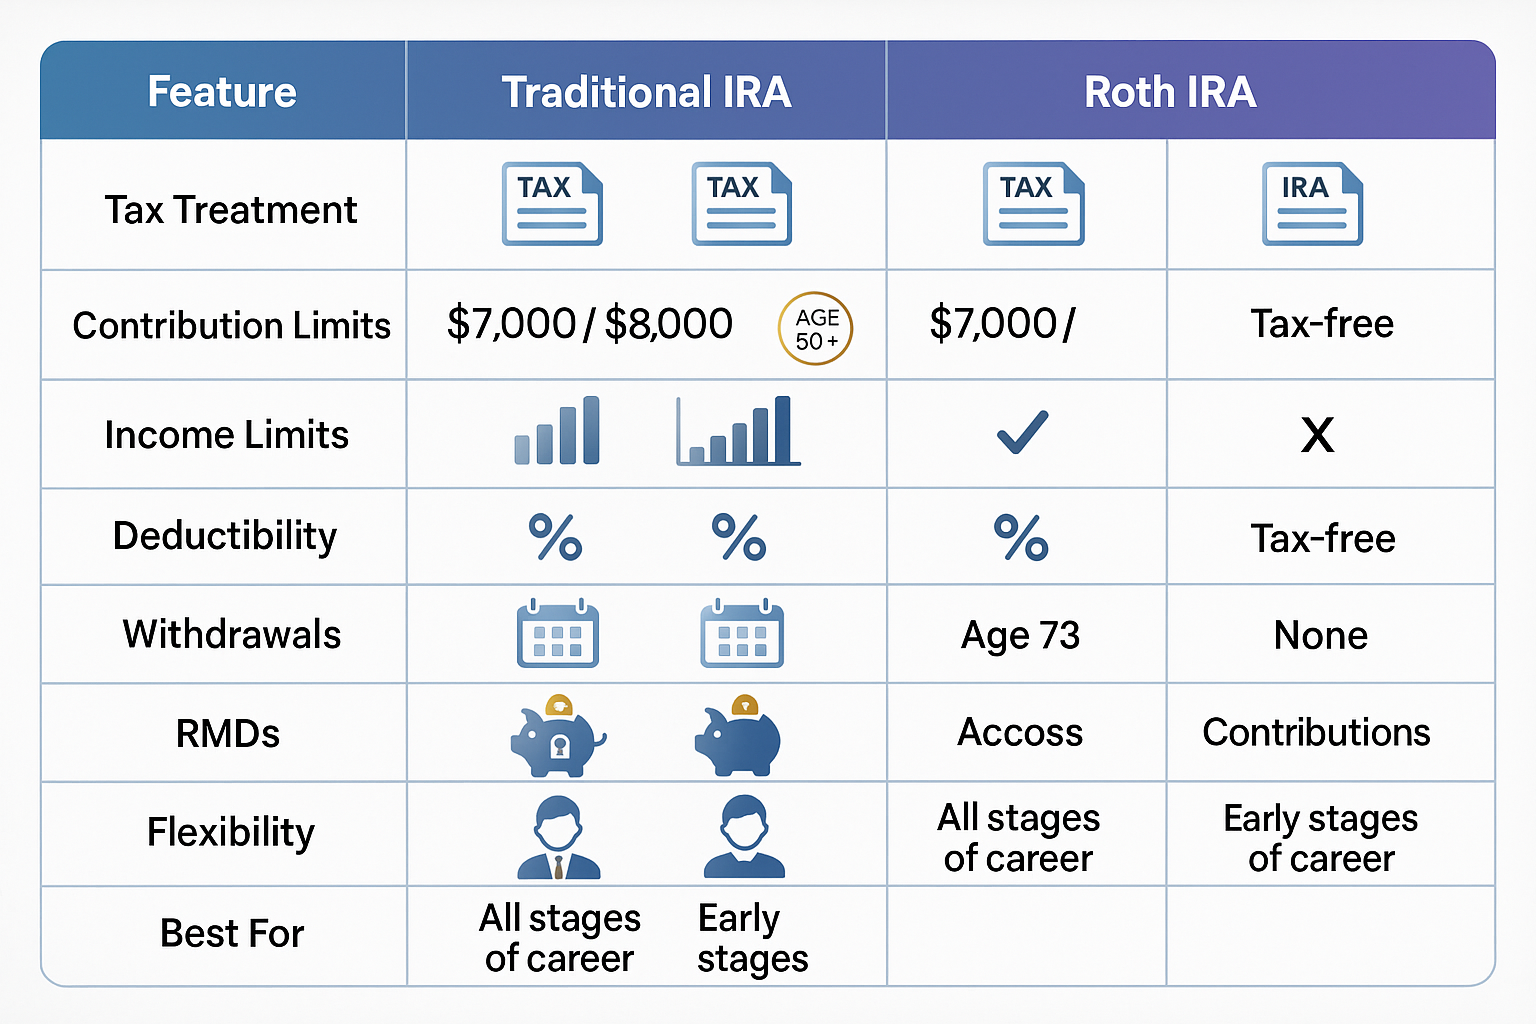 Roth IRA vs Traditional IRA: Which Is Better for Retirement? - The Rich
Sounds too good to be true, right? Well, there are income limits — if you earn too much, you can't contribute directly. And you can't take out your contributions' growth until age 59½ without penalties.
Roth vs. Traditional: Which One Fits You?
Here's a simple way to think about it. If you believe your tax rate will be higher in retirement, the Roth IRA is your best friend. If you think taxes might be lower when you're sipping lemonade on a porch, the Traditional IRA gives you the advantage now.
Another angle? If you're young and just starting your career, you're probably in a lower tax bracket. That makes the Roth particularly appealing — you lock in cheap taxes now while your income grows later.
 Roth IRA vs Traditional IRA: Which Is Better?
Some ambitious savers actually use both accounts. It's like ordering soup and salad — why choose just one when diversifying your entire meal makes so much sense?
Why Should You Care? Simple: Retirement Won't Fund Itself
Here's the sobering truth — Social Security alone probably won't cover your golden years comfortably. Starting any IRA, whether Roth or Traditional, is one of the easiest wins in personal finance. The government essentially hands you tax advantages because they'd rather reward you for saving than bail you out later.
Think of it this way: every contribution you make today is a quiet thank-you note from your future self. So whether you pay taxes now with the Roth or later with the Traditional, the real win is simply starting. Your future lemonade lemonade stands will thank you.