
Ever stumble across the term hard inquiry on your credit report and wonder what in the world it means? You're not alone. Let's break it down in the chillest way possible.
Imagine your credit report is like a diary of your financial life. Every time a lender peeks into your diary, they leave a little mark. That mark? That's a hard inquiry.
So, What's a Hard Inquiry Exactly?
A hard inquiry happens when a lender or creditor formally checks your credit to decide whether to lend you money. Think of it like a job interview — they're sizing you up before making an offer. This usually occurs when you apply for a credit card, mortgage, auto loan, or personal loan.
Must Read
Here's the thing: once it's logged on your report, it stays there for about two years. Don't panic though — most models stop counting it against you after just one year. So it's more like a temporary bruise than a permanent scar.
Hard Inquiry vs. Soft Inquiry — What's the Diff?
Great question! A soft inquiry is basically a casual peek — like when you check your own credit or a lender pre-approves you for an offer. No harm done, no score drop.
 Does Checking Your Credit Score Lower It?
A hard inquiry, on the other hand, is the real deal. It can nudge your credit score down by a few points, usually somewhere between 5 to 10 points. Not devastating, but still worth knowing about.
Why Would You Ever Want One?
Because sometimes you need one! Without hard inquiries, it would be chaos — lenders couldn't figure out if you're a responsible borrower or a high-risk ghost. Think of it as an honest handshake between you and the bank.
And if you're shopping around for a mortgage or car loan within a short window, multiple inquiries often count as just one. That's called rate shopping, and credit scoring systems are surprisingly cool about it.
 Hard Inquiry - What Is It, How To Dispute It, Vs Soft Inquiry
Is a Hard Inquiry a Bad Thing?
Not really — it's just part of life. You applied for a loan, a lender checked you out, and they scribbled a note. Done.
Could too many hard inquiries in a short time raise a red flag? Absolutely. But unless you're applying for ten credit cards in a week, you're probably fine.
Can You Remove a Hard Inquiry?
If you spot one you didn't authorize, you can dispute it. Hit up the credit bureaus and they'll investigate — just like returning a sweater you never bought.
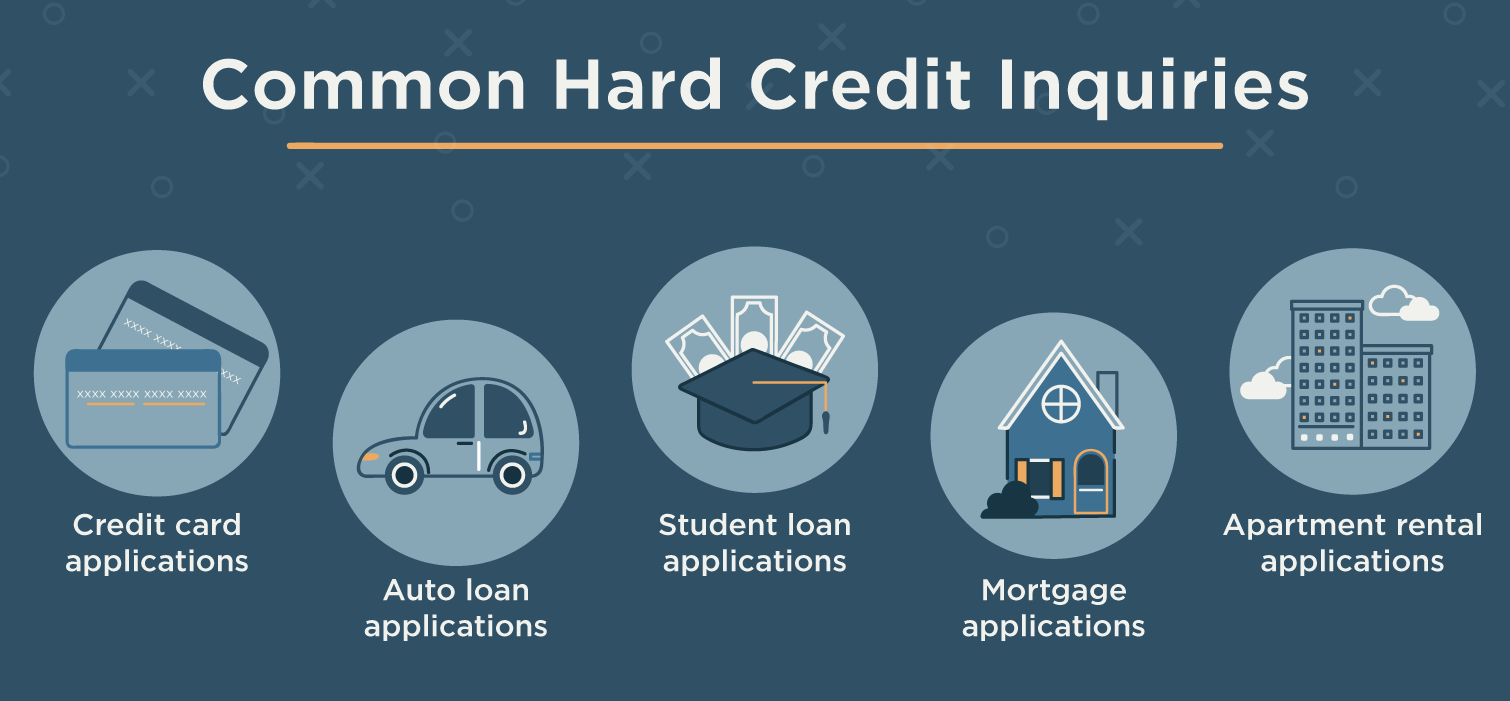 What is a hard inquiry? - Lexington Law
If the lender can't prove they got your permission, that inquiry vanishes. Pretty neat, right?
The Bottom Line
A hard inquiry is really just a snapshot moment — a lender taking a closer look at your credit story. It's normal, it happens, and it doesn't define your financial identity forever.
So next time you see one pop up on your report, don't sweat it. Take a deep breath, keep applying for credit as needed, and let your positive payment history do the heavy lifting. Your credit is more of a marathon than a sprint anyway!