One of the easiest ways to keep your money safe while it grows is a bank CD. This simple financial tool is popular because it’s both straightforward and reliable, making it a go‑to option for anyone who prefers a steady, predictable return over chasing high‑risk investments. Whether you’re saving for a vacation, building an emergency fund, or just looking for a place to park cash, a CD offers a clear, stress‑free path.
A certificate of deposit is essentially a loan you give to a bank for a set period. You choose a term—ranging from a few months to several years—deposit a lump sum, and the bank pays you fixed interest on that amount. When the term ends, you get your original deposit plus the interest, giving you a transparent picture of what you’ll earn.
How it works is pretty simple: you select a CD term, lock in the funds, and then watch the interest accrue daily or monthly. At maturity, the bank automatically rolls the balance into a new CD at the current rate unless you decide otherwise. If you cash out early, you’ll usually face an early‑withdrawal penalty, which can reduce the interest you’ve already earned.
Must Read
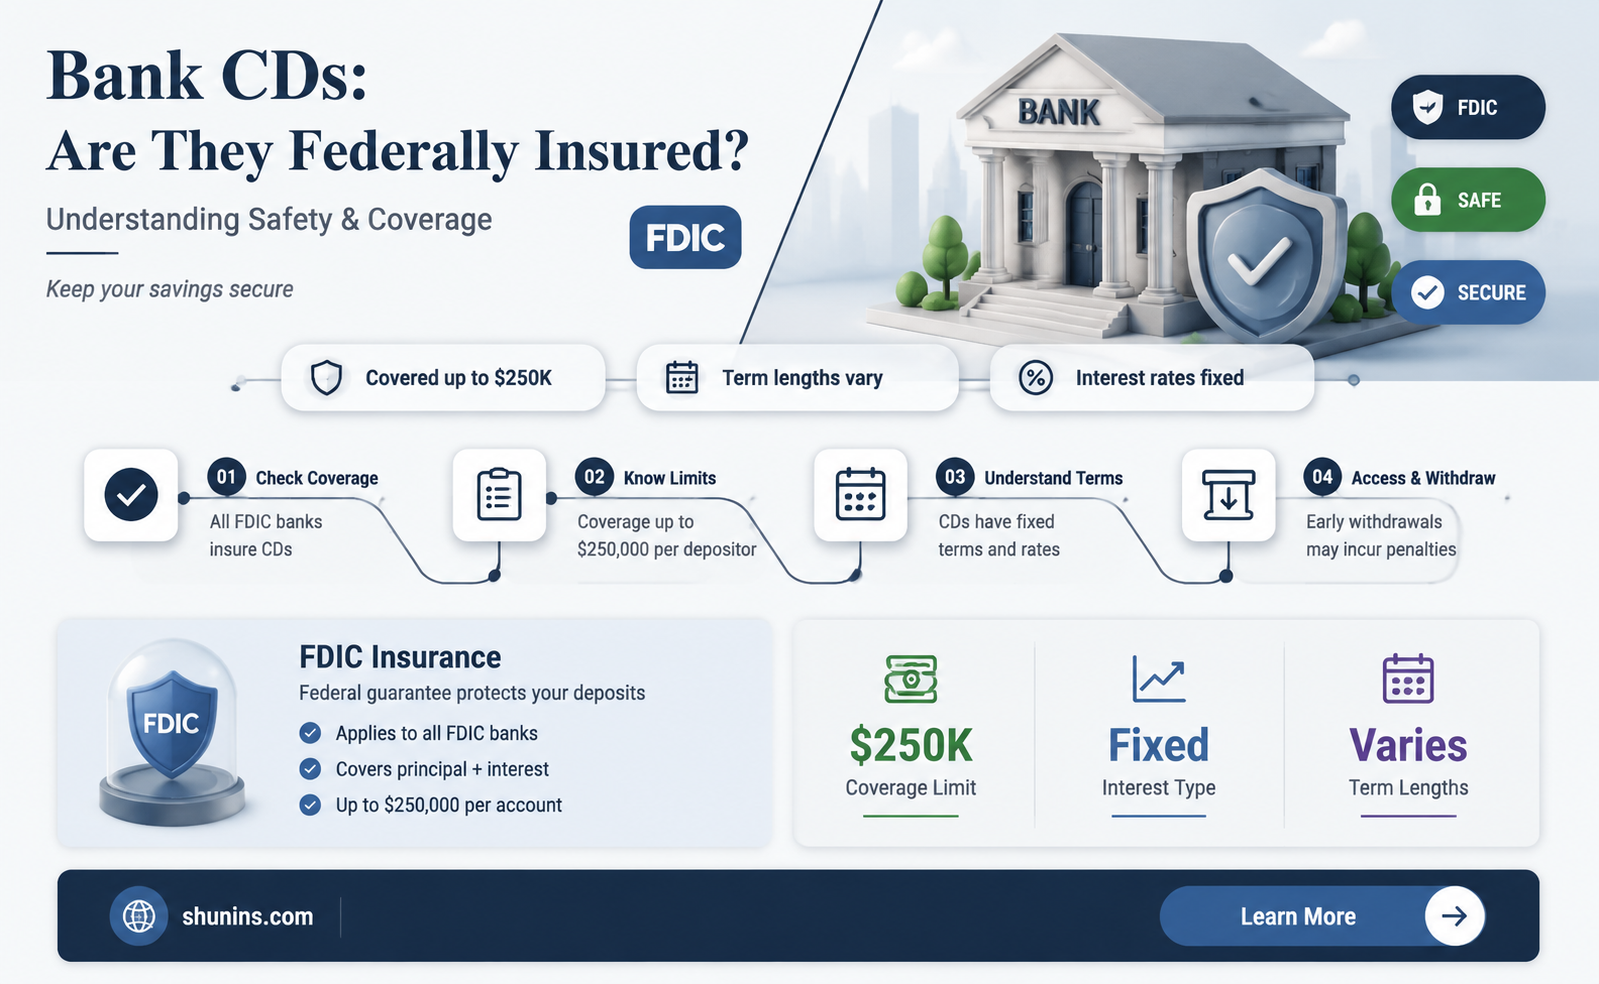
The main draw for most people is safety and predictability. Because the rate is guaranteed for the entire term, you can plan expenses and savings goals with confidence. Many banks also insure CDs up to $250,000 per depositor, adding an extra layer of security that’s especially appealing when the stock market gets volatile.
 How CD Accounts Work: Secure Savings With Fixed Interest
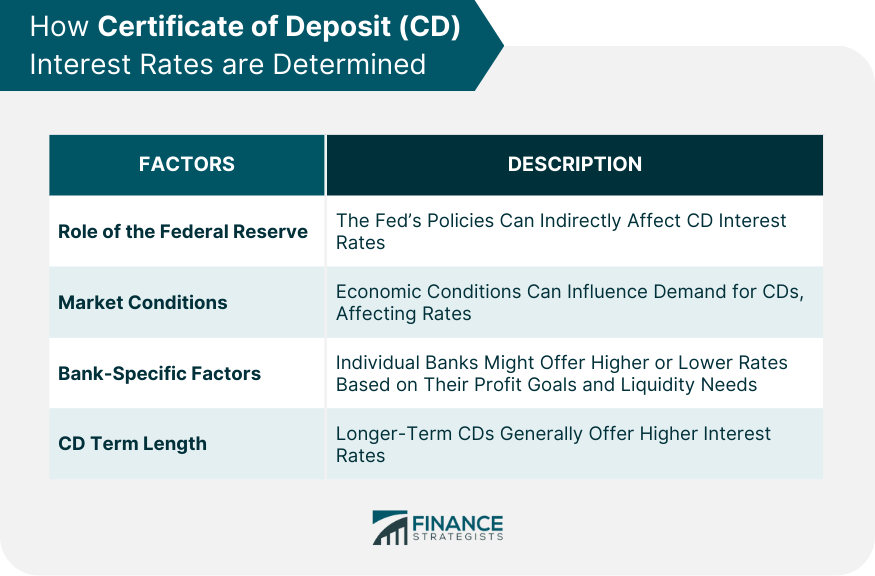
There are a few common variations you’ll encounter. Fixed‑rate CDs keep the same rate for the whole term, while variable‑rate CDs may adjust when the bank changes its benchmark rates. Step‑up CDs increase the interest rate at predetermined intervals, and no‑penalty CDs let you withdraw without a fee if you meet certain conditions.
Getting started is easy: shop around online for the best rates, compare term lengths, and read the fine print about penalties. Decide how long you can comfortably leave the money untouched, then open the CD at your preferred bank or credit union. Set a reminder for maturity so you can decide whether to renew, withdraw, or move the cash elsewhere.