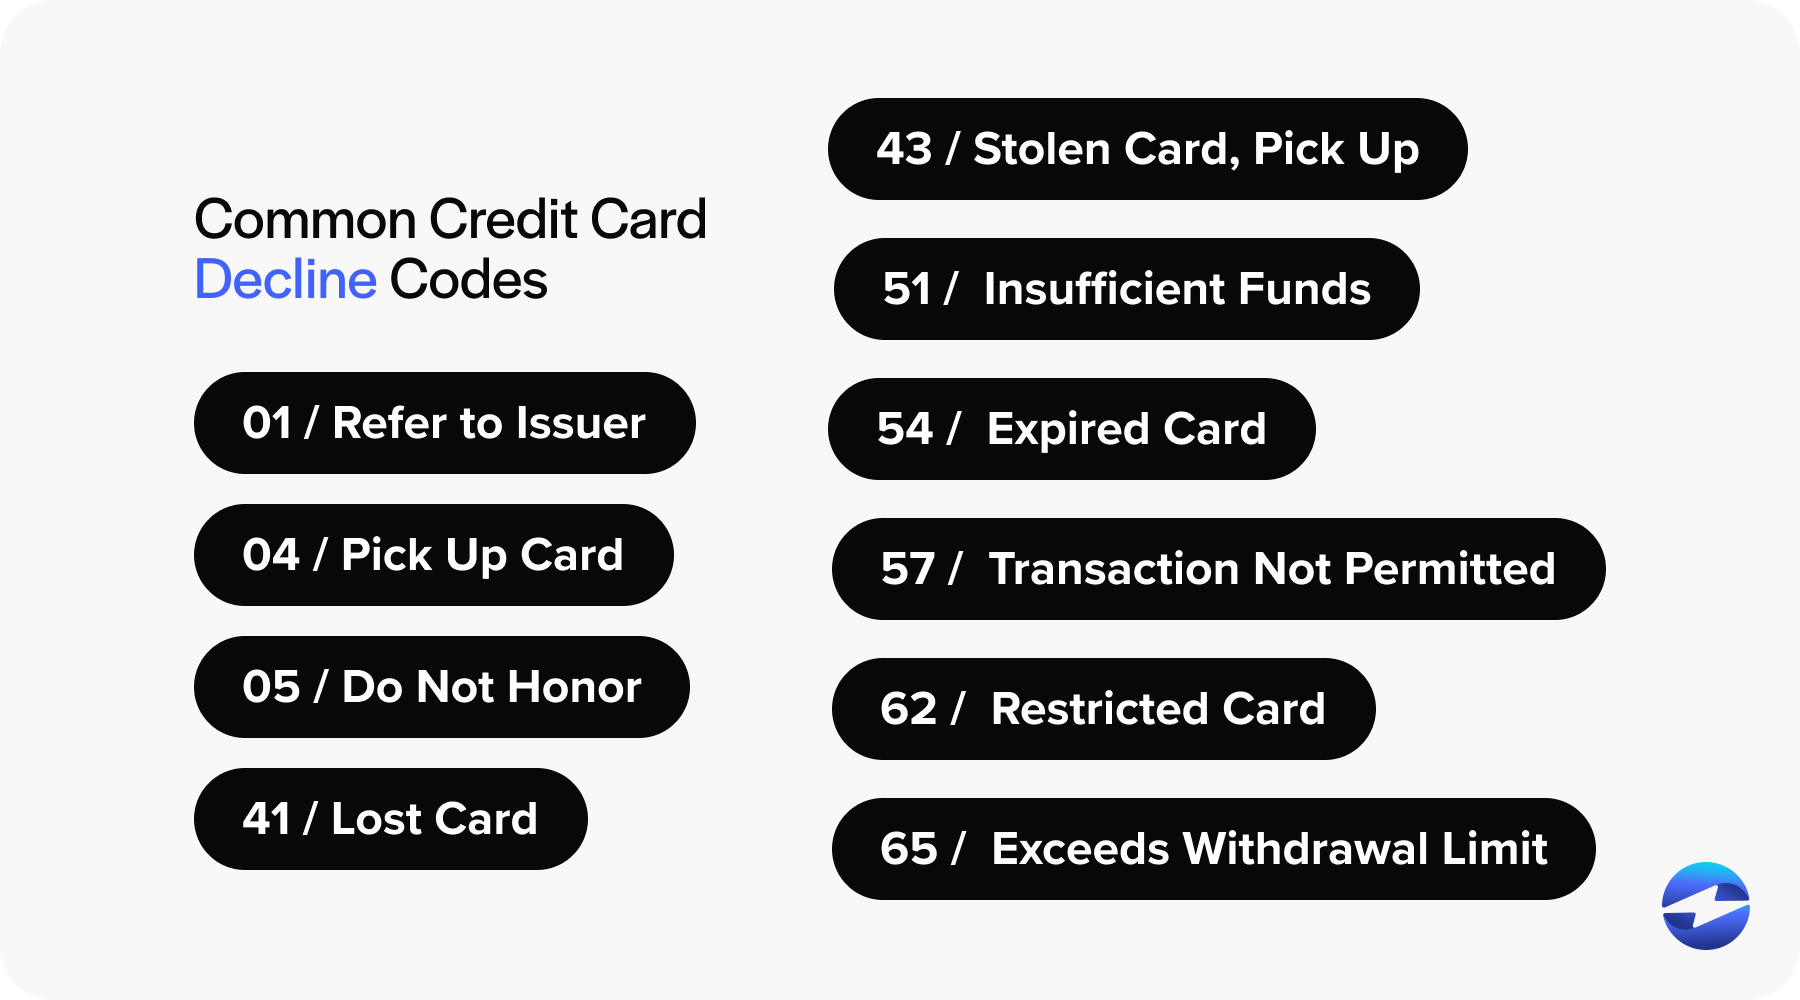
Rarely does a phrase stop a transaction faster than card declined by issuer. This simple message pops up at grocery stores, online shops, and even at ATMs, making it one of the most recognizable alerts in everyday payments. It’s popular not because it’s pleasant, but because it instantly signals that something needs a quick check, saving users from long lines or wasted effort.
Understanding this alert matters because it helps individuals avoid unexpected fees, protect their credit scores, and keep budgets on track. For families, a clear decline notice prevents shared card limits from being exceeded, while communities benefit when businesses can process payments smoothly without repeated retries that slow down service.
Imagine you’re buying a laptop online and the checkout flashes declined by issuer. The card might be expired or the bank may have flagged the purchase as risky. Realising this early lets you switch to another payment method instead of waiting for a delayed confirmation email.
Must Read
Another common scenario is a parent using a joint account to pay for a child’s school lunch. If the school’s POS system reports the same alert, the family knows the card’s daily limit has been reached, prompting them to use a backup card or adjust the limit before the next meal.
 Card Declined By Issuer
Practical steps are simple: first, check the card’s expiration date and billing address match. Second, ensure there are enough funds or available credit. Third, try a different card or digital wallet. If problems persist, call the issuer for a quick freeze‑release or to verify any security block.
In short, the phrase card declined by issuer is a handy, low‑key checkpoint that keeps finances safe and transactions flowing. By recognizing its meaning and acting swiftly, anyone can turn a momentary hiccup into a seamless payment experience.