So you've found your dream home. Your heart is racing, your wallet is sweating, and you're ready to buy. Then you hear the words: "Your file is going to underwriting."
And just like that, the mood shifts. It sounds like you're about to be judged by the strictest teacher in school. Spoiler alert: that's exactly what's about to happen.
The Underwriter: Your Financial Detective
An underwriter is basically a financial detective who digs into your money life with a magnifying glass. They want to know if lending you a six-figure loan is smart or if it's about to become a very expensive mistake. Think of them as the person who asks "Are you sure you can afford that avocado toast and a $3,000 mortgage?"
Must Read
They review your income, your debts, your credit score, and even your employment history. Some people feel like they're being interrogated by the FBI. Meanwhile, the underwriter is just doing their best to protect the lender's money.
What They Actually Look At
First up: your credit score. This three-digit number basically tells the underwriter how responsible you've been with money so far. If it's high, the underwriter smiles. If it's low, well, you just became very interesting.
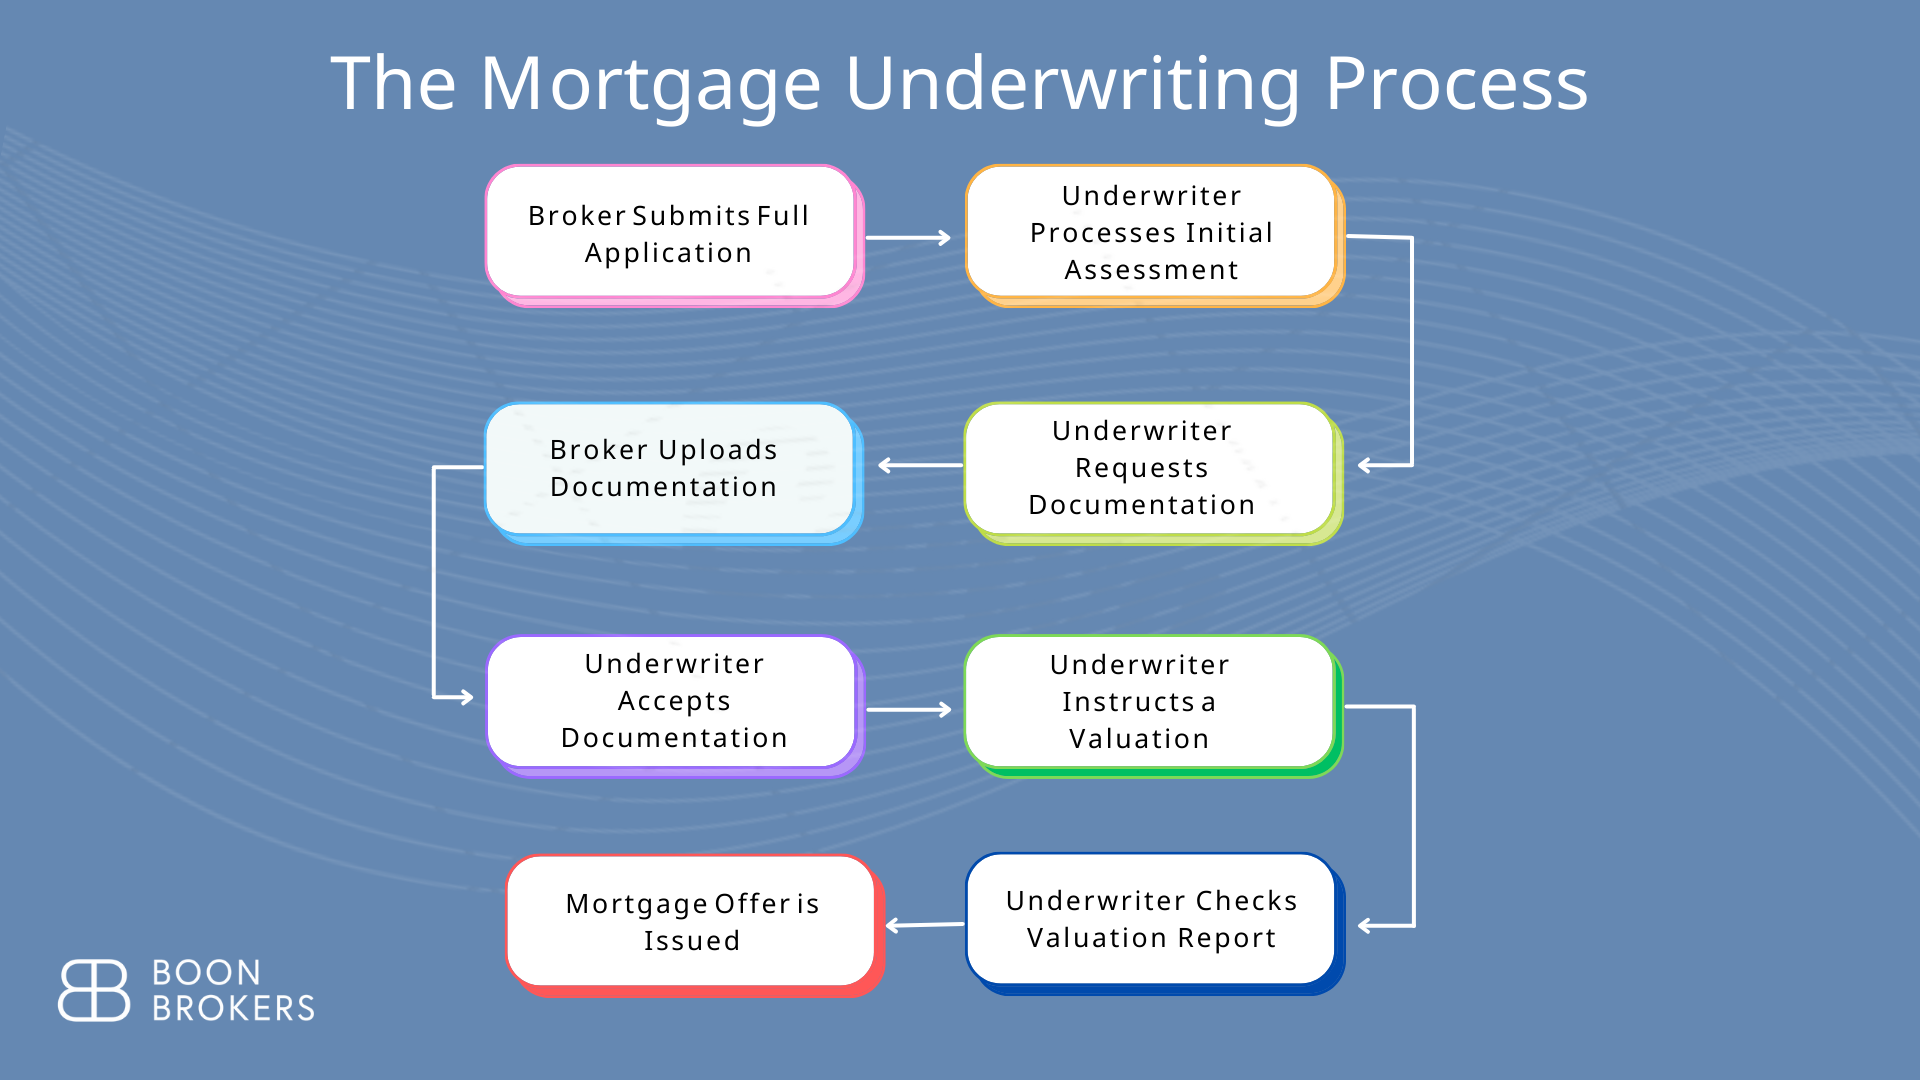
 The Mortgage Underwriting Process: A Comprehensive Guide | Mortgage
Next, they'll scrutinize your income down to the last dollar. They want to know it's stable, consistent, and will cover not just the loan but also pizza nights. Fun fact: the Federal Reserve says the average mortgage payment hit $1,750 per month in 2024 — so yeah, they're thorough for good reason.
They also look at your debt-to-income ratio. This fancy term just means how much of your income is already eaten up by debts. If your numbers look like a math Olympiad gone wrong, the underwriter might push back.
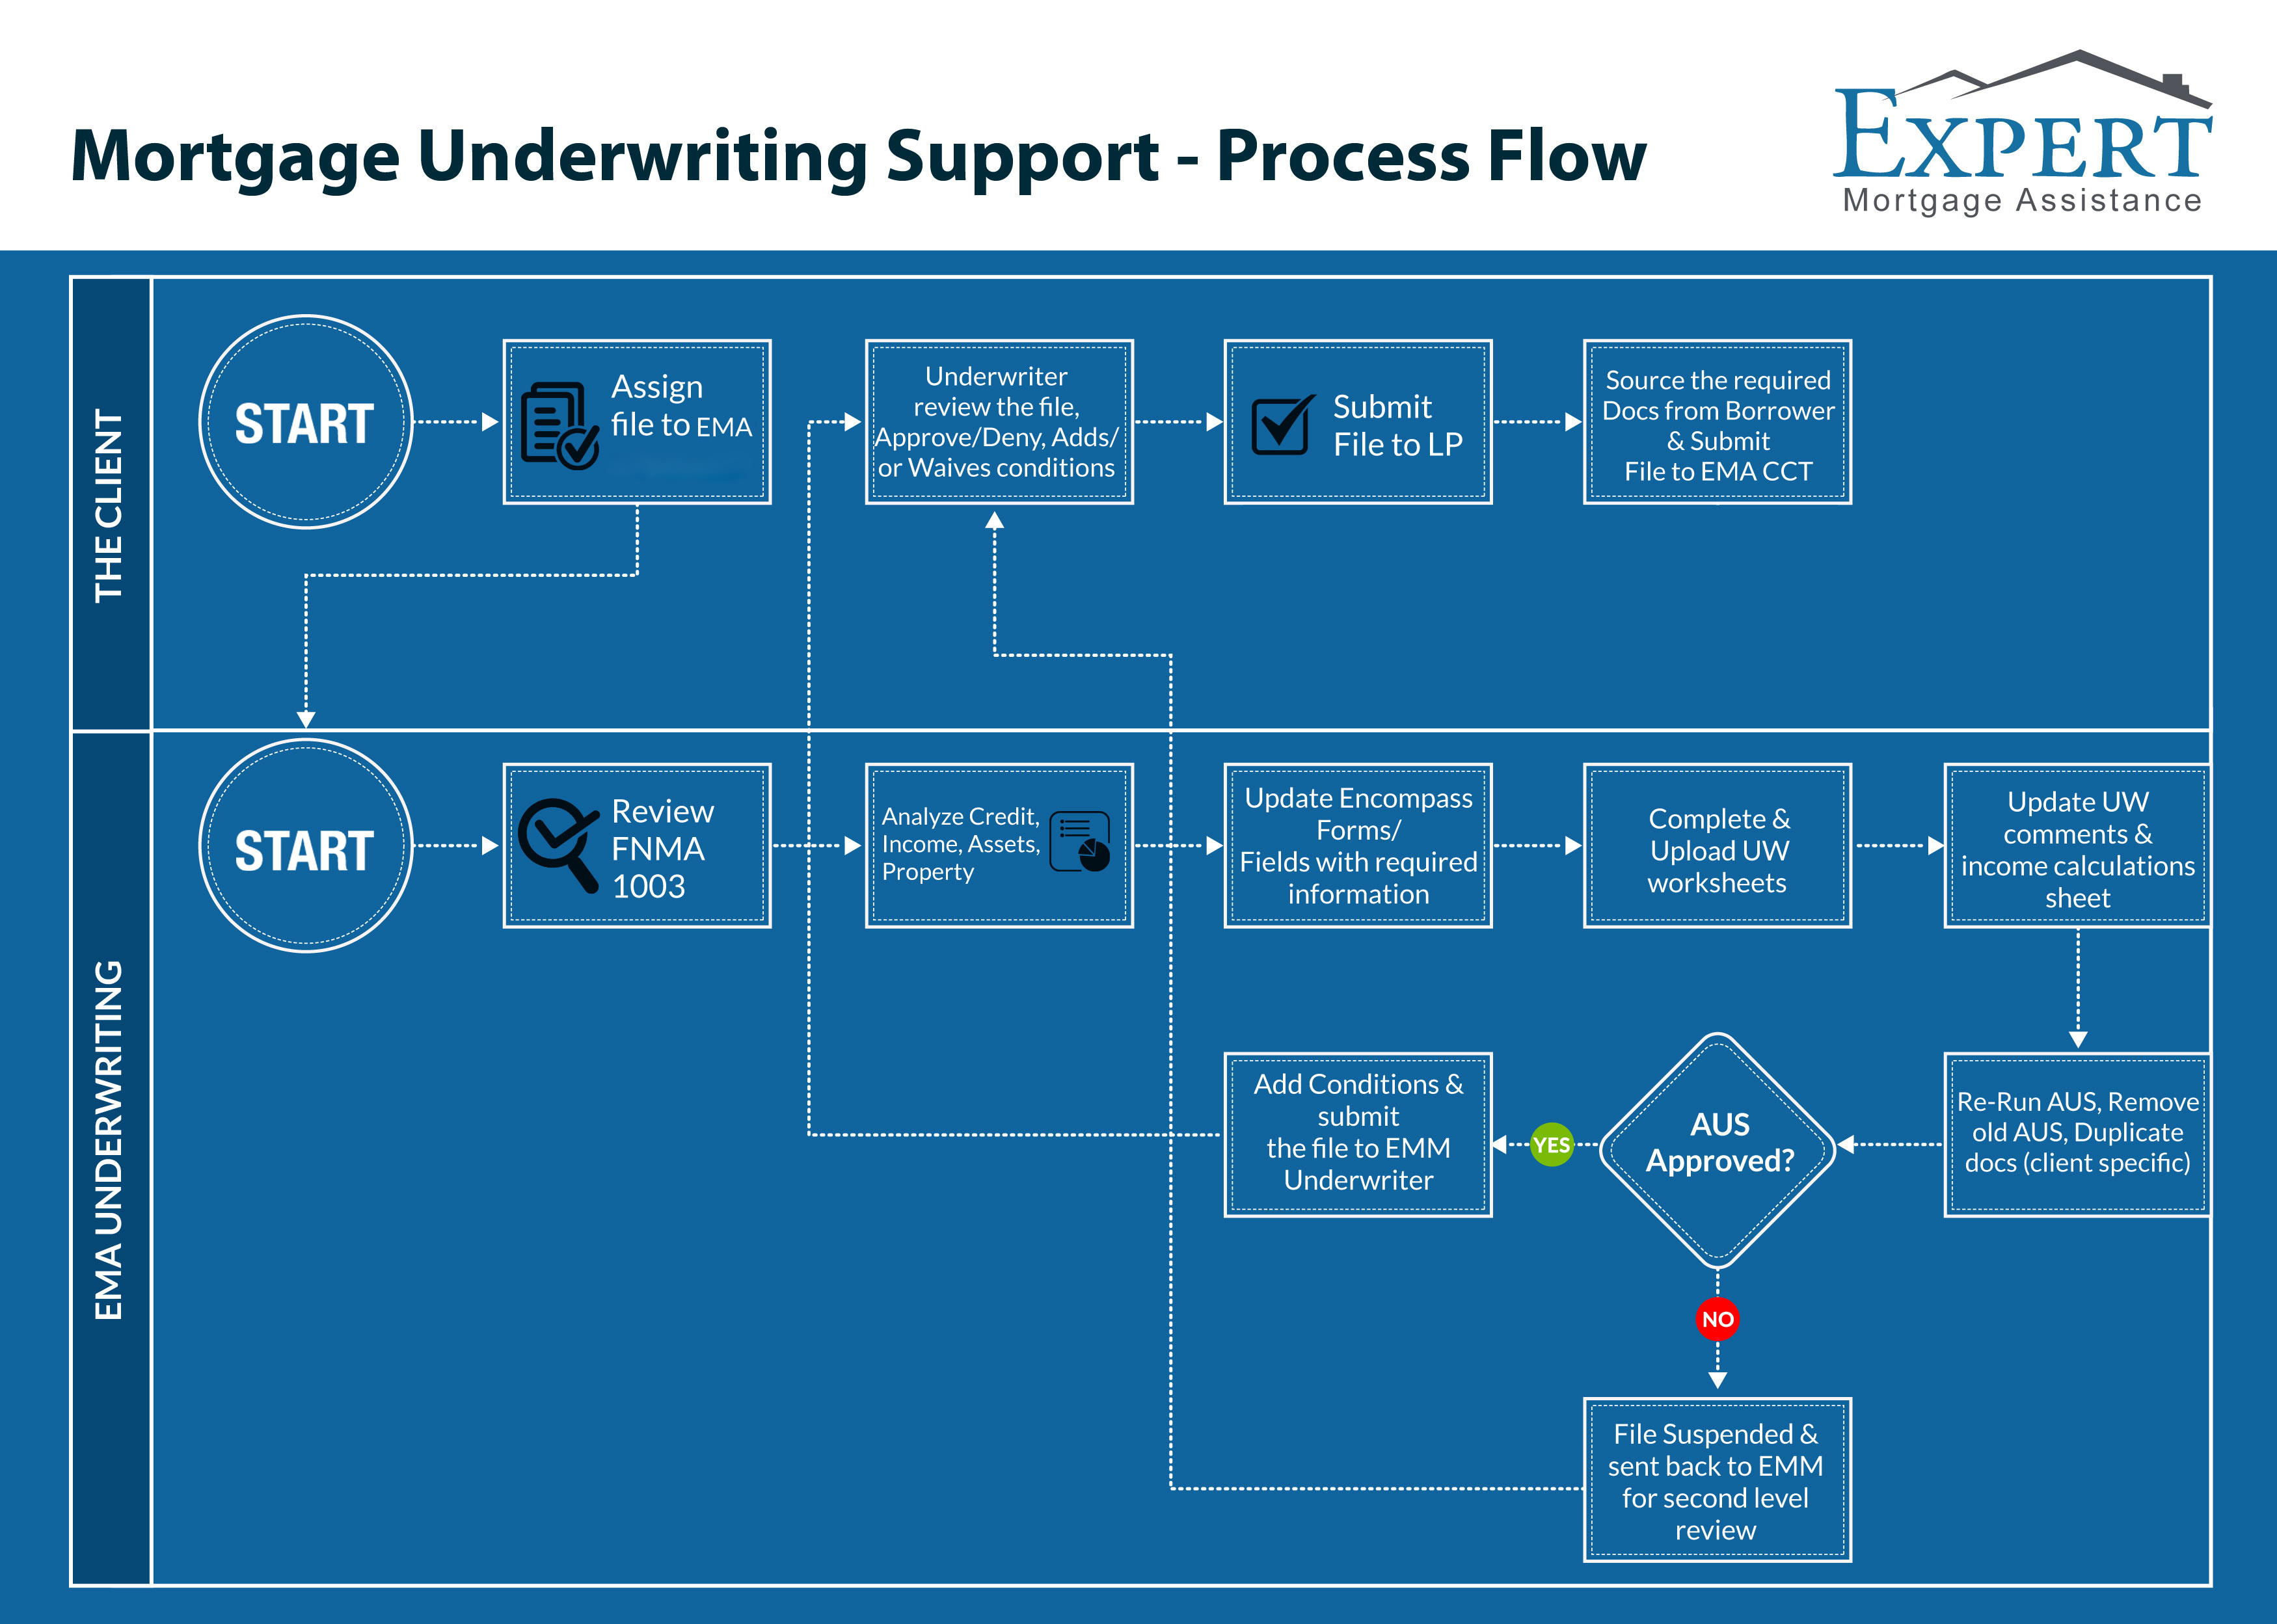 Mortgage Underwriting Process Outsourcing Services in USA
The Process Can Get Dramatic
Underwriting can take anywhere from a few days to several weeks, depending on how complicated your situation is. During this time, they might come back with a list of conditions or questions that seem oddly specific. "Who are these three new credit inquiries fr..."
They might ask you to explain a random $500 deposit from "Grandma Marge." They want to see bank statements, tax returns, and employment letters. If there's a mysterious gap in your employment history, buckle up — they'll want a story, not a shrug.
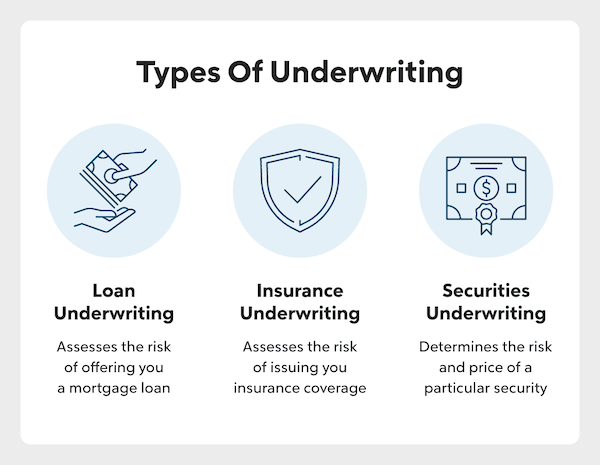 A Complete Guide To The Underwriting Process | Quicken Loans
Surprisingly, underwriters don't just protect the bank — they also protect you. By making sure you can genuinely afford the loan, they prevent a future where you're eating cereal for dinner while staring at a notice of foreclosure. Nobody wants that plot twist.
Why You Should Thank Your Underwriter
Most people barely know underwriters exist, yet they hold the power to approve or deny your life's biggest purchase. They're the unsung heroes standing between you and a mortgage disaster. Next time someone asks what they do, just say: "They make sure I don't buy a house I'd regret."
So when your loan finally gets approved, give a mental high-five to your underwriter. They spent sleepless nights checking your financial homework so you could get those keys. And honestly, that's a pretty solid deal for both sides.