
Ever wonder why your credit score suddenly dropped by, say, 20 points? It's like your financial report card gave you a "B minus" when you were expecting straight A's. Let's peel back the curtain and see what's really going on down there.
Missing Payments: The Biggest Buzzkill
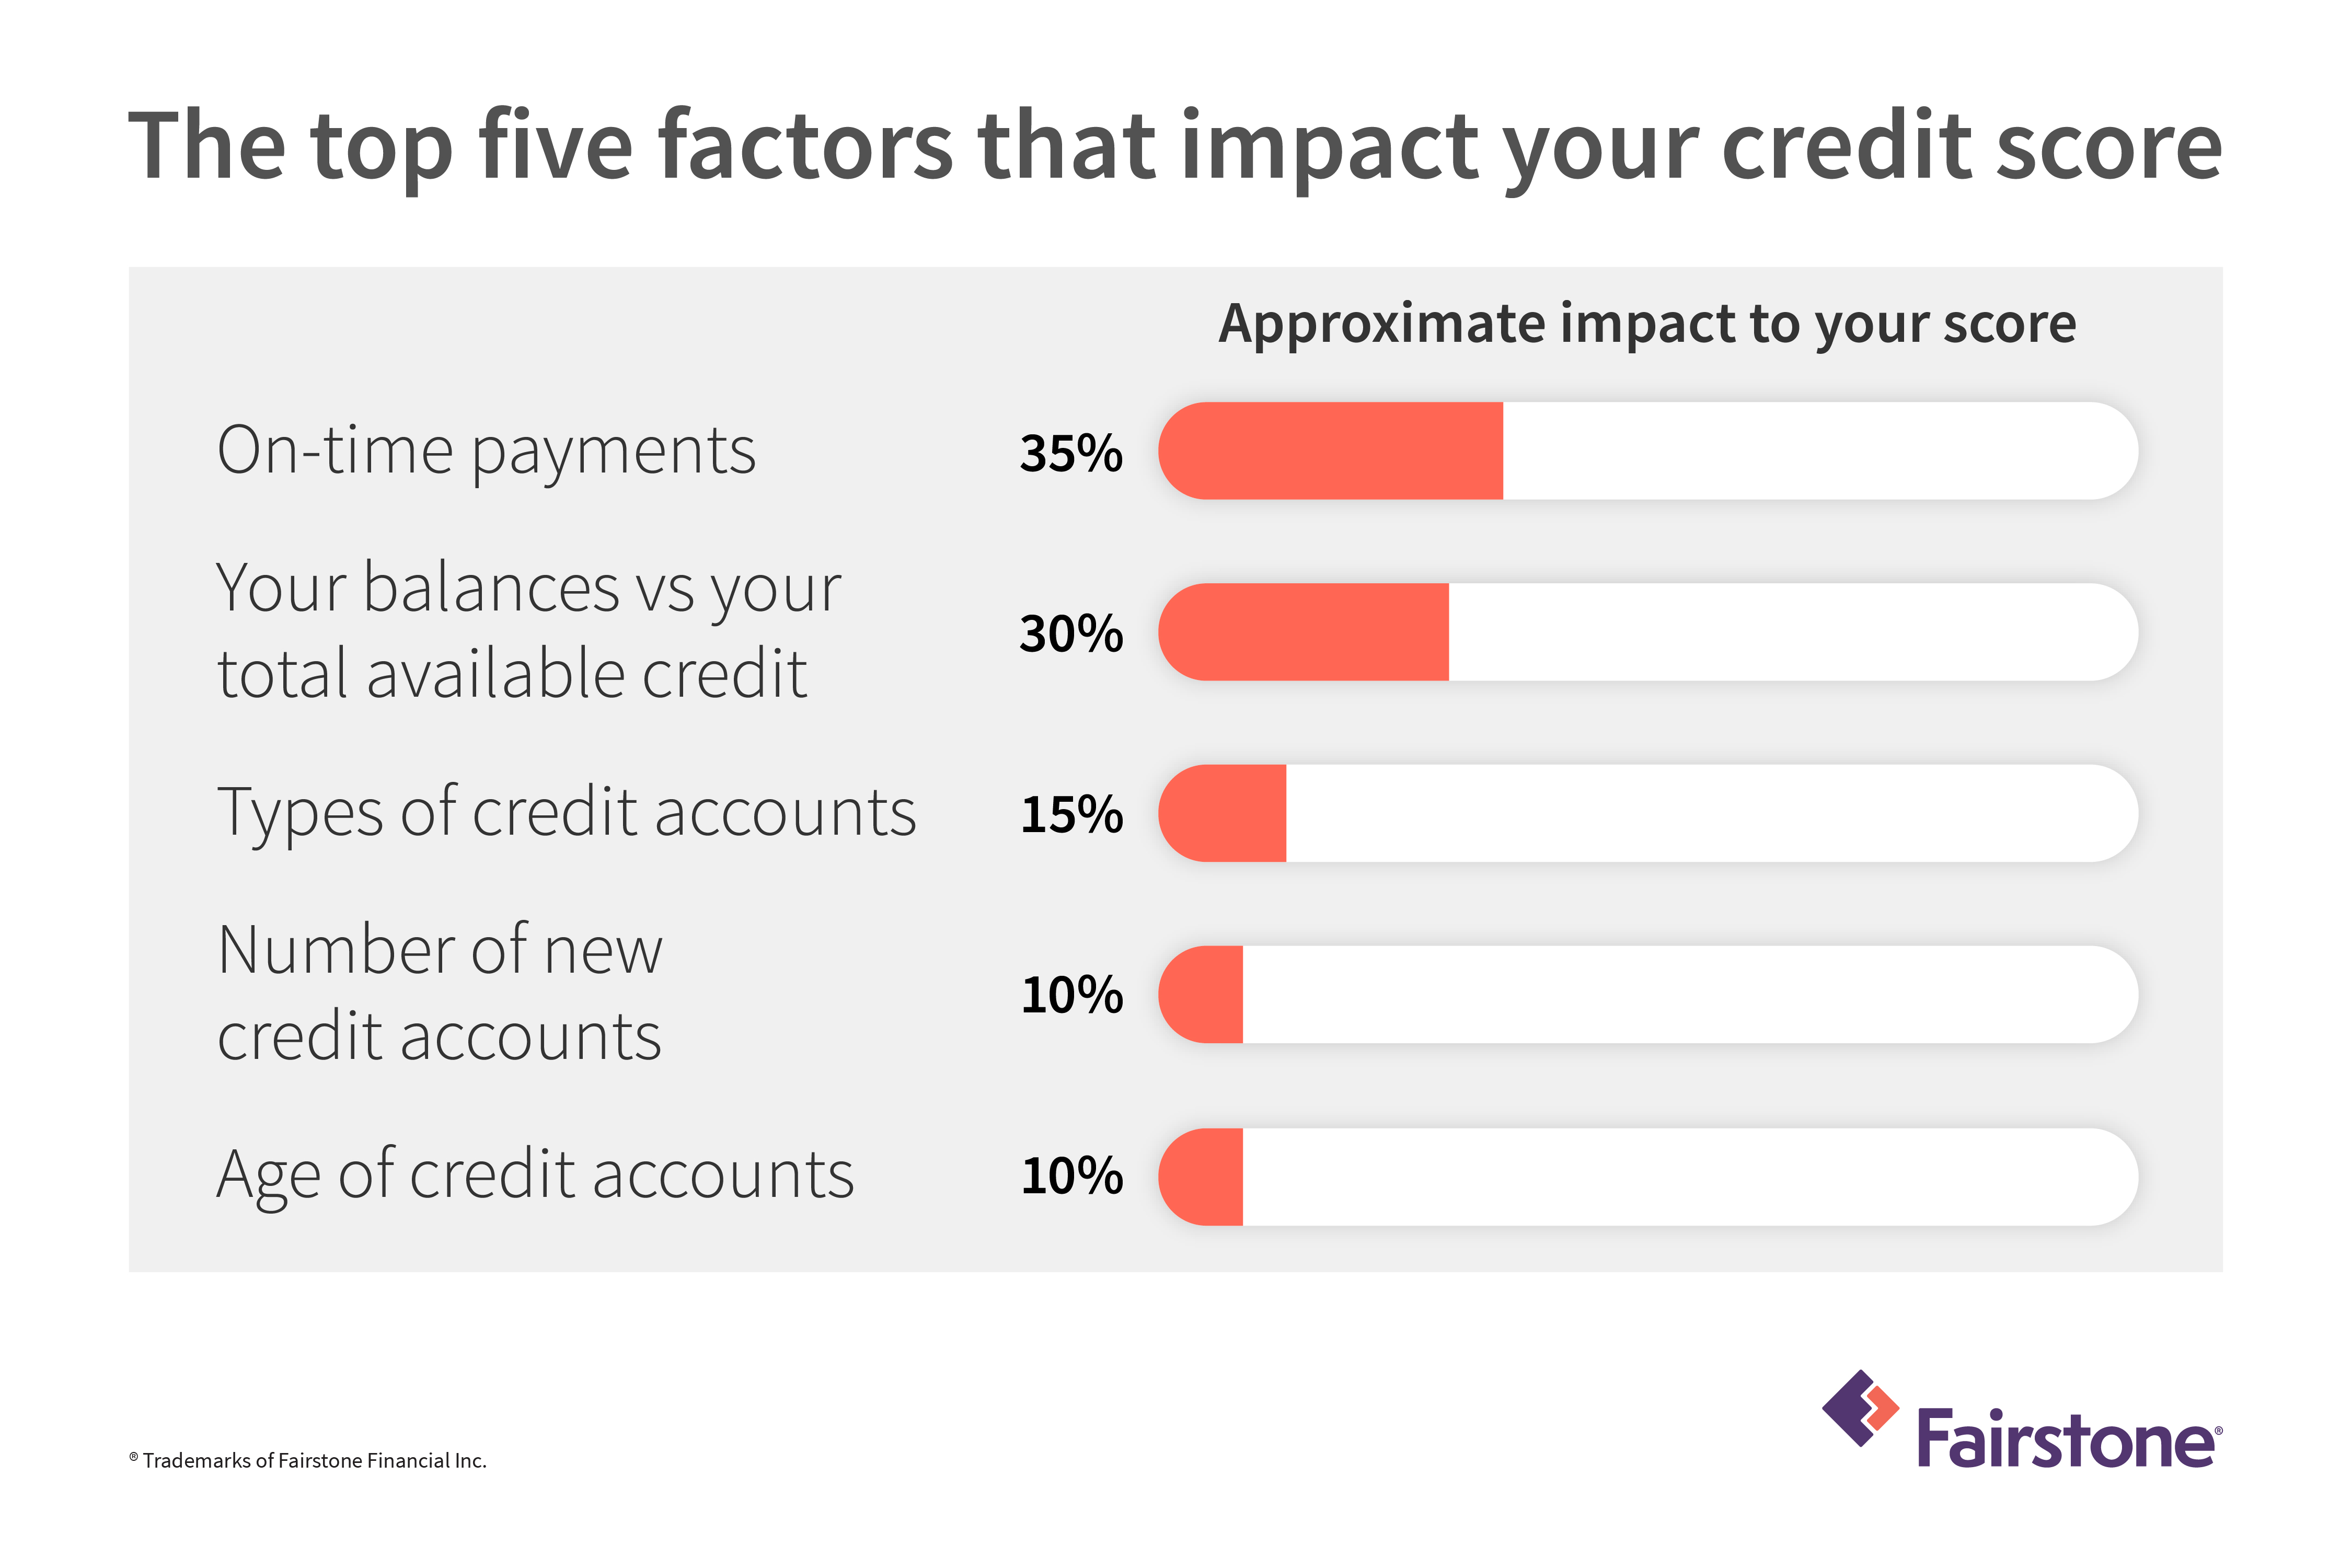
Think of your credit score like a friendship. Nothing kills trust faster than ghosting someone, right? Late or missing payments are the number one reason your score takes a nose dive.
Even one missed payment can sting. Lenders see that and think, "Hmm, can this person keep a promise?" Over time, those missed payments stack up like dirty dishes in the sink—nobody wants to deal with that mess.
Must Read
Your Credit Utilization Creeped Up
You know how a backpack gets heavier the more you stuff into it? Your credit utilization works the same way. When you're using a big chunk of your available credit—say, maxing out a card—your score gets weighed down.
The sweet spot? Keeping your usage under 30% of your total limit. Go over that, and it's like telling the world, "I'm living paycheck to paycheck!" Not exactly a confidence booster for lenders.
Too Many Hard Inquiries
Every time you apply for new credit, lenders run a hard inquiry on your report. It's a bit like bumping into exam proctors a hundred times while studying—they're just checking if you're getting too nosy. Each one can shave a few points off your score.
 Why Did My Credit Score Drop After Paying Off Debt? | Lexington Law
Do it in a short period, and it adds up fast. Lenders wonder why you're suddenly shopping for credit everywhere. It looks desperate, even if you're just curious.
Old Debts Sent to Collections
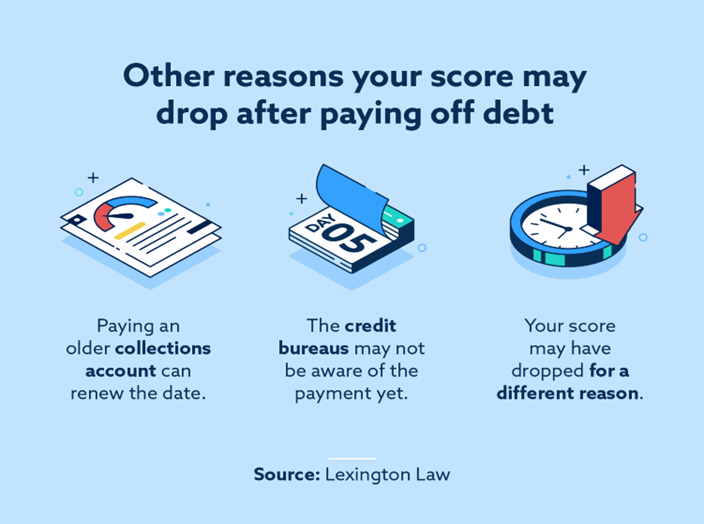
This one hurts. A debt that goes to collections is like that embarrassing moment you hoped everyone forgot—it comes back to haunt you. Right when you're getting comfortable.
Collection agencies reporting that old debt will absolutely tank your score. And those things can stick around for seven years. That's longer than most people stay in their first apartment.
 When can paying off debt cause your credit score to drop? | Fairstone
Closing Old Accounts
Here's a fun surprise: closing a credit card can actually lower your score. It reduces your total available credit, which bumps up that utilization ratio we just talked about. Sneaky, huh?
It also shortens your credit history. If you've been paying a card off responsibly for ten years, walking away from it is like erasing years of good vibes. Why would you do that to yourself?
Changes in Your Credit Mix
Lenders like to see a healthy mix—credit cards, loans, a mortgage, the works. If you lose one type of credit entirely, the balance shifts. Imagine a basketball team losing its point guard: everything feels a little off.
 My Credit Keeps Going Down : Money blog: Subway drastically changing
Suddenly your score has less to brag about. Diversity isn't just cool in our daily lives—it's critical in credit scoring too.
The Big Takeaway
Your credit score isn't some mysterious number invented to ruin your day. It's a living snapshot of your financial habits, updating as you go. The cool part? Once you know what drags it down, you can fix it.
Pay bills on time, keep balances low, and think twice before opening or closing accounts sneakily. Watch that number climb back up—and enjoy the peace of mind that comes with it.