So, you've been squirreling money away in an IRA, huh? Smart move. But now the big question looms: when can you actually touch it? Let's break it down without the boring financial jargon.
The Magic Number: 59½
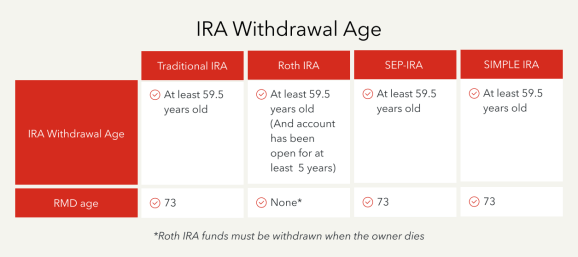
In the world of IRAs, the golden moment is age 59½. Yes, they really do specify the half. Think of it as the financial equivalent of a driver's license lurking just past the halfway mark.
Before hitting this milestone, withdrawing from your IRA triggers a 10% early withdrawal penalty. That's on top of any taxes you'd owe anyway. Ouch.
Must Read
It's a bit like getting caught sneaking into a concert before the doors officially open. You want to be there, but the consequences aren't fun.
Wait, There Are Exceptions?
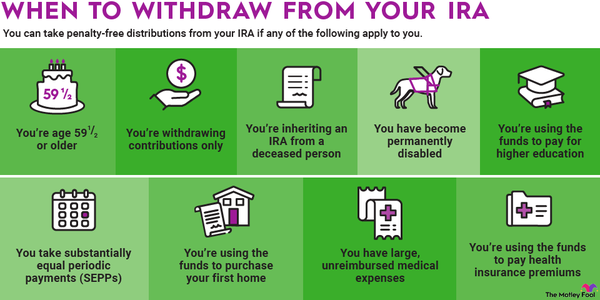
Good news — the rules aren't as ironclad as you might think. Certain situations let you dip into your IRA early without that 10% penalty. Life happens, right? The IRS seems to get that.
For example, first-time homebuyers can withdraw up to $10,000 early. Think of it as a small head start when you're chasing that dream house.
 SEP-IRA Contribution Limits and Deadlines
Qualified education expenses also count. Because apparently, paying for school shouldn't feel like stealing from your future self.
Medical Emergencies and More
If you face unreimbursed medical expenses that exceed 7.5% of your adjusted gross income, early withdrawal is allowed. The IRS essentially says, "We get it — bodies break down sometimes."
Military reservists called to active duty have a special window too. If your average military service period lasts more than 179 days a year, you're free to withdraw early.
 Rules for IRA Withdrawals | The Motley Fool
And if you land unemployed and are pulling unemployment compensation, that counts as well. The IRS is surprisingly reasonable when life throws curveballs.
Required Minimum Distributions
Here's where it flips — the government actually forces you to start withdrawing at a certain point. For traditional IRAs, the deadline appears to be RMD age, which has shifted to 73 as of recent updates.
Missing this requirement comes with a hefty 25% penalty on the amount you were supposed to withdraw. Unlike early withdrawals, this is the IRS saying, "Use it or lose it."
 11-Step Guide To IRA Distributions
Roth IRAs play by slightly different rules since you've already paid taxes on contributions. You're never required to withdraw from a Roth IRA during your lifetime — pretty cool, right?
It's Your MoneyEventually
At the end of the day, an IRA is like a time-locked piggy bank. The government makes you wait mostly because they want your savings to grow and you to be financially secure later.
Understanding these age rules helps you plan smarter. Why play financial roulette when a little knowledge goes a long way?
Knowledge your future self will absolutely thank you for.