So, you've got a whole life policy. Congratulations, you've signed up for a financial ritual more confusing than a magic trick. It's the insurance equivalent of a magic set that promises a rabbit but delivers a tax-deferred growth schedule. It's all sound, fury, and... paper cuts.
Recently, you've been staring at the original sales pitch. You're where the temptation hits you like a pie to the face you didn't know was in the oven. You dream of a golden ticket, a veiled promise of instant wealth just sitting there, waiting for you to just say the words.
Then, a little voice in your head perks up. It's not the angel or the demon, it's just a tired guy asking the real questions. You know, the ones like, "Do I really want to suffer through the financial buffet of adulthood for a potential payoff?"
Must Read
So you do something wild. You actually talk to your insurance agent, the Wizard of Insurance. He doesn't cackle, but he does smile a lot while he explains that cashing out your whole life policy is complicated. Apparently, financiers work in surprising waves of smiling whispers and paper cuts.
There's a dirty little secret. The cash value isn't just your sweet, sweet money sitting in a piggy bank, no. It's the sum of all the premiums you've paid over the years, minus a bunch of fees I'm 90% sure only lawyers read. You're basically paying yourself back with interest, which seems like a lovely idea, until you check the fine print.
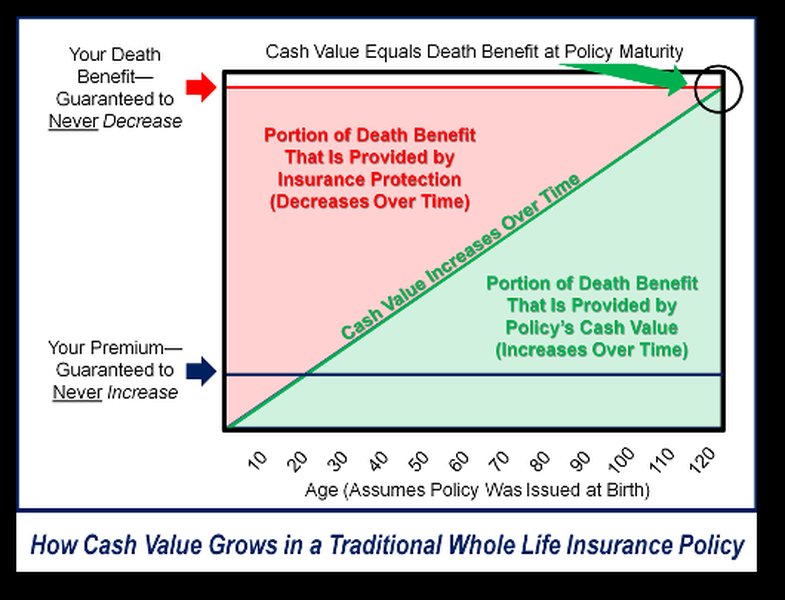 Ithy - Unlocking the Enduring Value of Whole Life Insurance Policies
See, life insurers are all about playing the long game, like a sloth doing tax evasion. The moment you cash out, the contract vanishes into thin air. Suddenly, your loved ones are left with a lump sum of cash instead of a life raft, and that's a big change when your financial boat takes on water.
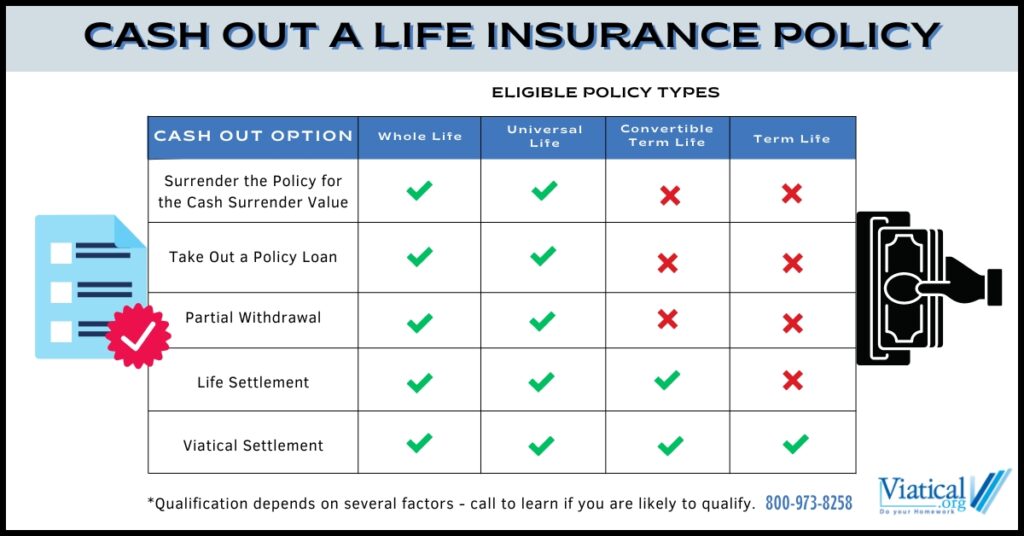
Often, the "cash out" is more of a policy loan. You're borrowing your own money and paying back... yourself, with interest. It's like shoving a wooden spoon into a maze of soup.
 Whole Life Insurance: Everything You Need To Know
Then, a thought dawns on you. The policy might be there for your grandkids, your hypothetical future kids, or even your cat, Mr. Whiskers, if he learns how to sign his own name. Plus, having a policy means you've got a stable premium for life, and will lower your life insurance rates.
There's also that simple feeling of contentment. You're paying into something that will, according to the sales pamphlet, pay you back. It's a strange loop, a financial ouroboros eating its own tail, but hey, it works for the insurance company.
 Should I Cash Out My Whole Life or Universal Life Insurance Policy
Your insurance company loves you. Seeing you maintain your policy is like a sugar rush of certainty. They can count on your premium payments for decades, which makes their actuaries do a little happy dance made of spreadsheets.
Now, cashing out is only okay in one of two scenarios. Scenario one: you're genuinely in near-total poverty, which is not a fun game show to host. Scenario two: you're about to fall into a black hole, but even then, scientists say you'll experience infinite time dilation before you hit the event horizon.
Ultimately, you look at your policy. It's not just a complex ritual designed to confuse financial lawyers. You've considered it and decided to keep it, proving you're an absolute old pro.