So, you've made it to the big leagues of life decisions. Not choosing what to binge-watch on Netflix, not picking a restaurant for date night. We're talking about buying a house — the closest thing to adopting a permanent, 30-year commitment that doesn't come with a ring.
But here's the real question keeping you up at night (besides your suspicious neighbor's 2 AM car revving): should you buy in 2024 or wait until 2025? Let's break this down before your real estate agent starts texting you emojis you don't understand.
The 2024 Situation: Should You Just Pull the Trigger?
Here's a fun fact: mortgage rates hovered around 6-7% in 2024. That's not the dreamy 3% we all got addicted to a few years ago, but hey — nobody said owning a house would feel like drinking oat milk. It's an acquired taste.
Must Read
Inventory — meaning available homes — has been slowly opening up. Think of it like a buffet that finally stopped running out of rolls. More options mean you might not have to settle for the house next to the landfill (unless you're oddly into that view).
On the flip side, home prices in many markets haven't exactly crashed to your bank account's delight. The median U.S. home price still sits well above $400,000, which is a number that makes some people laugh and others cry at the grocery cart.
 Should I Buy A House Now Or Wait Until 2024
The 2025 Outlook: Is Waiting the Power Move?
Many economists are cautiously betting that rates might edge down slightly in 2025. That could mean a few more dollars staying in your pocket each month — money you can spend on upgrades like a bathroom you're not embarrassed to show guests.
Waiting might also give sellers the reality check they've been avoiding. When buyers disappear like free samples at Costco, prices tend to soften. That's basic supply and demand — also known as "the universe finally cutting you a break."
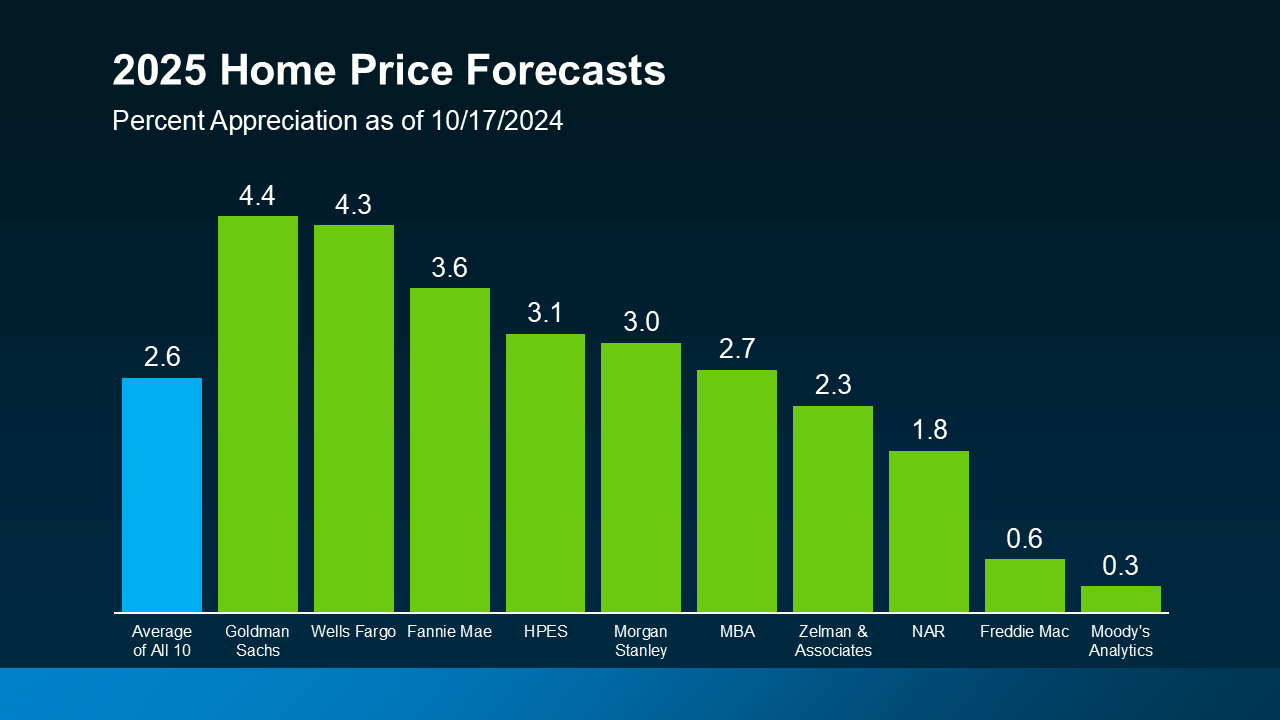 What To Expect from Mortgage Rates and Home Prices in 2025
But let's not get cocky. Predicting the housing market is like predicting the weather in an unhinged city — experts get it wrong regularly, and your cousin on Facebook gets it wrong even more confidently.
So... What Should You Actually Do?
Here's the honest answer: it depends on your life, your savings, and your tolerance for stress eating. If you need a house now, rates don't make a good master. Buy the home, fill it with furniture from IKEA, and screw in the furniture with confidence.
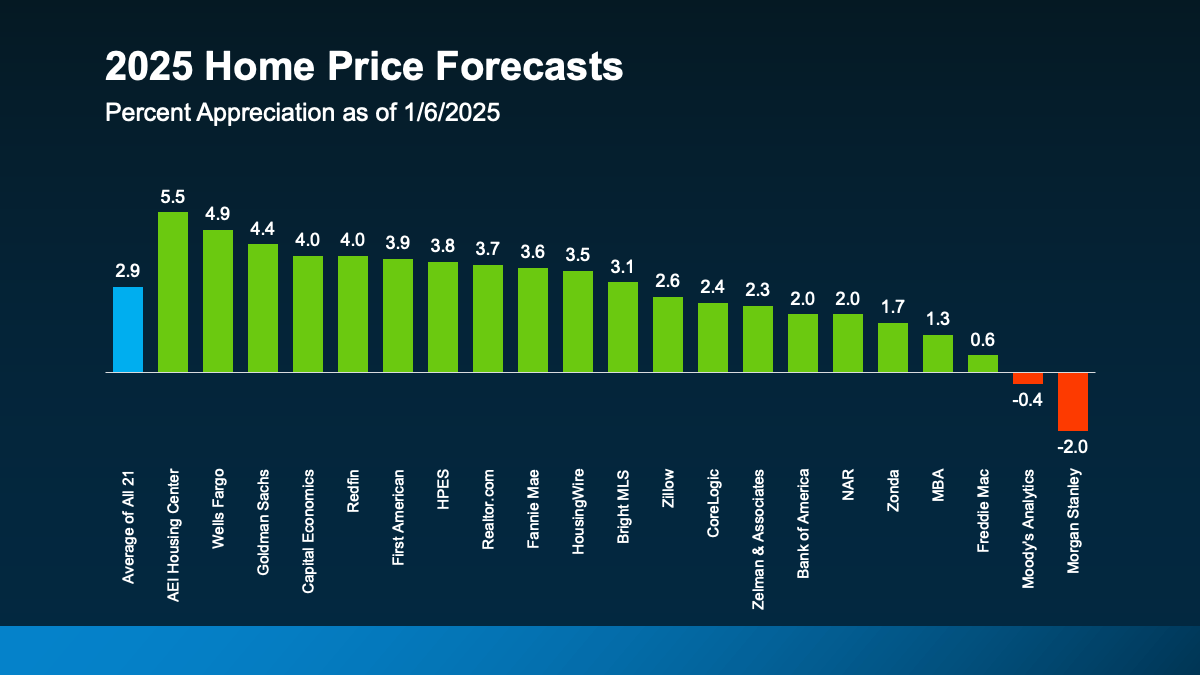 Expert Forecasts for the 2025 Housing Market - Backus Realty and
If your lease has more room to breathe and your finances need a little CPR, waiting until 2025 might be your best bet. Just make sure you're researching, not refreshing listings at 1 AM like it's a Taylor Swift concert ticket drop.
One thing's for sure — while you're sitting on the fence deciding, the market keeps moving. So whether you jump in 2024 or 2025, just make sure you're watching your budget and not your imagination run wild.
Bottom line: 2024 is the "act now" option, 2025 is the "let's see what happens" option. Both are valid. Neither will make you rich overnight, but one of them will definitely make your landlord very, very sad.