
Ever wonder why some interest rates are tiny and others are way bigger? It all comes down to two main categories: short term and long term interest rates. And honestly, understanding the difference is pretty fascinating.
So What's the Deal?
Think of it like borrowing money from a friend. Would you ask for a few days of help or borrow a little bit each week for an entire year?
Short term interest rates apply to loans and investments that are, well, short. We're talking about periods that usually go up to one year or even just a few months. Long term rates, on the other hand, stretch out over years or even decades.
Must Read
Why Do We Even Care?
Because how much you pay in interest depends entirely on whether your loan is short or long. A mortgage that lasts 30 years feels completely different from cashing a check next Friday, right?
Short term rates tend to move quickly. They respond fast to what central banks decide, so they can flip from low to high in a matter of months. Long term rates are a bit more like a slow-moving cruise ship — they take their time.
 Inverted yield curve: Opportunities in long-term fixed interest rates
The Risk Factor
Here's a fun thought: would you rather lend money to someone for one day or for thirty years? Longer loans carry more risk because so many things could go wrong over time.
That's exactly why long term rates are usually higher than short term rates. Lenders want a little extra compensation for sticking around for the long haul. It's basically their patience bonus.
The Yield Curve — Wait, What?
Okay, this is where it gets really cool. If you plot short term and long term rates side by side on a chart, you get something called the yield curve. Think of it like reading the mood of the entire economy in one swoop.
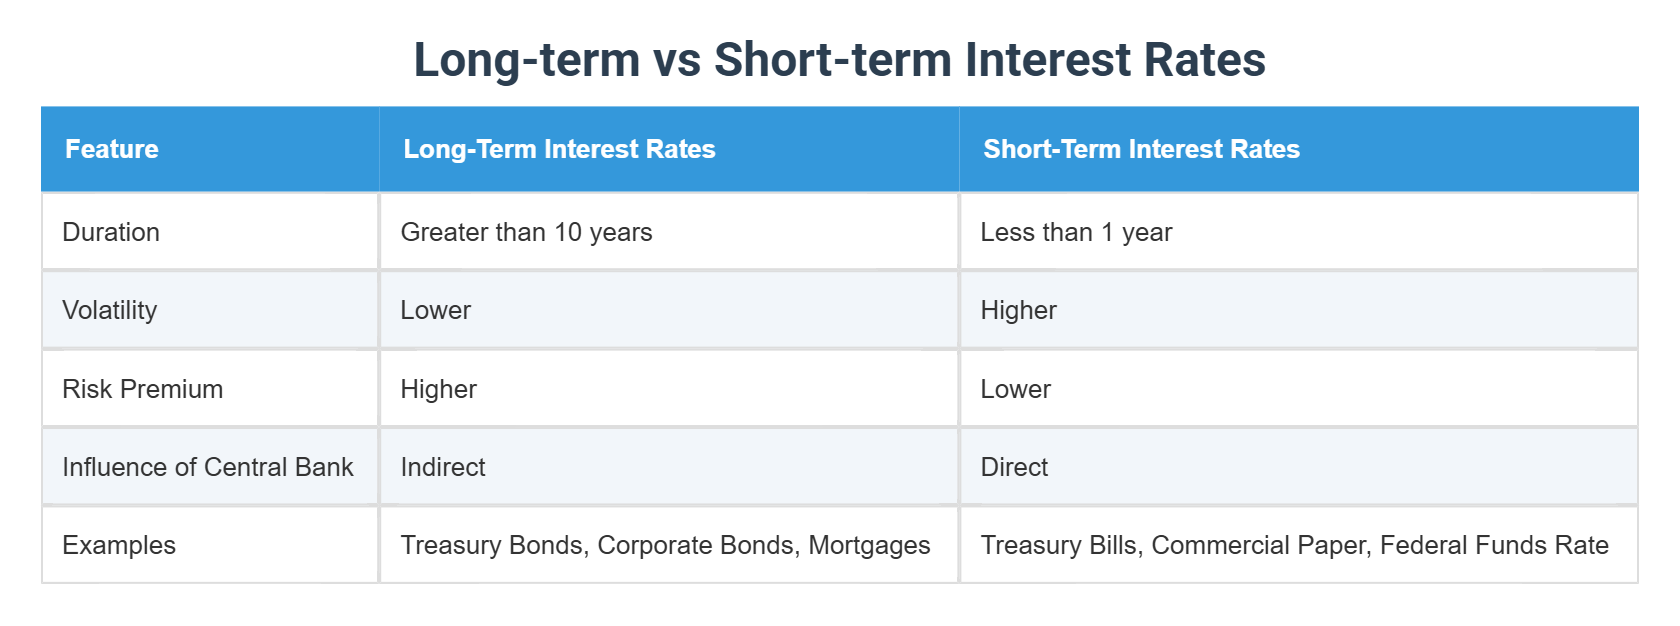 Long-term vs Short-term Interest Rates
Normally, the curve slopes upward — long rates sit above short rates. But sometimes short term rates rise above long term rates, and that creates an inverted yield curve. Historically, that's been a pretty reliable signal that a recession might be lurking around the corner.
Who Sets These Rates Anyway?
Central banks like the Federal Reserve control short term rates directly. They raise or lower them to cool down inflation or give the economy a little espresso shot. Long term rates, though, are more shaped by market forces and investor expectations.
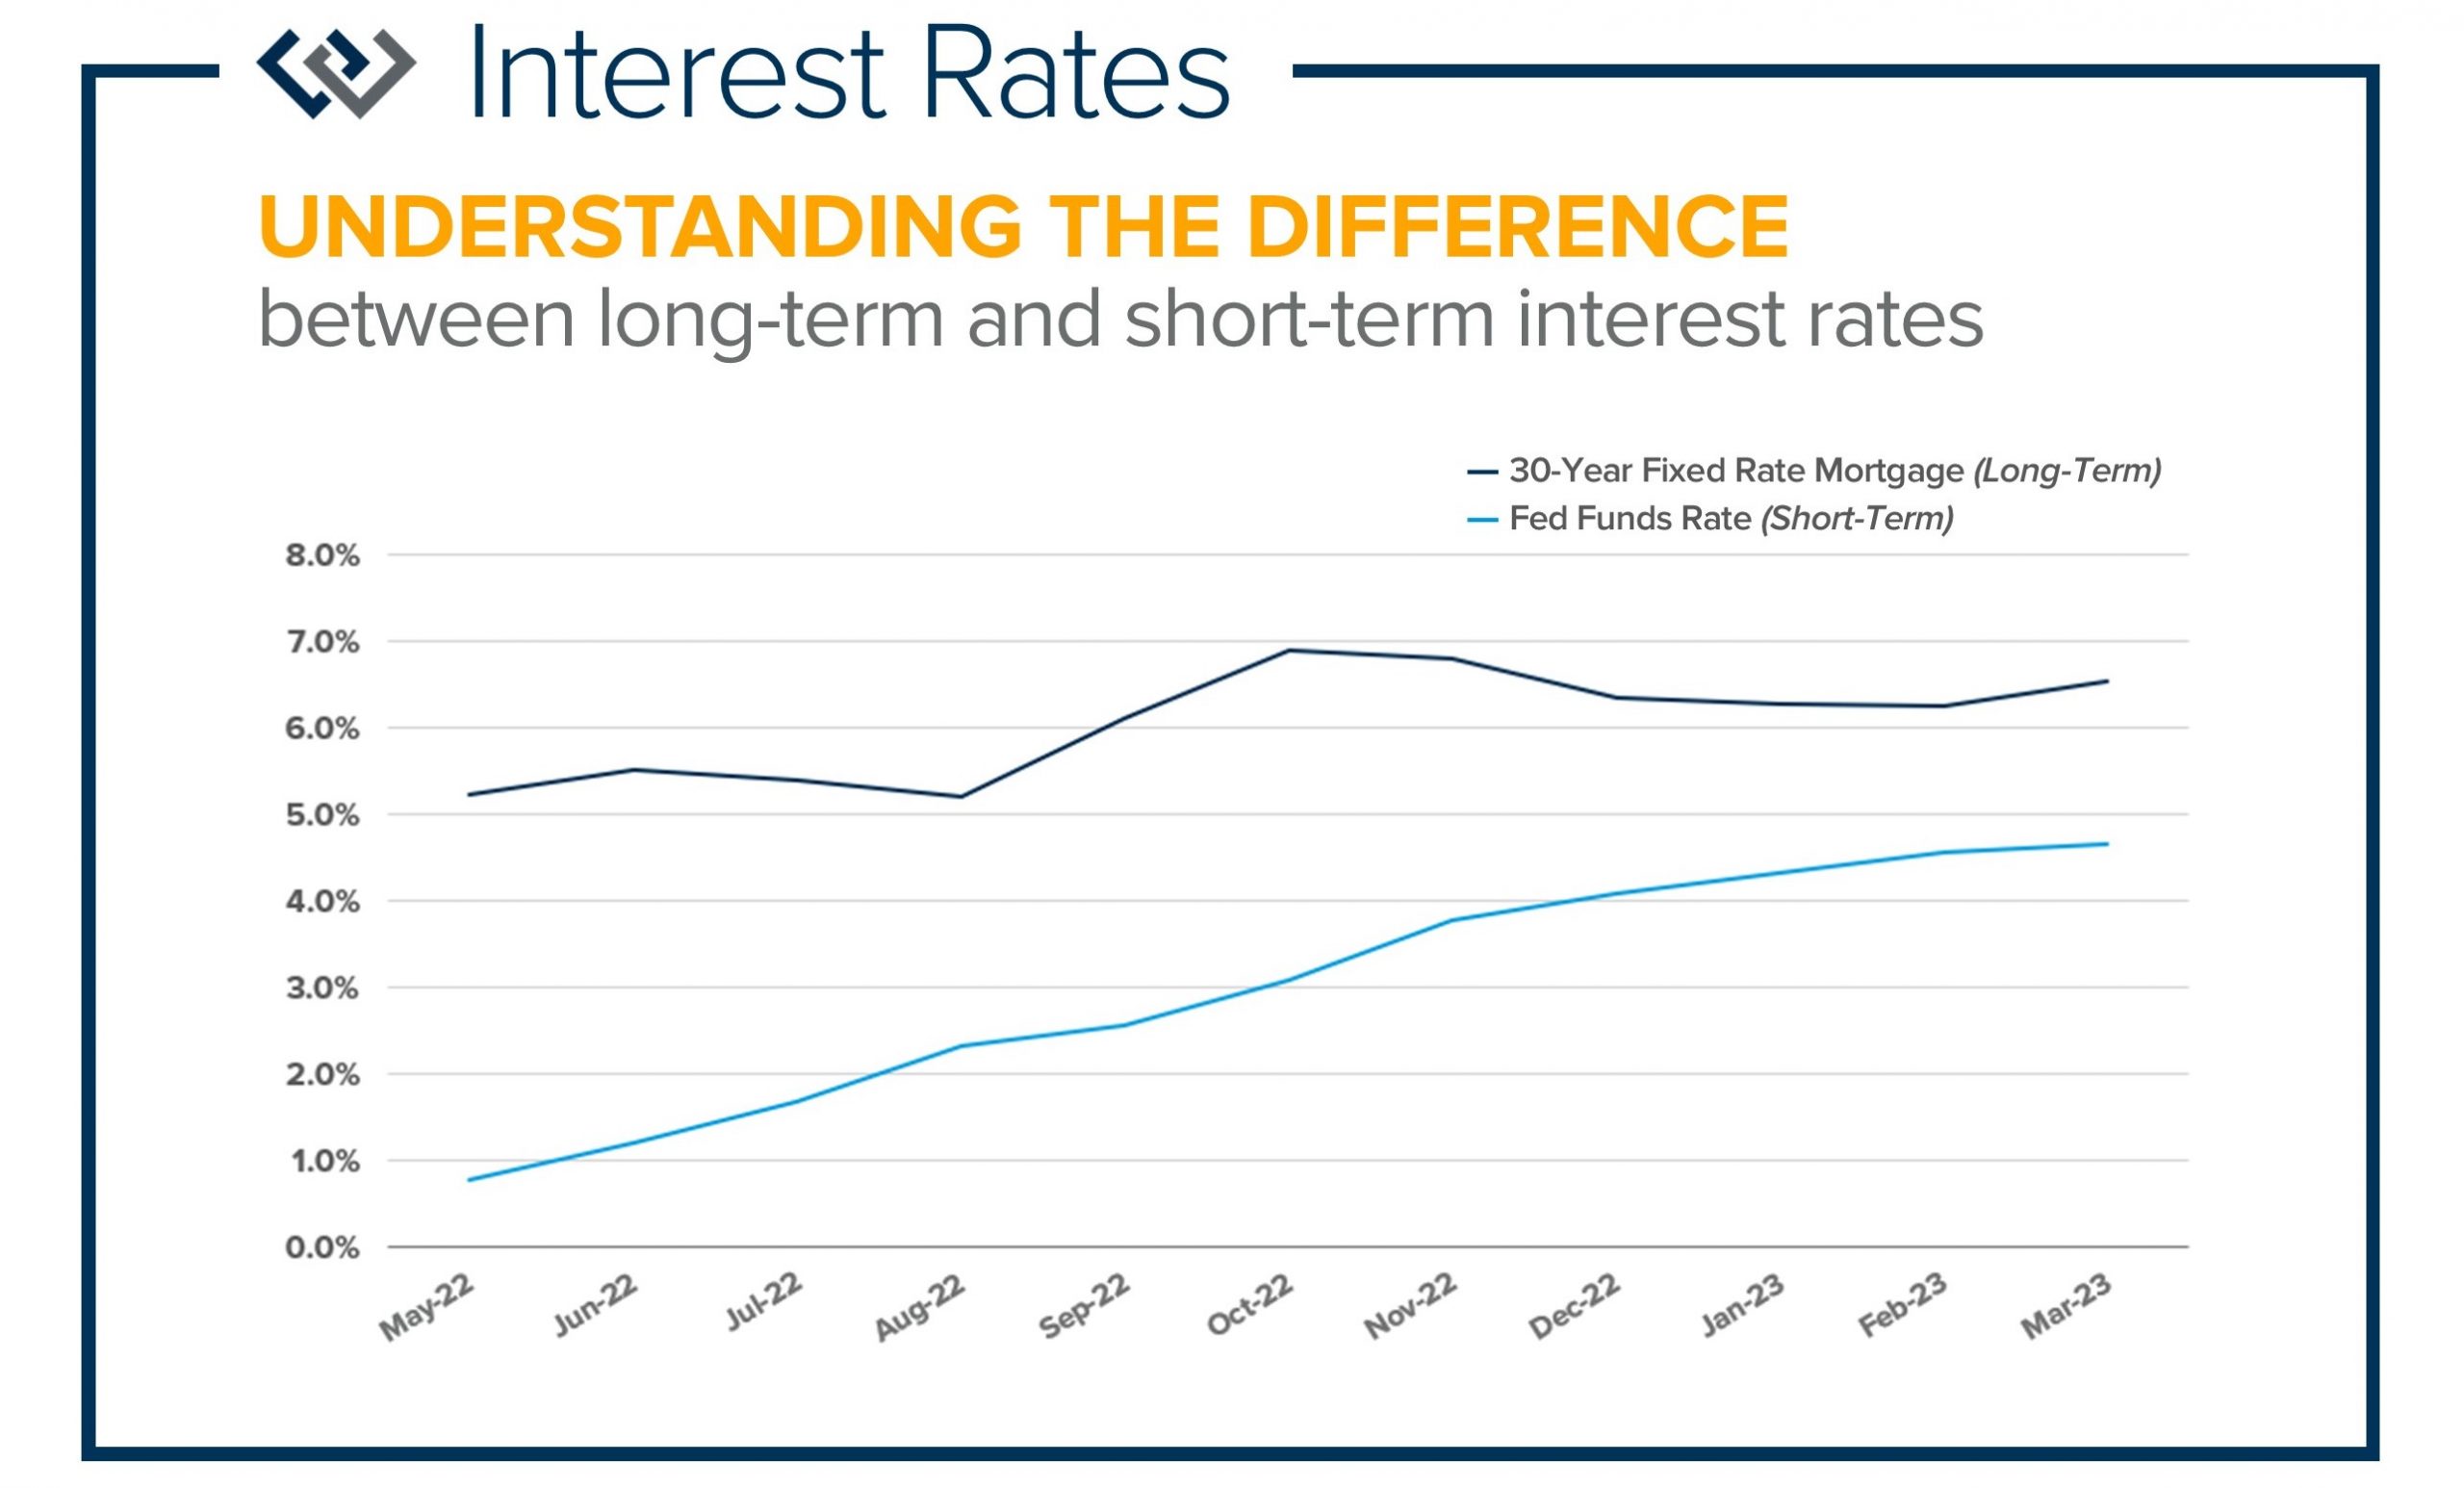 Understanding the Difference Between Long-Term & Short-Term Interest
Imagine short term rates as a thermostat the government can adjust. Long term rates are more like the weather — influenced by many factors nobody fully controls.
Why This Should Feel Interesting
Understanding short vs long term rates helps you make smarter money decisions. Whether you're picking a savings account, locking in a mortgage, or just curious about the economy, the distinction matters. Plus, it's weirdly satisfying to watch the yield curve dance around and tell stories about where the economy is headed.
So next time someone mentions interest rates, you can casually drop the difference between short-term and long-term like a pro. Not bad for a nerdy little finance secret, right? The world of rates is way more interesting than most people give it credit for.