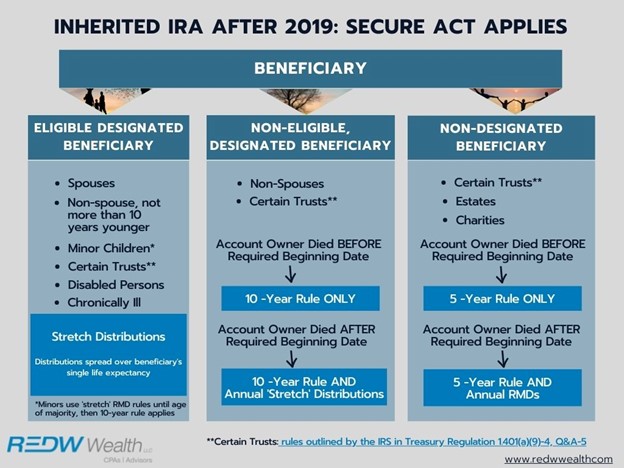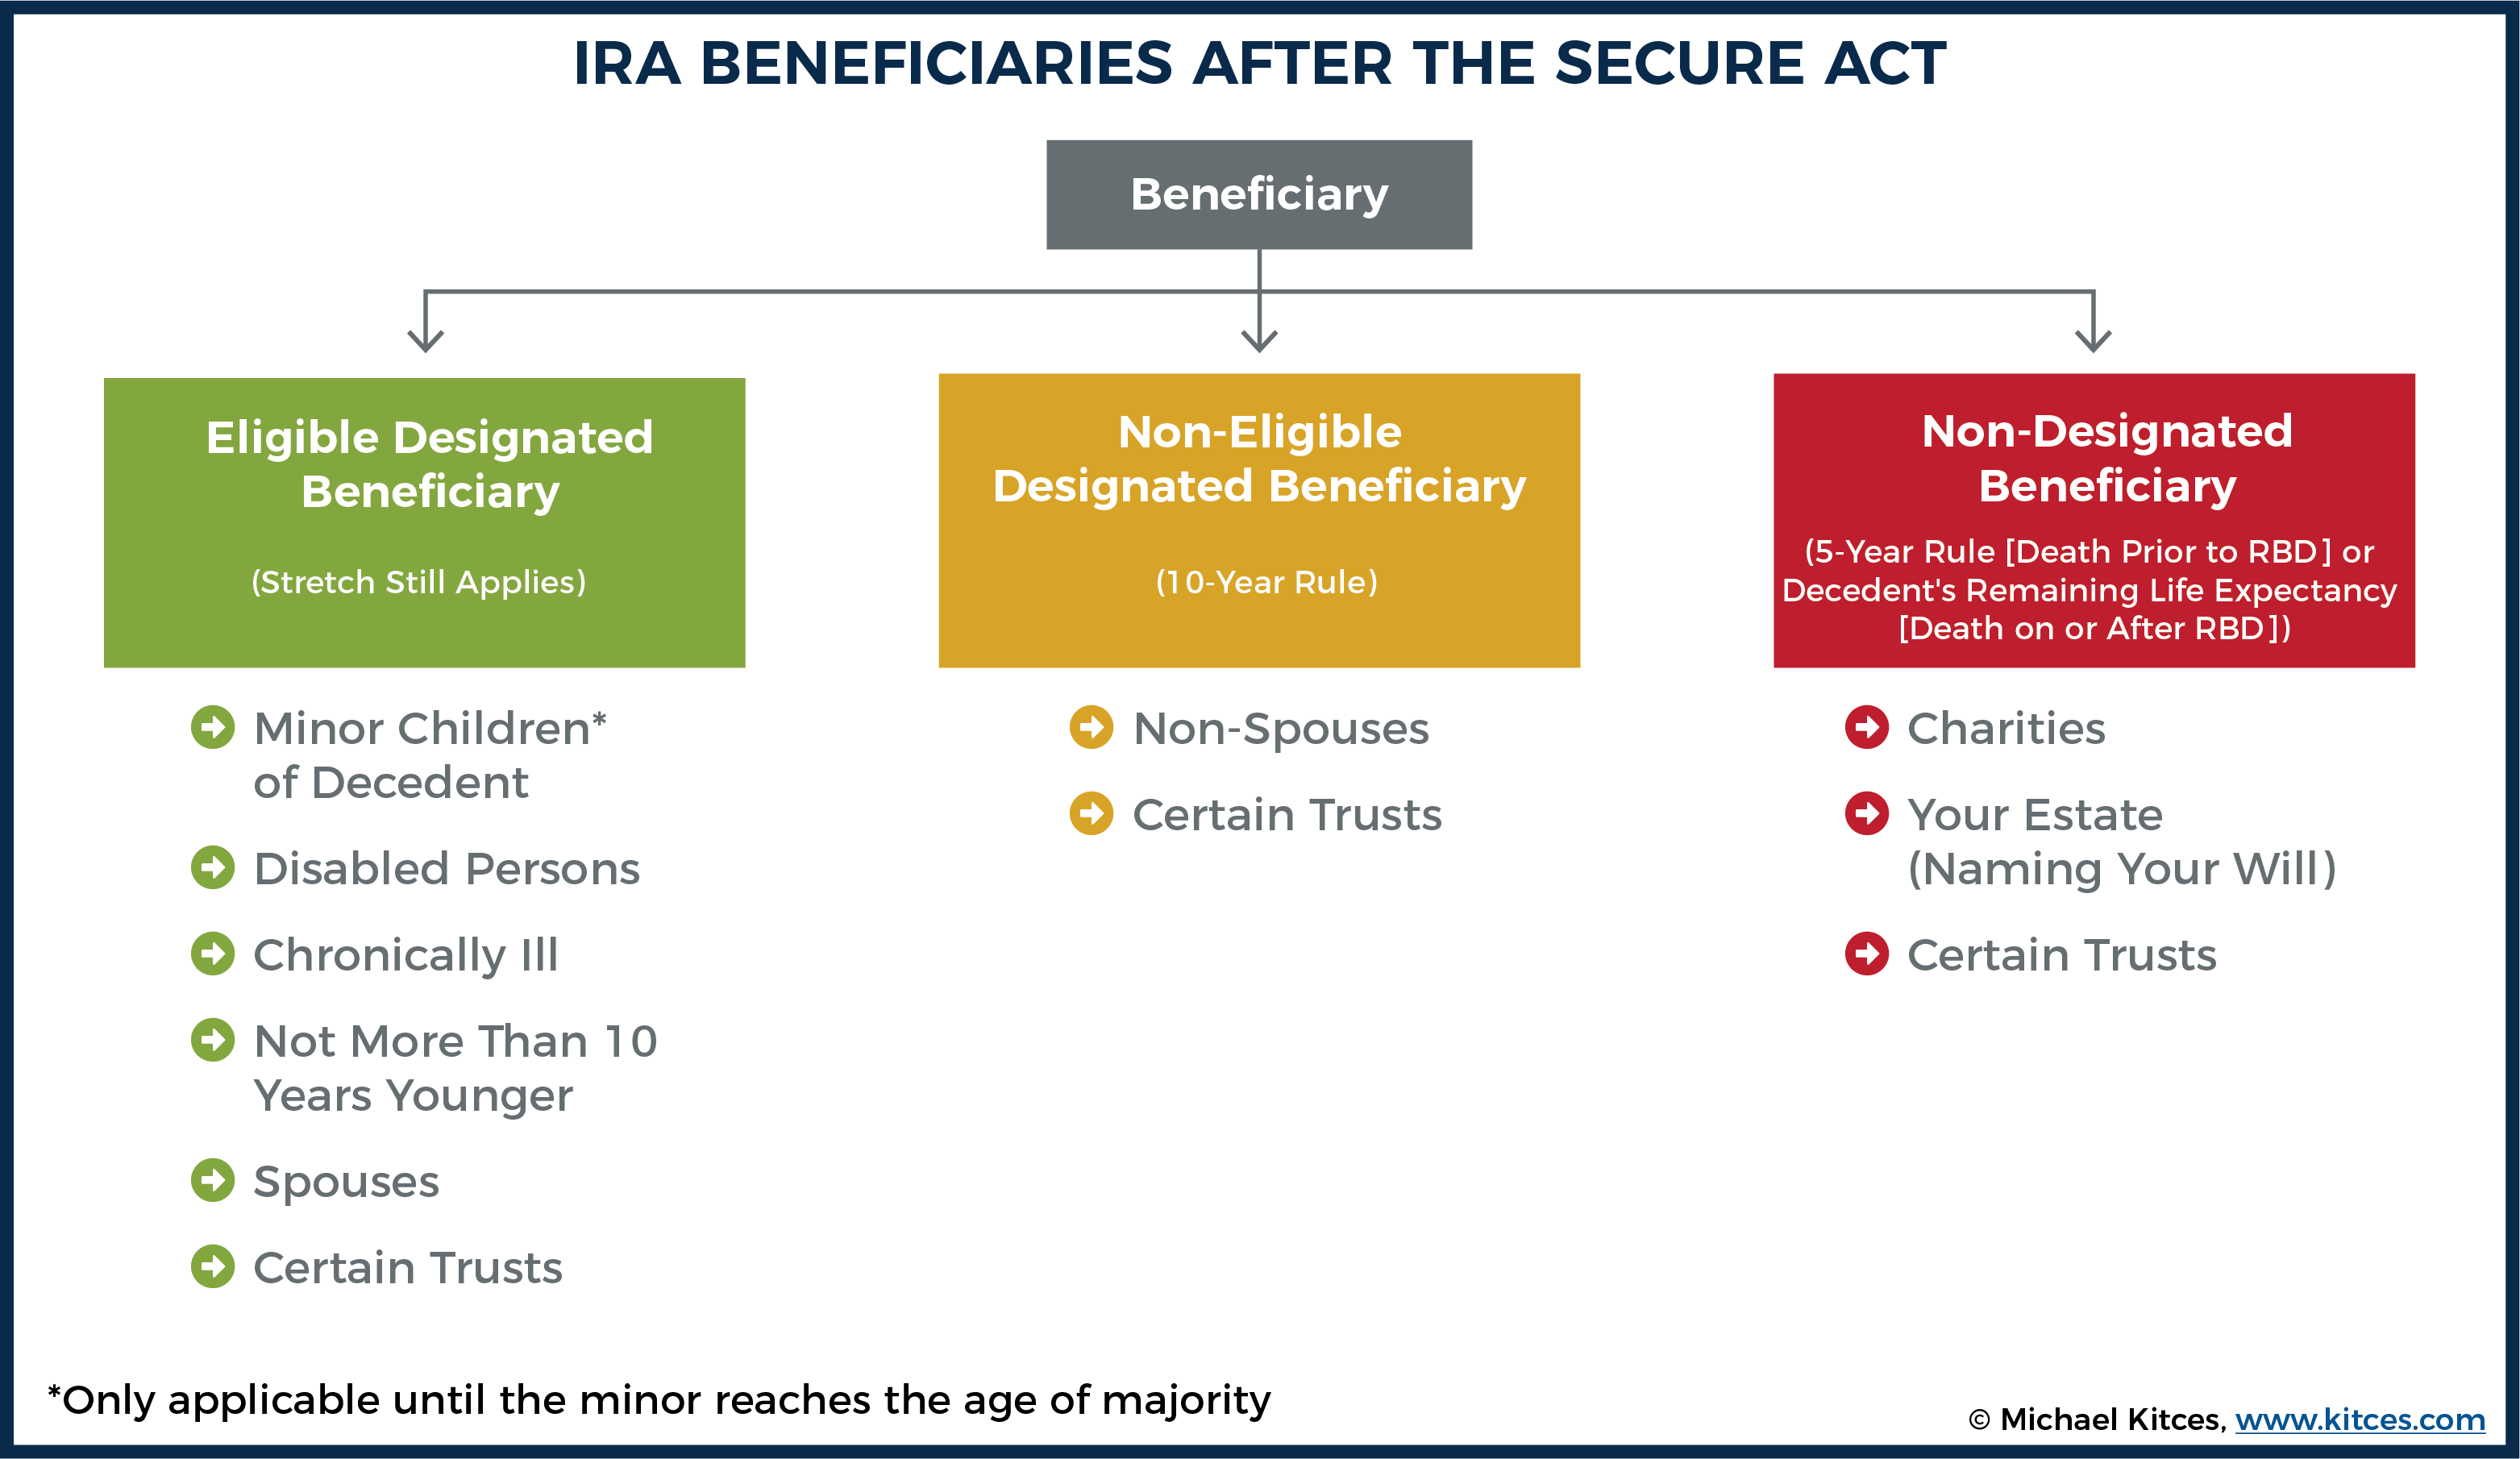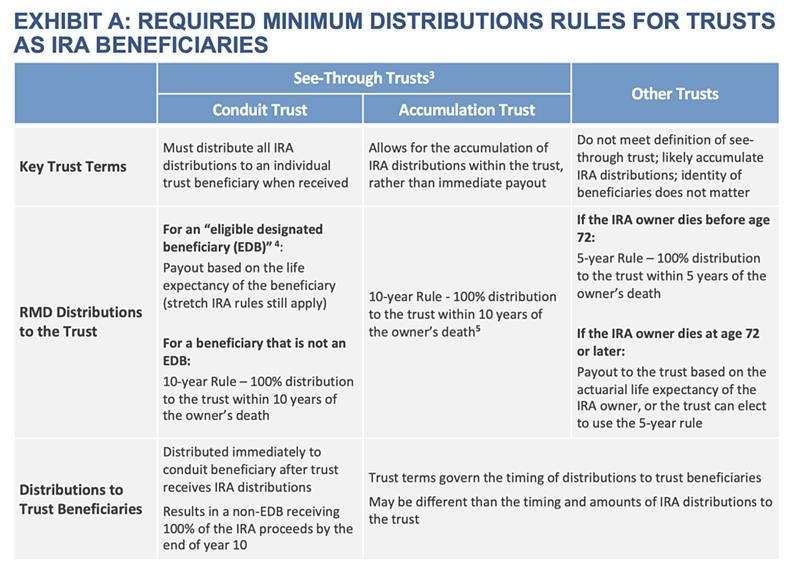
Ever wondered what happens to a parent's IRA when it passes to a child and not a spouse? The rules can feel like a maze, but they’re actually a playground of opportunities for savvy heirs. Understanding Required Minimum Distributions (RMDs) for non‑spouse inherited IRAs is like learning a secret shortcut that can turn a sudden inheritance into a steady stream of tax‑friendly cash.
The main purpose of these rules is to ensure the funds are withdrawn over a defined period, preventing the account from becoming an untouchable vault forever. For a non‑spread heir, the good news is flexibility: you can choose a 10‑year rule or tie distributions to your own life expectancy, giving you control over timing and cash flow. This flexibility often means you can smooth out tax brackets, avoid large lump‑sum penalties, and keep more money working for you.
Imagine inheriting a $500,000 IRA and deciding to spread withdrawals over a decade. Each year you pull out a modest amount, aligning it with a year when you’re in a lower tax bracket—softening the blow. Or, if you’re still working, you might hold off until retirement, then take larger, tax‑advantaged withdrawals while you’re earning less. Both scenarios turn the inherited IRA into a strategic tool rather than a headache.
Must Read
Key facts to remember: the 10‑year deadline starts the year after the original owner’s death, and you must start taking RMDs in the year you reach the required age (currently 73 for most). Failing to take the proper amount can trigger a steep penalty of 25% of the shortfall, so keeping a calendar with marked dates is essential.
 The Final Rules For Non-spouse Beneficiary Inherited IRAs Has Been
Practical tips: 1) Set a reminder for each December to calculate your distribution. 2) Use a simple spreadsheet to model different withdrawal amounts and see how they affect your tax bill. 3) Consider consulting a CPA before making large withdrawals—few minutes of advice can save thousands. 4) If you have leftovers after ten years, you can donate the remainder to charity, turning RMDs into a philanthropic move.
Ready to transform an inherited IRA from a puzzle into a reward? Dive into the details, plan your distributions, and you’ll find that the rules aren’t just constraints—they’re the building blocks of a smarter financial future.