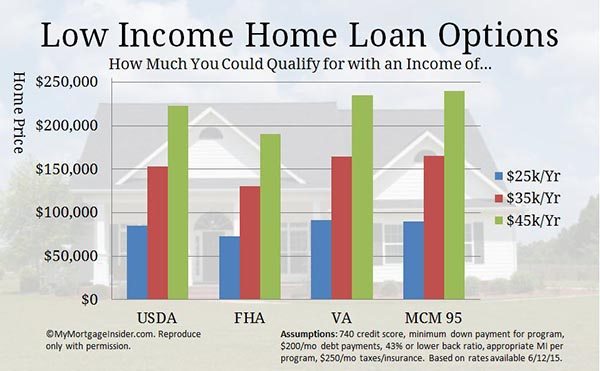
So, you're dreaming of your own front door, but your bank account is giving you the side-eye? Relax — having a low income doesn't mean homeownership is off the table. It just means you need a smarter game plan.
First things first: check your credit score. A solid score can work absolute magic when lenders are deciding whether to trust you with a big, gorgeous mortgage. Pay down small debts, avoid new ones, and watch that number climb! (Yes, it's tedious. But so is moving back in with your parents.)
Next up, government-backed loans are your best friend here. Programs like FHA loans are practically designed for folks with limited income. They come with lower down payments — sometimes as low as 3.5% — and more forgiving requirements. USDA and VA loans are also worth exploring if you qualify.
Must Read
Don't forget about down payment assistance programs. Your local city or state might offer grants or low-interest loans that cover your upfront costs. A quick Google search could save you thousands. You're welcome in advance.
And here's a tip nobody talks about: consider a co-signer. Maybe know a generous relative who believes in you? A trusted co-signer can boost your application and unlock better rates.
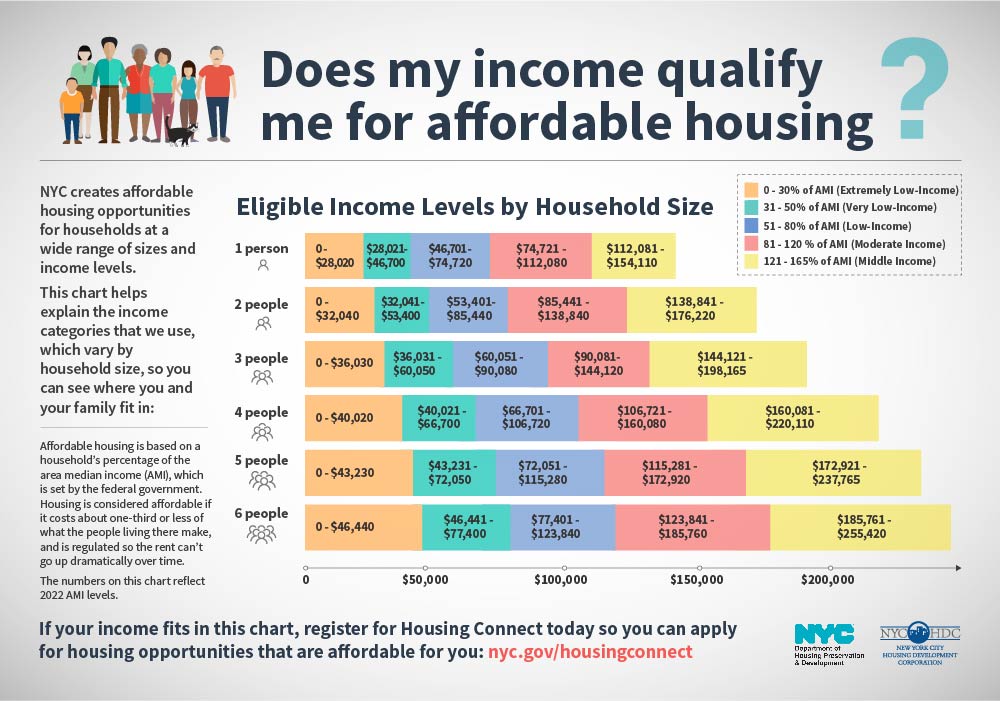 Do You Qualify? - HPD
Lastly, talk to multiple lenders. Shopping around isn't just for bargains at the mall — it applies here too. Rates, fees, and terms vary more than you'd think, and one lender's "no" is another's "absolutely."
Remember, low income is a temporary chapter, not your final story. With the right tools, a little patience, and some hustle, those keys will be jingling in your hand sooner than you imagine. You've got this — and your dream home is waiting.

