
So you've got some extra cash sitting around, and now you're wondering: should I smash that mortgage or shove it into retirement savings? Honestly, it's one of the most debated money questions out there, and you're definitely not alone if you're scratching your head.
First, Let's Talk About the Mortgage
Your mortgage is probably the biggest chunk of debt you'll ever carry, right? Paying it off early feels amazing — like finally cutting a chain you've been wearing for years.
Think about it: every extra dollar you throw at your mortgage saves you years of interest. Imagine cutting twenty years off your loan just by adding a bit more each month. That's like fast-forwarding through a boring movie to get to the good part.
Must Read
Plus, once that mortgage is gone, you own your home outright. That's a pretty sweet safety net, don't you think?
Now, What About Retirement Savings?
Here's the thing — retirement savings have a superpower called compound interest. The money you invest today could grow into something massive over decades, like a tiny snowball rolling downhill until it's astronomically huge.
Waiting to invest means missing out on those critical early years of growth. It's kind of like planting a tree — the earlier you start, the taller and stronger it gets.
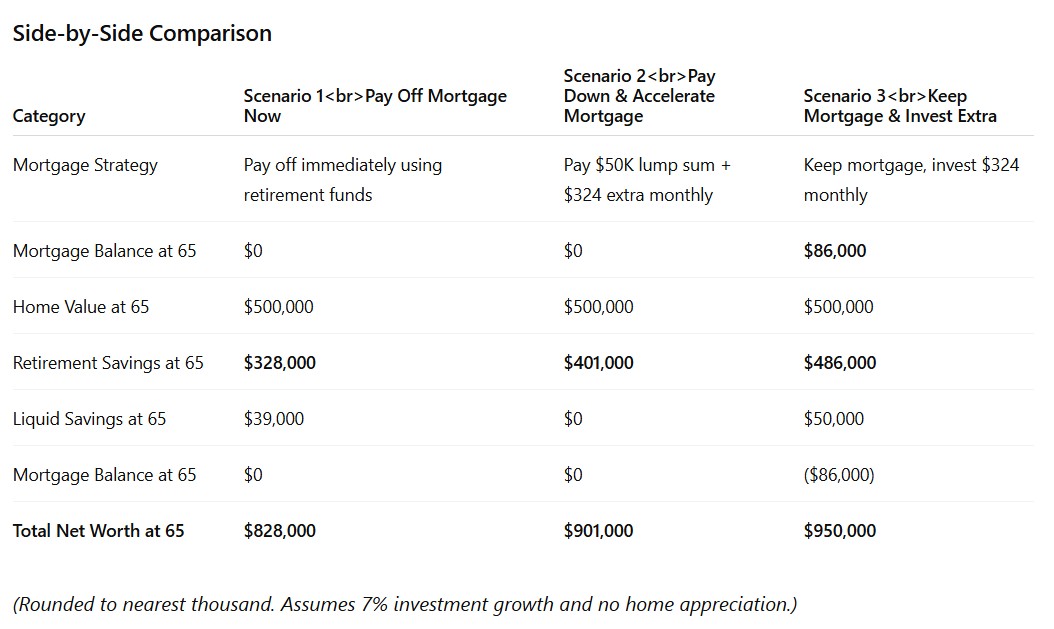 Should You Pay Off Mortgage Before Retirement? The Math Might Surprise
Also, most retirement accounts come with sweet tax benefits. Your money works harder for you when the government isn't taking a chunk of it along the way.
So Which One Wins?
Here's the fun part — there's no single right answer, and that's totally okay. It really depends on your personal situation, your age, your interest rate, and even your personality.
Does debt stress you out more than anything? Then paying off the mortgage might bring you peace of mind, which honestly is priceless.
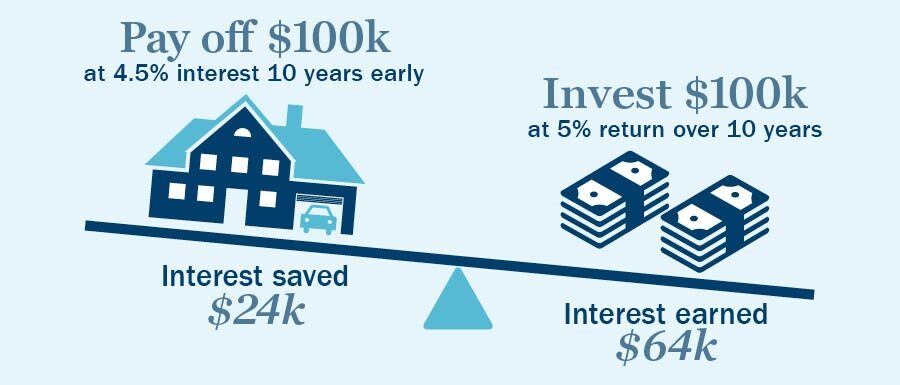 Paying off Mortgage vs Investing - New Century Investments
But if you're more of a numbers person who wants to maximize every dollar, investing in retirement could be the smarter play over time.
The Magic Middle Ground
What if you didn't have to choose just one? Some people do a split approach — pouring extra cash into both the mortgage and retirement accounts simultaneously.
Imagine it like a seesaw that balances perfectly — neither side is neglected, and you're making progress on both fronts. Steady progress on every front beats perfection on just one.
 How to Pay Off Your Mortgage Early
A Quick Reality Check
Before you make any moves, take a look at your interest rates. If your mortgage sits at 7% but your retirement fund earns 10% on average, the math might surprise you.
Don't forget about employer 401(k) matches either — if your company offers free money, grab it. That's like passing up a coupon for something you were already going to buy.
Final Thoughts
At the end of the day, the real goal is financial freedom, whichever road you take. Paying off your home early gives you shelter and stability, while building retirement savings gives you freedom to dream.
So, what excites you more — waking up debt-free or watching your investment portfolio climb? Whatever you pick, the fact that you're thinking this hard about it already puts you way ahead of most people.