One of the most common questions in personal finance is whether a Roth IRA is different than a Roth 401(k). People value these accounts because they offer tax-free growth and tax-free withdrawals in retirement — a powerful advantage that can mean thousands of extra dollars saved over a lifetime. Understanding how they differ helps you make smarter decisions about where to put your hard-earned money.
Both accounts share the same basic purpose: you contribute money after taxes, let it grow without paying taxes on earnings, and withdraw it tax-free after age 59½. This makes them invaluable tools for everyday Americans who want to keep more of their money and avoid tax surprises later in life. The main difference lies in your contribution limits and how the accounts work behind the scenes.
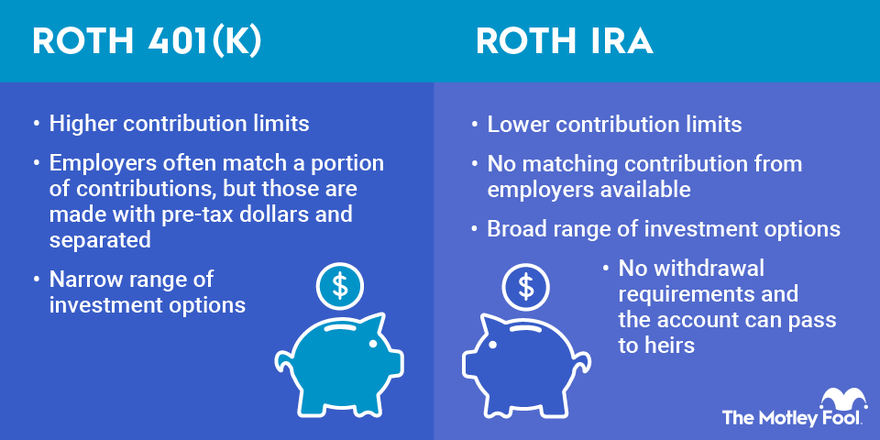
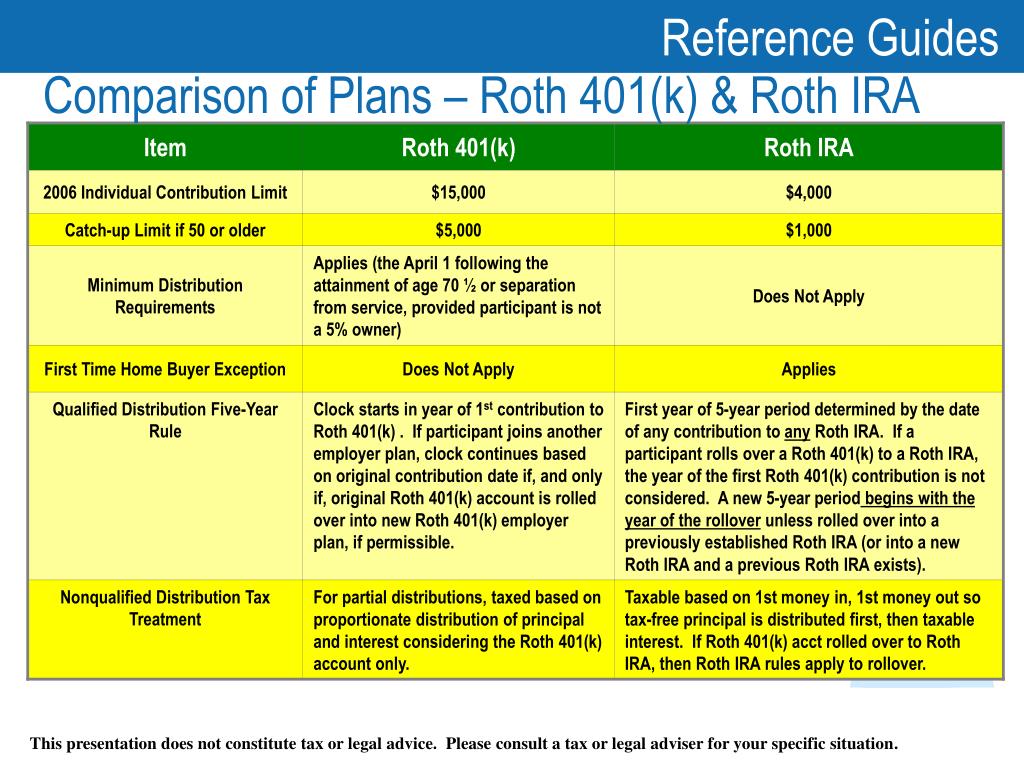
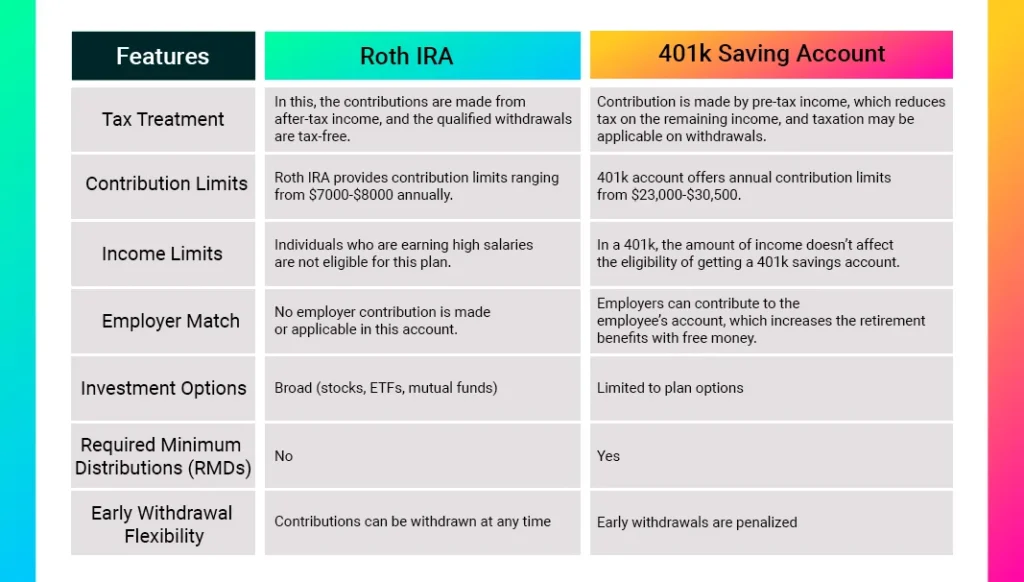
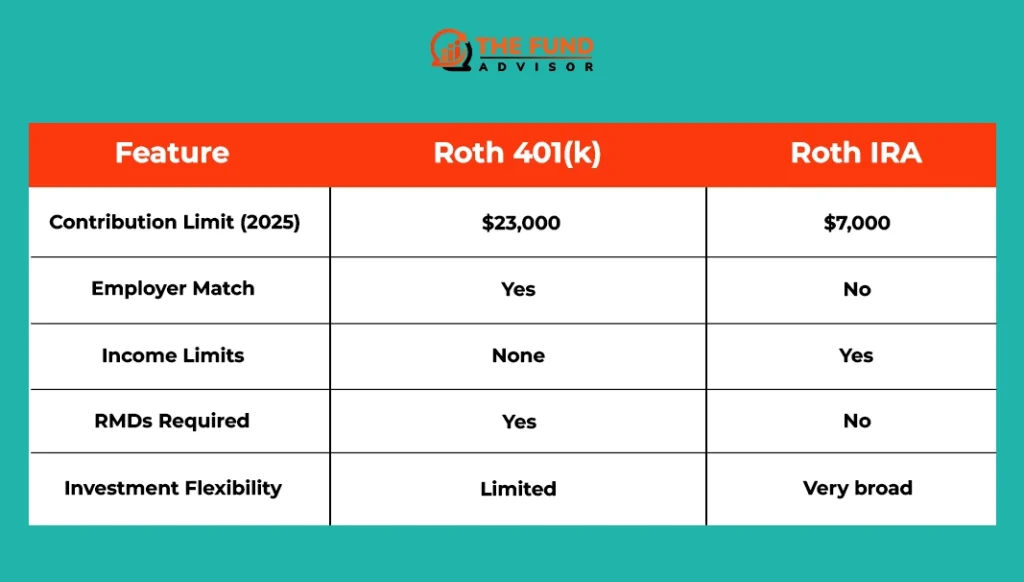
A Roth 401(k) is offered by an employer and allows much higher annual contributions — up to $30,500 in 2025 — including an employer match. A Roth IRA, on the other hand, is opened individually with a maximum contribution of just $7,000 per year (plus a $1,000 catch-up if you're 50 or older). This means people with steady jobs and good benefits often start with a Roth 401(k) to take full advantage of matching funds.
Must Read
Roth IRAs come with unique benefits that Roth 401(k)s don't offer. For example, you can withdraw your contributions at any time without penalties, and there are no required minimum distributions during your lifetime. Imagine needing emergency cash — with a Roth IRA, you can access what you've already put in without tax or penalty. A Roth 401(k) has stricter withdrawal rules in this regard.
On the other hand, the employer match in a Roth 401(k) is essentially free money, making it an excellent starting point. Consider a scenario: if your employer matches 50% of your contributions up to 3% of your salary, that match typically goes to a traditional 401(k) side of the account — meaning you'd owe taxes on those matched dollars when withdrawn.
 Roth IRA vs 401(k): Pros, Cons & Which One You Should Choose
So, are they different? Yes, but they're both valuable. You don't have to choose just one — many financially savvy people use both together. Here are a few simple tips: first, always contribute enough to your Roth 401(k) to capture the full employer match; second, open a Roth IRA for its flexible withdrawal rules; and third, compare your income against IRA eligibility limits to confirm you qualify.
By combining these two accounts strategically, you build a diversified tax-free nest egg that serves you well in retirement. The key is to start early, be consistent, and let compound growth work its magic over the years. Both accounts are designed with the everyday saver in mind — and using them together is one of the smartest moves you can make.