The topic of whether a MICR number is the same as an account number is both practical and widely discussed because it touches something nearly everyone interacts with — banking. Whether you're writing a check for the first time, setting up a direct deposit, or simply curious about the mysterious code on the bottom of your check, understanding this distinction can save you confusion and potential mistakes. It's a simple yet important piece of financial knowledge.
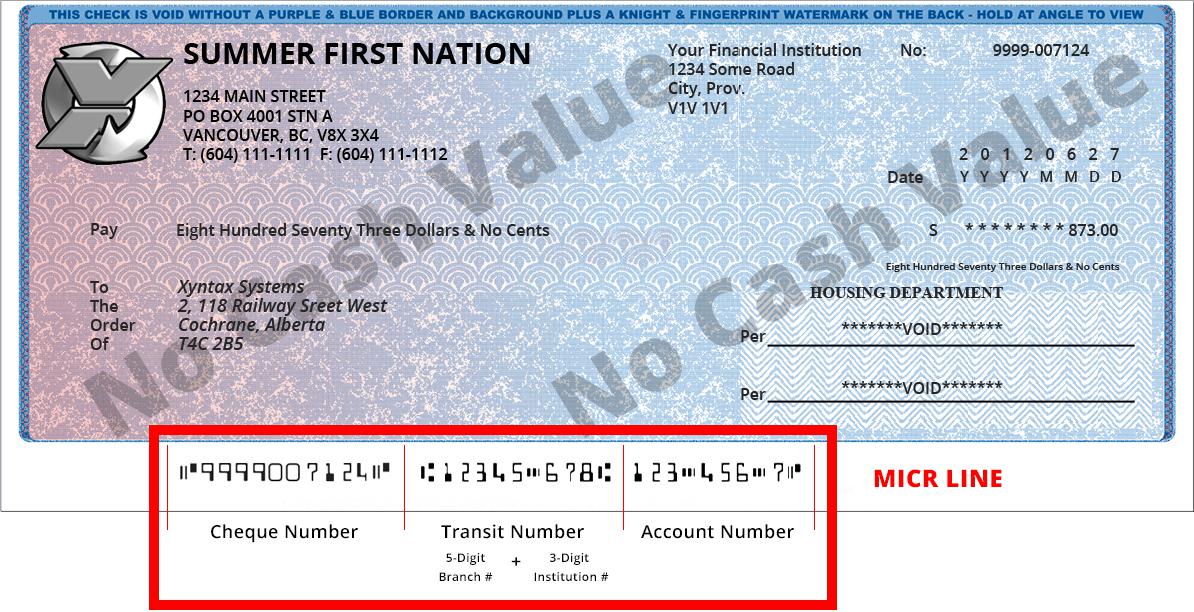
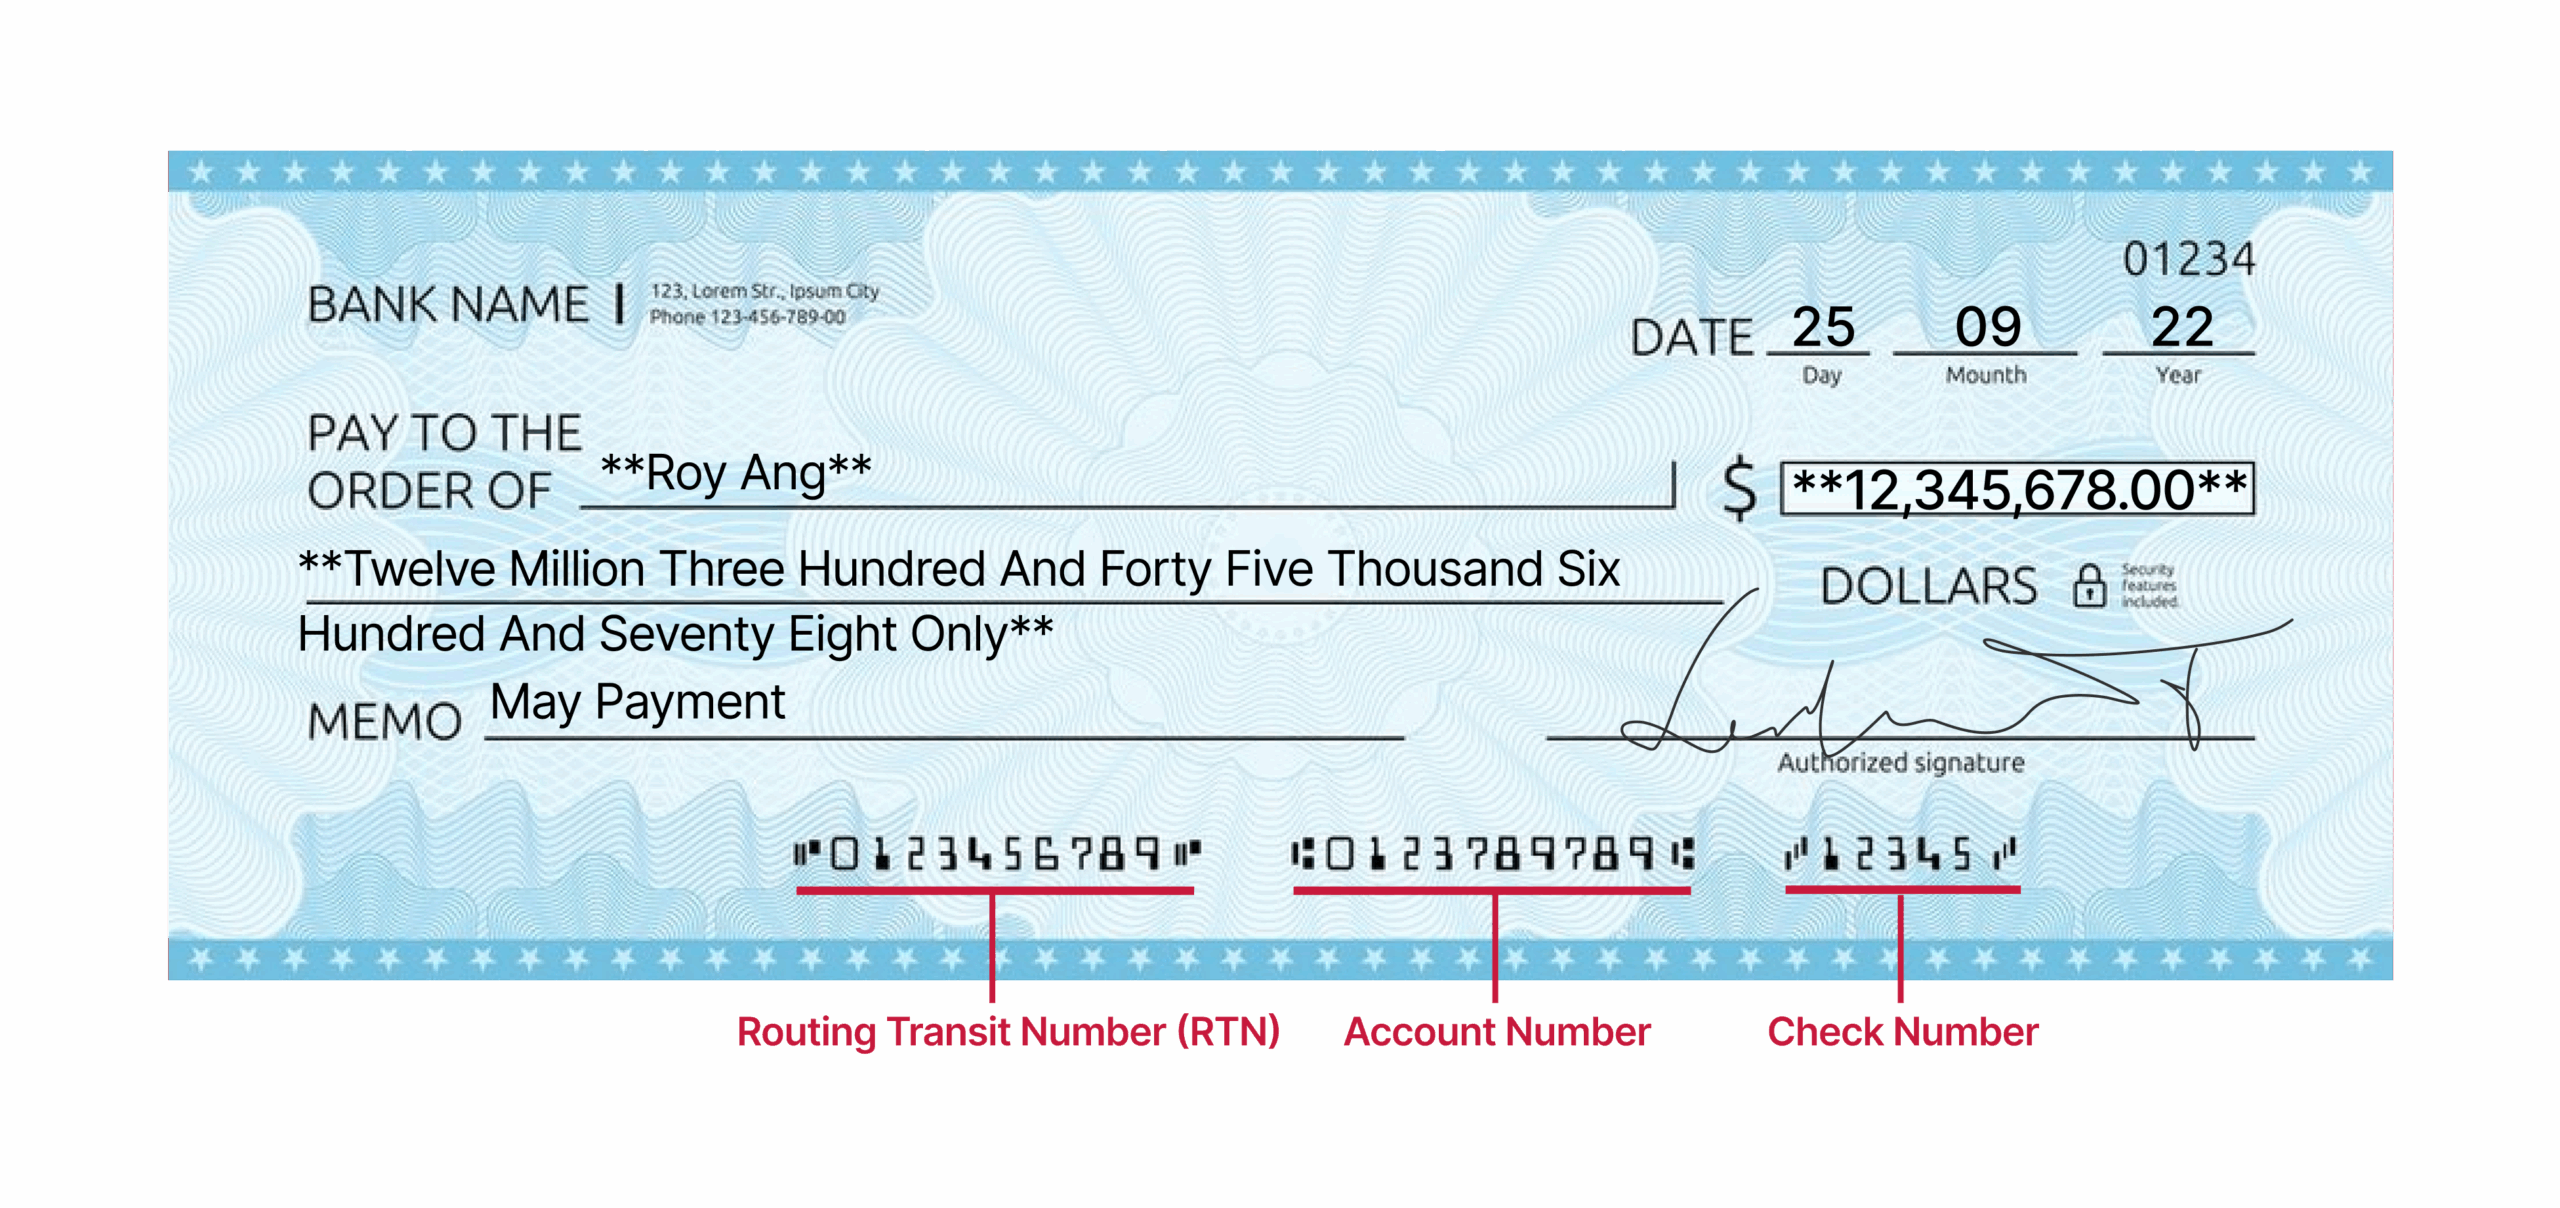
The answer is straightforward: no, a MICR number and an account number are not the same thing. The MICR (Magnetic Ink Character Recognition) number refers to the entire coding line printed at the bottom of a check in magnetic ink. It is a combination of three elements — the routing number, the account number, and the check number — all encoded together so that banks can process checks quickly and accurately using specialized scanners.
Your account number is just one part of that MICR line. It identifies your specific account at your bank, distinguishing it from every other customer's account. Think of it as your personal identifier within the banking system, while the routing number tells which financial institution your account belongs to. Together, they create a seamless system for transferring money safely.
Must Read
Here's a quick example to make it clearer: on a typical check, you'll notice three sets of numbers along the bottom. The first set enclosed by special symbols is the routing number (9 digits), the middle set is your account number, and the last set is the check number — which matches the number in the top corner. All three together form the MICR line that banks read electronically.
To find your MICR number, simply look at the bottom of any check from your account. You can also find your account number on your bank statement or online banking portal. If you have a mobile account without checks, your bank's routing and account numbers will still exist as part of their ACH system, but no physical MICR line will be printed.
 How to Deposit Your Tax Return into Your AOCU Account
The best tip is to separate these numbers carefully whenever you share financial details. For example, when setting up direct deposit, your employer needs your routing and account numbers — not your check number. Mixing these up can delay payments or cause errors. Always double-check which number corresponds to which purpose before sharing any banking information.
Keeping a basic understanding of banking codes like MICR and account numbers empowers you to handle daily financial transactions with confidence. It's a small piece of knowledge that pays off enormously whenever money is on the line, making your banking experience smoother and far less stressful.