Hey there! Ever wondered whether you should close that old credit card gathering dust in your drawer? It’s a surprisingly fun topic to explore, because the answer can help you save money, boost your credit score, and even simplify your financial life. Knowing when to say goodbye to a card can feel like a small victory in the quest for financial freedom.
The main purpose of closing a credit card is to take control of your credit profile. When a card isn’t being used, it may carry hidden fees or a high interest rate that weighs down your overall score. By eliminating those dead-end accounts, you reshape your credit mix and reduce unnecessary risk.
There are several advantages to this move. First, your credit utilization ratio improves because you have fewer total limits. Second, you avoid annual fees that often sneak up after the first year. Third, fewer open accounts can make it easier to track spending, giving you a clearer picture of your cash flow.
Must Read
Consider Sarah, a recent graduate who opened three cards for promotions. After a year, she realized only one was active. She closed the two dormant cards, saw her score jump by 30 points, and stopped paying surprise fees. Her experience shows how a simple decision can turn into a financial win.
 How to Cancel a Credit Card in 5 Steps - Personal Finance Library
Want a creative twist? Try a “virtual card” strategy. Keep a low‑limit card for occasional online purchases, but close the high‑limit one you never use. This gives you the safety of a backup while eliminating the temptation to overspend, all while keeping your credit history healthy.
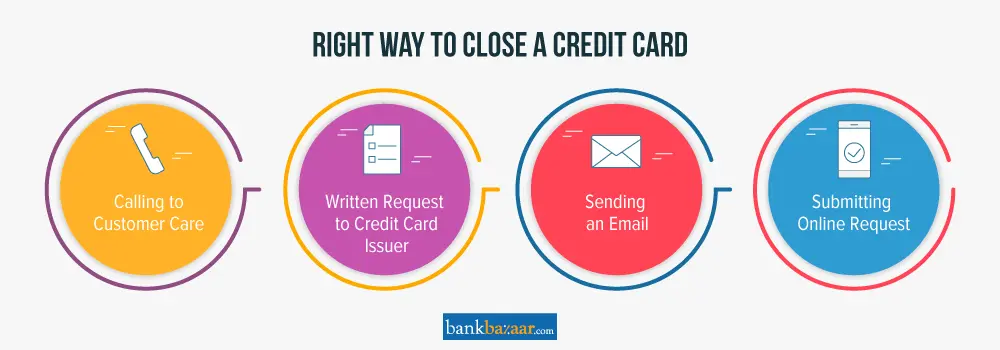
Ready to act? Start by checking your credit report for any balances. Pay off the statement, wait a month for the update, then contact the issuer to close the account. Finally, monitor your score for a few weeks to confirm the boost. Follow these steps, and you’ll enjoy a tidier wallet and a stronger credit profile.