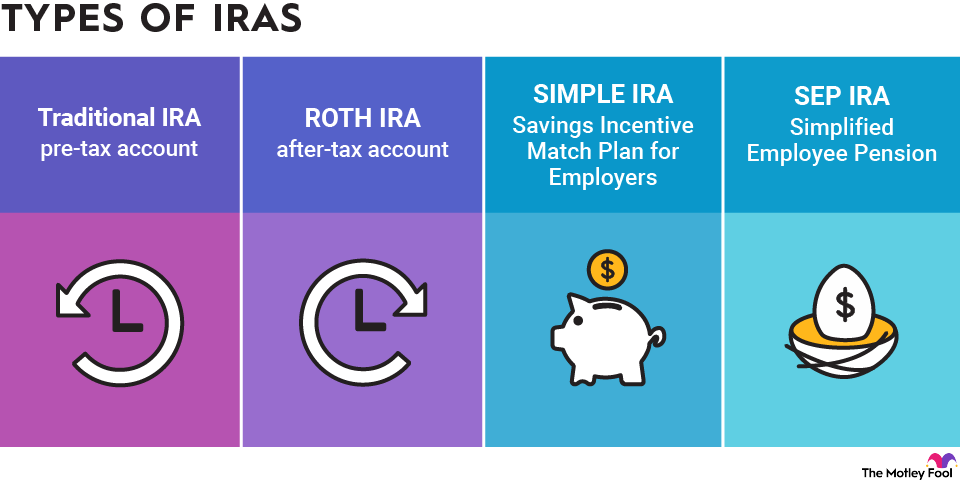
If you’ve ever stared at the alphabet soup of retirement plans and wondered, “Is a SIMPLE IRA the same as a Roth IRA?”, you’re about to get a friendly answer that’s perfect for choosing a tax‑saving option.
The SIMPLE IRA is a employer‑sponsored plan for tiny businesses (under 100 workers). It lets employees put in up to $16,000 (2025) and often adds a fixed match, giving a quick boost to your retirement fund.
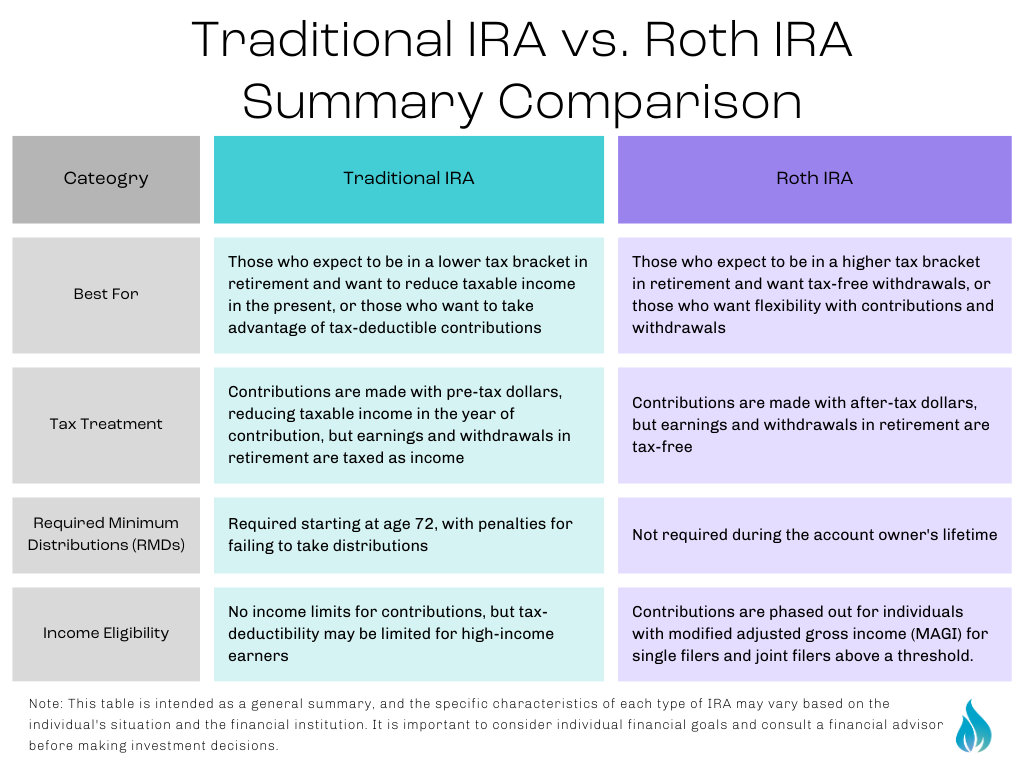
A Roth IRA is a personal account you open yourself. You fund it with after‑tax dollars, so all growth and later withdrawals are tax‑free if you meet the five‑year rule. It’s great for flexibility and no employer involvement.
Must Read
The main difference is when you pay taxes. A SIMPLE offers a pretax contribution that lowers this year’s taxable income, while a Roth’s benefit comes later when withdrawals are tax‑free. Contribution limits also differ: SIMPLE allows higher amounts, Roth caps at $7,000 (2025).
Imagine a young coder at a startup: she can max a SIMPLE with the company’s generous match, then open a Roth for extra savings. A freelance graphic designer with no employer plan can still build a tax‑free nest egg through a Roth alone.
 Asset Location + Asset Allocation: 2 Practical Approaches
To decide, ask: Do I need immediate tax relief and an employer match? If yes, choose SIMPLE. Do I value tax‑free growth and personal control? Go Roth. You can even use both—just track limits—and enjoy a balanced, future‑proof plan.
Before you jump in, double‑check a few criteria. First, confirm your employer offers a SIMPLE—small firms (<100 employees) are eligible. Second, review your income level for Roth eligibility; single filers can contribute until $150,000 (2025). Finally, think about your withdrawal timeline: SIMPLE penalties hit before 59½, while Roth earnings stay hidden until five years. A quick spreadsheet can model both taxes, fees, and growth to see which path fits your future goals. Whichever you choose, start early and let compounding do the heavy lifting. Your future self will thank you.