
Picture this: you borrowed money, promised to pay it back, and then life — or your love for avocado toast — got in the way. Congratulations, you've just defaulted on a loan. Buckle up, because it's about to get wild.
The Lender Notices (And They're Not Happy)
First, your lender sends you a friendly-ish reminder. Think of it as a polite slap on the wrist via email, like when your mom texts you a single thumbs-down emoji.
If you ignore that, the messages get louder — phone calls, letters, maybe a visit. At this stage, you might feel like a celebrity dodging paparazzi, except your fans are debt collectors.
Must Read
Your account will start accruing late fees and penalty charges. So not only do you owe the original amount, but now your debt is doing what your plants do when you forget to water them — growing without permission.
Your Credit Score Takes a Punch
Here's where it gets real serious: your credit score nose-dives. Imagine it as a stock market graph that someone kicked down a flight of stairs.
A missed payment can cost you over 100 points, and a full default might tank it by 200 or more. Your score becomes that kid in dodgeball who nobody picks — everyone's rejecting your applications for years.
 Getting Mortgage With Defaults: What You Need To Know
The default stays on your report for up to seven years. That's longer than most people stay on their chosen streaming platform without switching.
Collection Agencies Enter the Chat
After about 120 days of non-payment, your lender hands your debt to a collection agency. Congrats — your financial struggle now has a professional babysitter.
Collection agents call relentlessly, sometimes using tactics that make telemarketers look like gentle monks. They might even contact your friends and family, which is somehow both legal and deeply humiliating.
Story time: one guy in the US owed $80 and hid from collectors for decades. He eventually paid $160,000 in interest and fees. Let that marinate.
 What Happens If You Default on a Loan? Consequences Explained
Lawsuits and Wage Garnishments
If you play dead long enough, the lender may sue you in court. Imagine showing up to court in sweatpants because — let's be honest — you can't afford anything else.
If they win, they can garnish your wages, meaning up to 25% of your paycheck goes straight to them. Your boss gets to watch a stranger skim your pay while you wonder where your money went.
In some cases, they may also seize assets like your car or home. Suddenly, "my garage" becomes "their garage with their name." Awkward.
The Long-Term Aftermath
Defaulting makes future borrowing almost impossible for a while. Lenders will look at your file and say "absolutely not" with the energy of a bouncer at a VIP club.
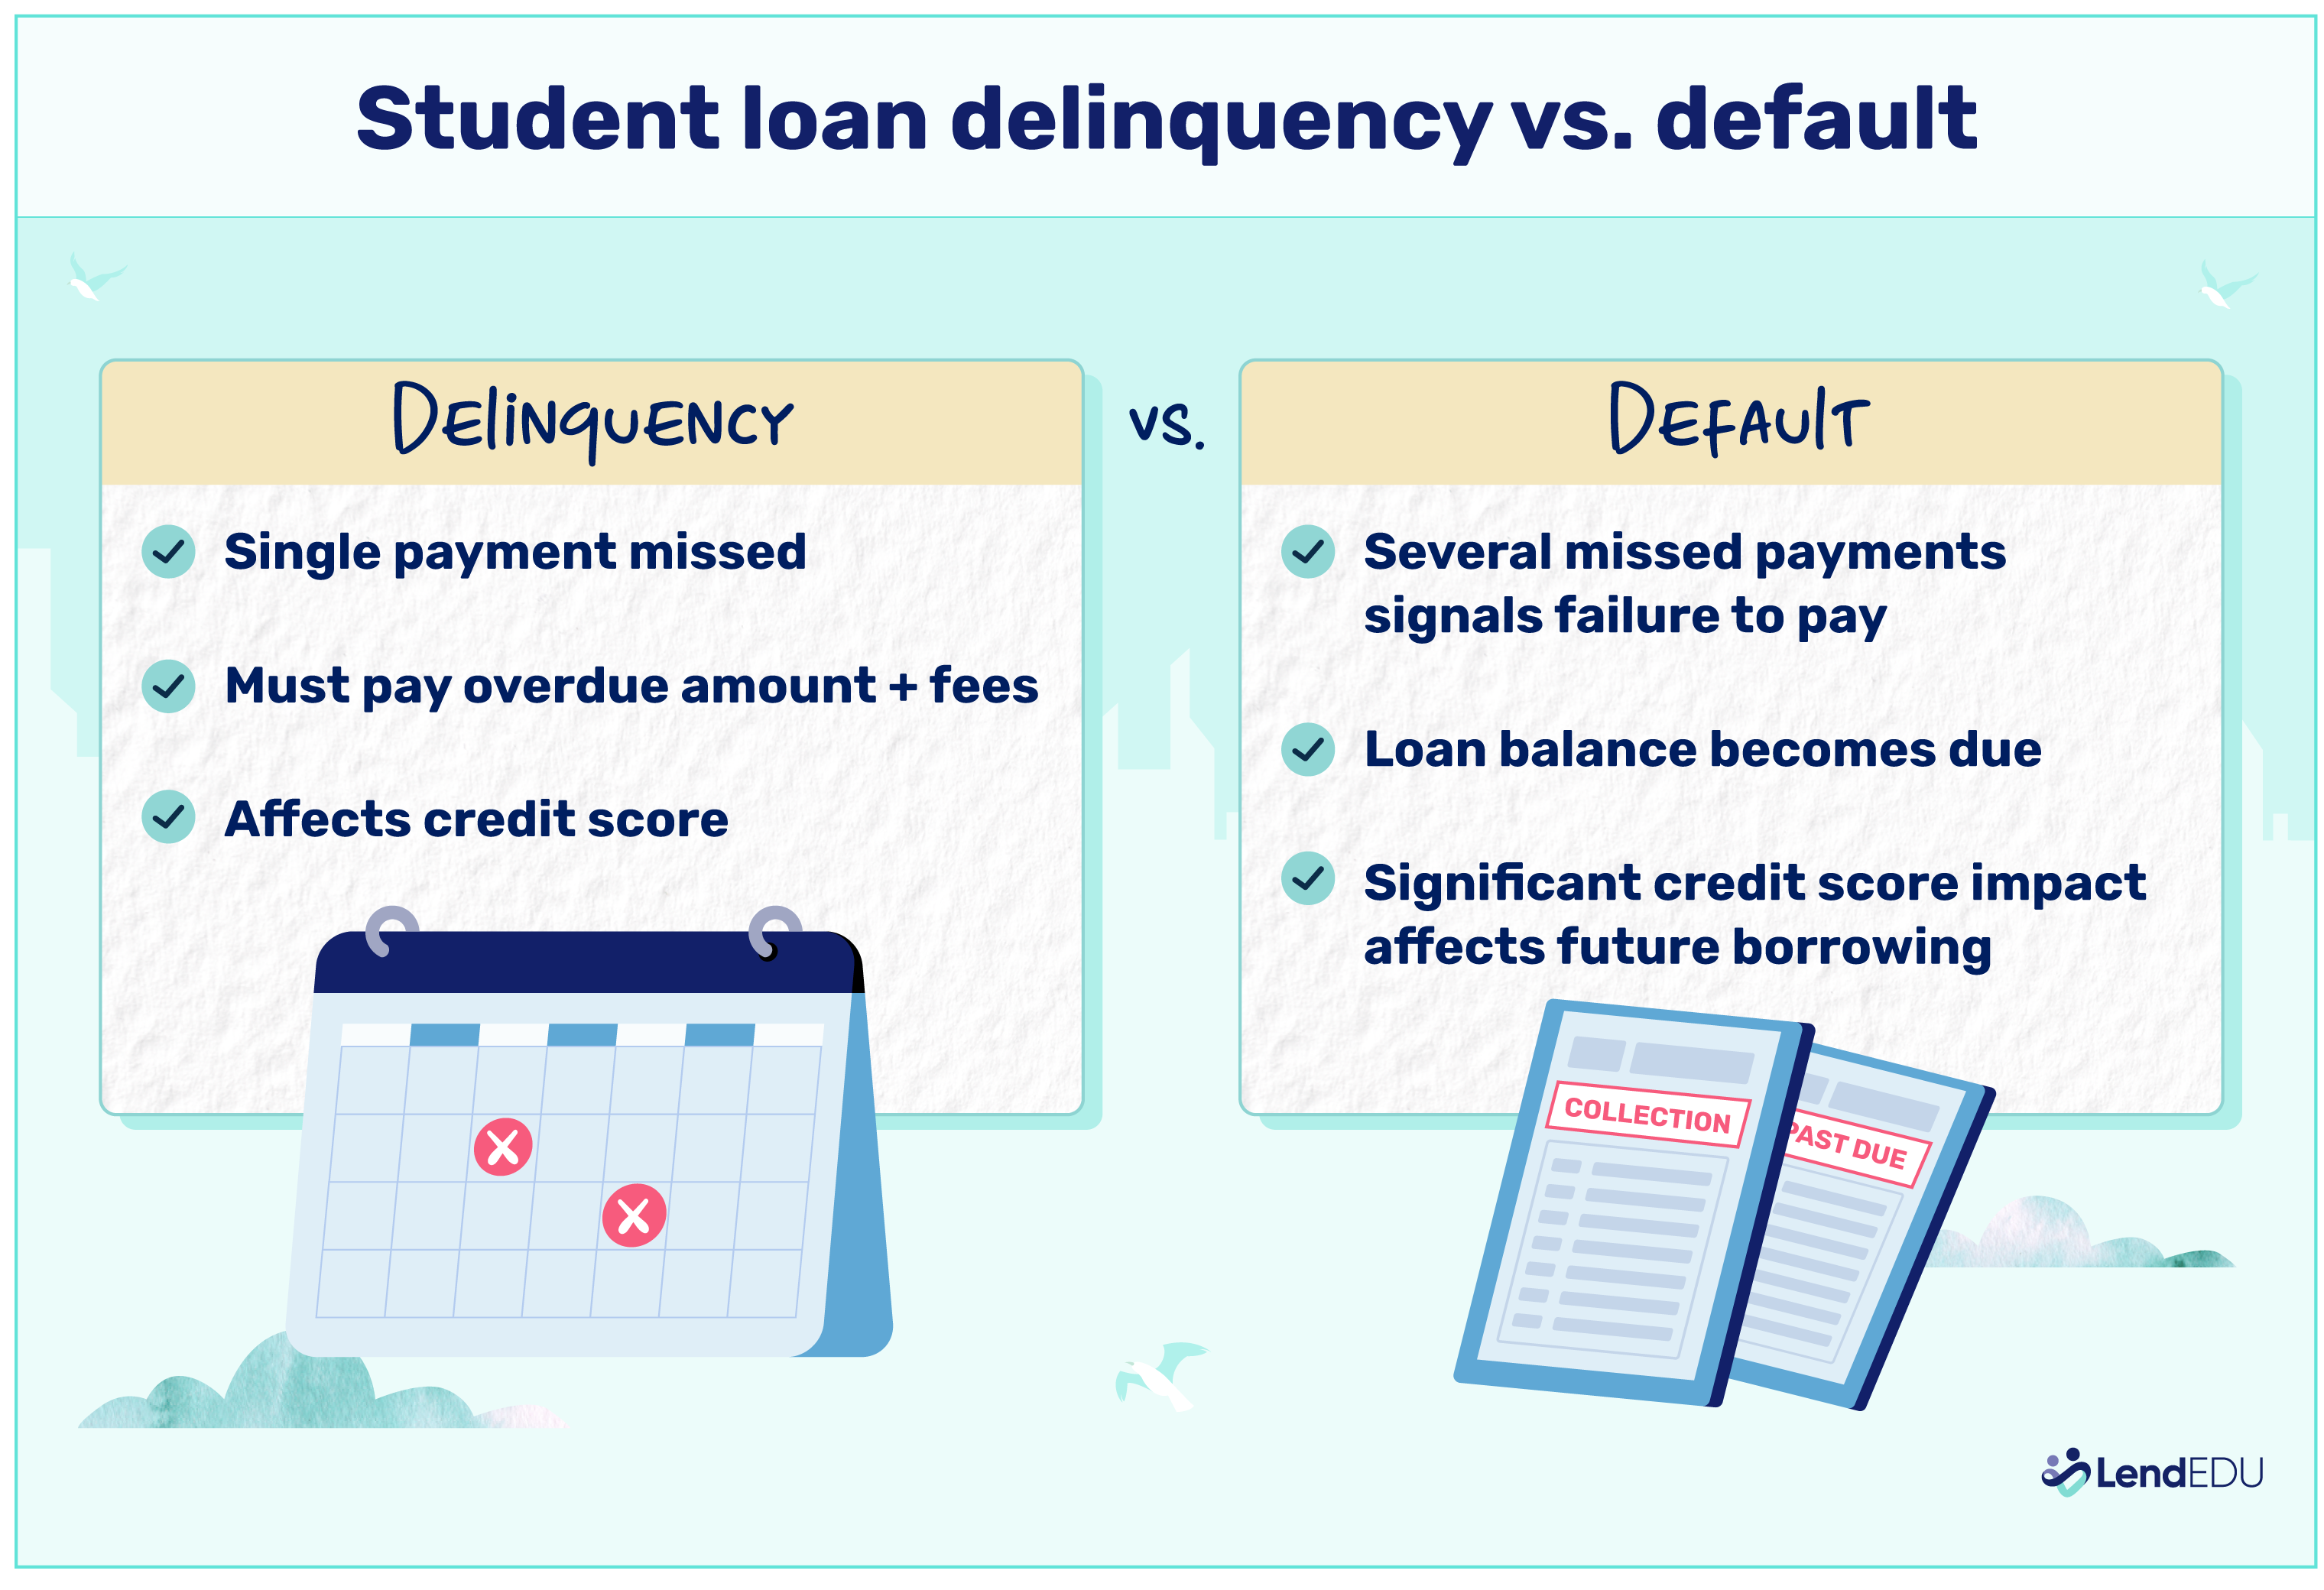 How to Recover from Private Student Loan Default: Consequences and
You might struggle to rent an apartment, get a phone plan, or even land certain jobs. Some employers do check credit scores — imagine losing your dream job because of a missed payment.
So What's the Fix?
The best move is to communicate with your lender early. Many pros would rather restructure your loan than chase you with lawyers.
Consider borrowing wisely only what you can repay, building an emergency fund, and getting advice when things get tough. A little effort now can save you from a dramatic financial soap opera later.
Remember: a default isn't a life sentence, but it sure makes life a lot more inconvenient. Handle your debt like you'd handle that hot espresso — carefully.