Okay, let's talk about something unexpected: your TransUnion credit report. Yeah, I said it. It's actually weirdly entertaining once you crack it open.
Think of this report as your financial diary. Someone's writing every money move you've ever made in it. Spooky, right?
First Things First — Grab It
Before you can read it, you need to get your hands on it. Head over to TransUnion's website and request a free copy. It's free once every twelve months, so no excuses.
Must Read
They might ask for some ID stuff. A few clicks later — boom. Your report lands in your inbox like a surprise birthday card. 🎉
It's Basically Four Big Sections
Here's the fun part. Your report is organized into four main sections. Think of them as chapters in a mystery novel.
There's your personal info, credit inquiries, account details, and public records. Each one tells a different part of your money story. Let's break them down.
 How To Read TransUnion Credit Report (2025) - YouTube
Section 1: The Personal Stuff
This section shows your name, address, and Social Security number. Look closely — errors hide here all the time. A misspelled name? A wrong address? Fix it fast.
Funny fact: even one typo can mess with your score. Your data should be spotless. Think of it as your financial ID card.
Section 2: Who's Been Poking Around?
This is the credit inquiries section, and it's fascinating. Hard inquiries happen when a lender checks your credit for a big decision — like a car loan. Soft inquiries are innocent little peeks, like checking your own score.
Too many hard inquiries? That'll raise eyebrows. So only let lenders peek when you're serious about borrowing.
 Buy Now, Pay Later | TransUnion
Section 3: Show Me the Accounts
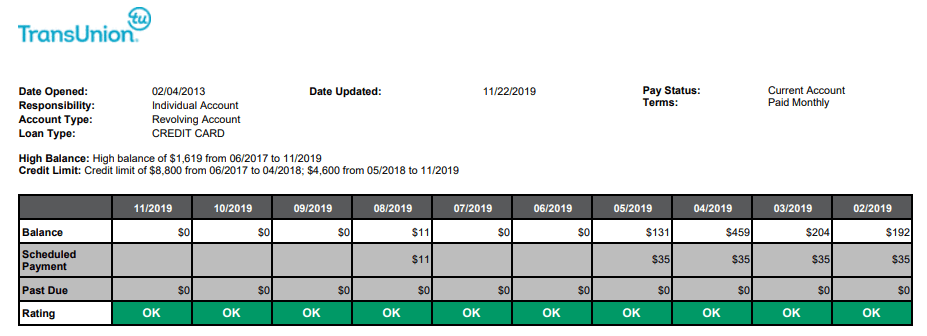
Here's the meatiest part of your report. Every credit card, loan, and mortgage you've ever had shows up here. Look at balances, payment history, and statuses.
Green lights mean on-time payments. Red flags mean trouble. This section basically screams whether you're a financial rockstar or a serial late-payer.
Section 4: The Dark Alley of Public Records
This section covers bankruptcies, liens, and civil judgments. Most people's reports are empty here — and that's a beautiful thing. If something shows up, deal with it yesterday.
It's like finding a stain on a white shirt. You notice it immediately. Keep this section clean, and your financial rep stays shiny.
 A Guide to Reading Your Credit Report
Your Score Is the Grand Finale
TransUnion doesn't give your actual credit score on the report itself. It gives you the ingredients. You connect the dots yourself — or use a scoring tool.
Scores range from 300 to 850. Higher means lenders will practically roll out a red carpet. Lower means they'll slam the door before you finish knocking.
So Why Bother?
Reading your report isn't boring — it's surprisingly addictive. You spot errors, catch fraud, and see the story your money tells. It's like forensic accounting, but for your own life.
Check it regularly. Stay curious. Your credit report is your money autobiography — and you deserve a good read.