Okay, let's talk about something that might sound boring but is actually kind of thrilling: a second mortgage. Imagine borrowing more money against the home you already own. It's like dipping into a well you thought had run dry, but surprise — there's still water down there.
What Even Is A Second Mortgage?
A second mortgage lets you borrow against your home's equity. Equity is the difference between what your house is worth and what you still owe on it. It's basically free money sleeping in your walls. Kind of wild, right?
Two popular flavors exist: a home equity loan and a heloc. The loan gives you a lump sum. The heloc is more like a credit card tied to your house. Choose your weapon wisely.
Must Read
Crack The Equity Code
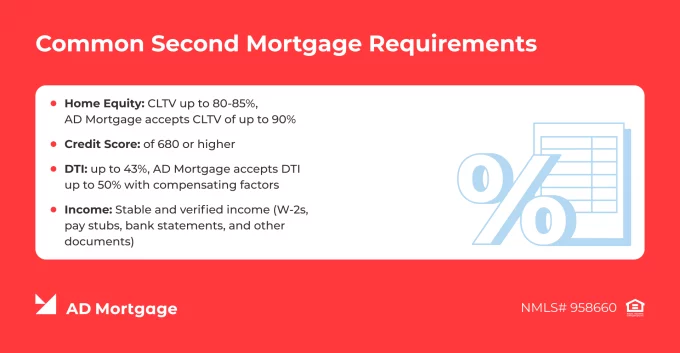
Lenders will peek at how much equity you've built up. Most want at least 20% equity sitting pretty. If your home has tanked in value, your equity might have taken a nosedive too. So mind that market, friend.
Your Credit Score Better Flex
Want a second mortgage? Your credit score needs to impress. Most lenders look for at least a 660, though 700+ makes them swoon. Excellent credit could unlock seriously juicy rates. Go chase that number!
 Second Mortgage | Newfi
Pro tip: pay off small debts first. Even a few points added to your score can save you thousands. Tiny moves, massive payoff.
Show The Money 💰
Lenders love to see that you actually earn a living. They'll want proof of income — pay stubs, tax returns, the whole show. A stable job history? Chef's kiss. They want to know you can handle extra payments without panicking.
Your debt-to-income ratio matters too. It's basically how much debt you carry compared to what you make. Most lenders want that number 43% or below. Slash your expenses a little and watch it drop.
 PPT - Mortgage Company Surrey PowerPoint Presentation, free download
Paperwork Is (Not) Fun
Expect to juggle documents like a circus clown. Bank statements, employment verification, property appraisals — oh my. Keep everything organized or lose your mind.
Watch The Fine Print
A second mortgage sits behind your first in priority. If you default, the first lender gets paid first. It's like cutting in line, but legally. Also note the second may carry a steeper interest rate for that exact reason.
 What Is a Second Mortgage? 2026 Broker Guide | AD Mortgage
Closing costs sneak in too. Budget for appraisal fees, origination fees, and more. Nobody likes surprise bills. Plan ahead and keep a small cushion.
So… Are You Ready?
Qualifying for a second mortgage isn't rocket science, but it demands some homework. Build equity, boost your credit, prove your income, and tame that debt-to-income ratio. Do all that and lenders will practically roll out the red carpet for you. Your home is sitting on a fortune — time to unlock it!
Now go make that quirky little money vault in your walls start earning its keep. You've got this!